VWAP Trading Strategy
This strategy is a trading strategy based on EMA, VWAP, and volume. The main idea is to generate opening signals when the closing price breaks through VWAP and EMA, and the trading volume is greater than the previous…
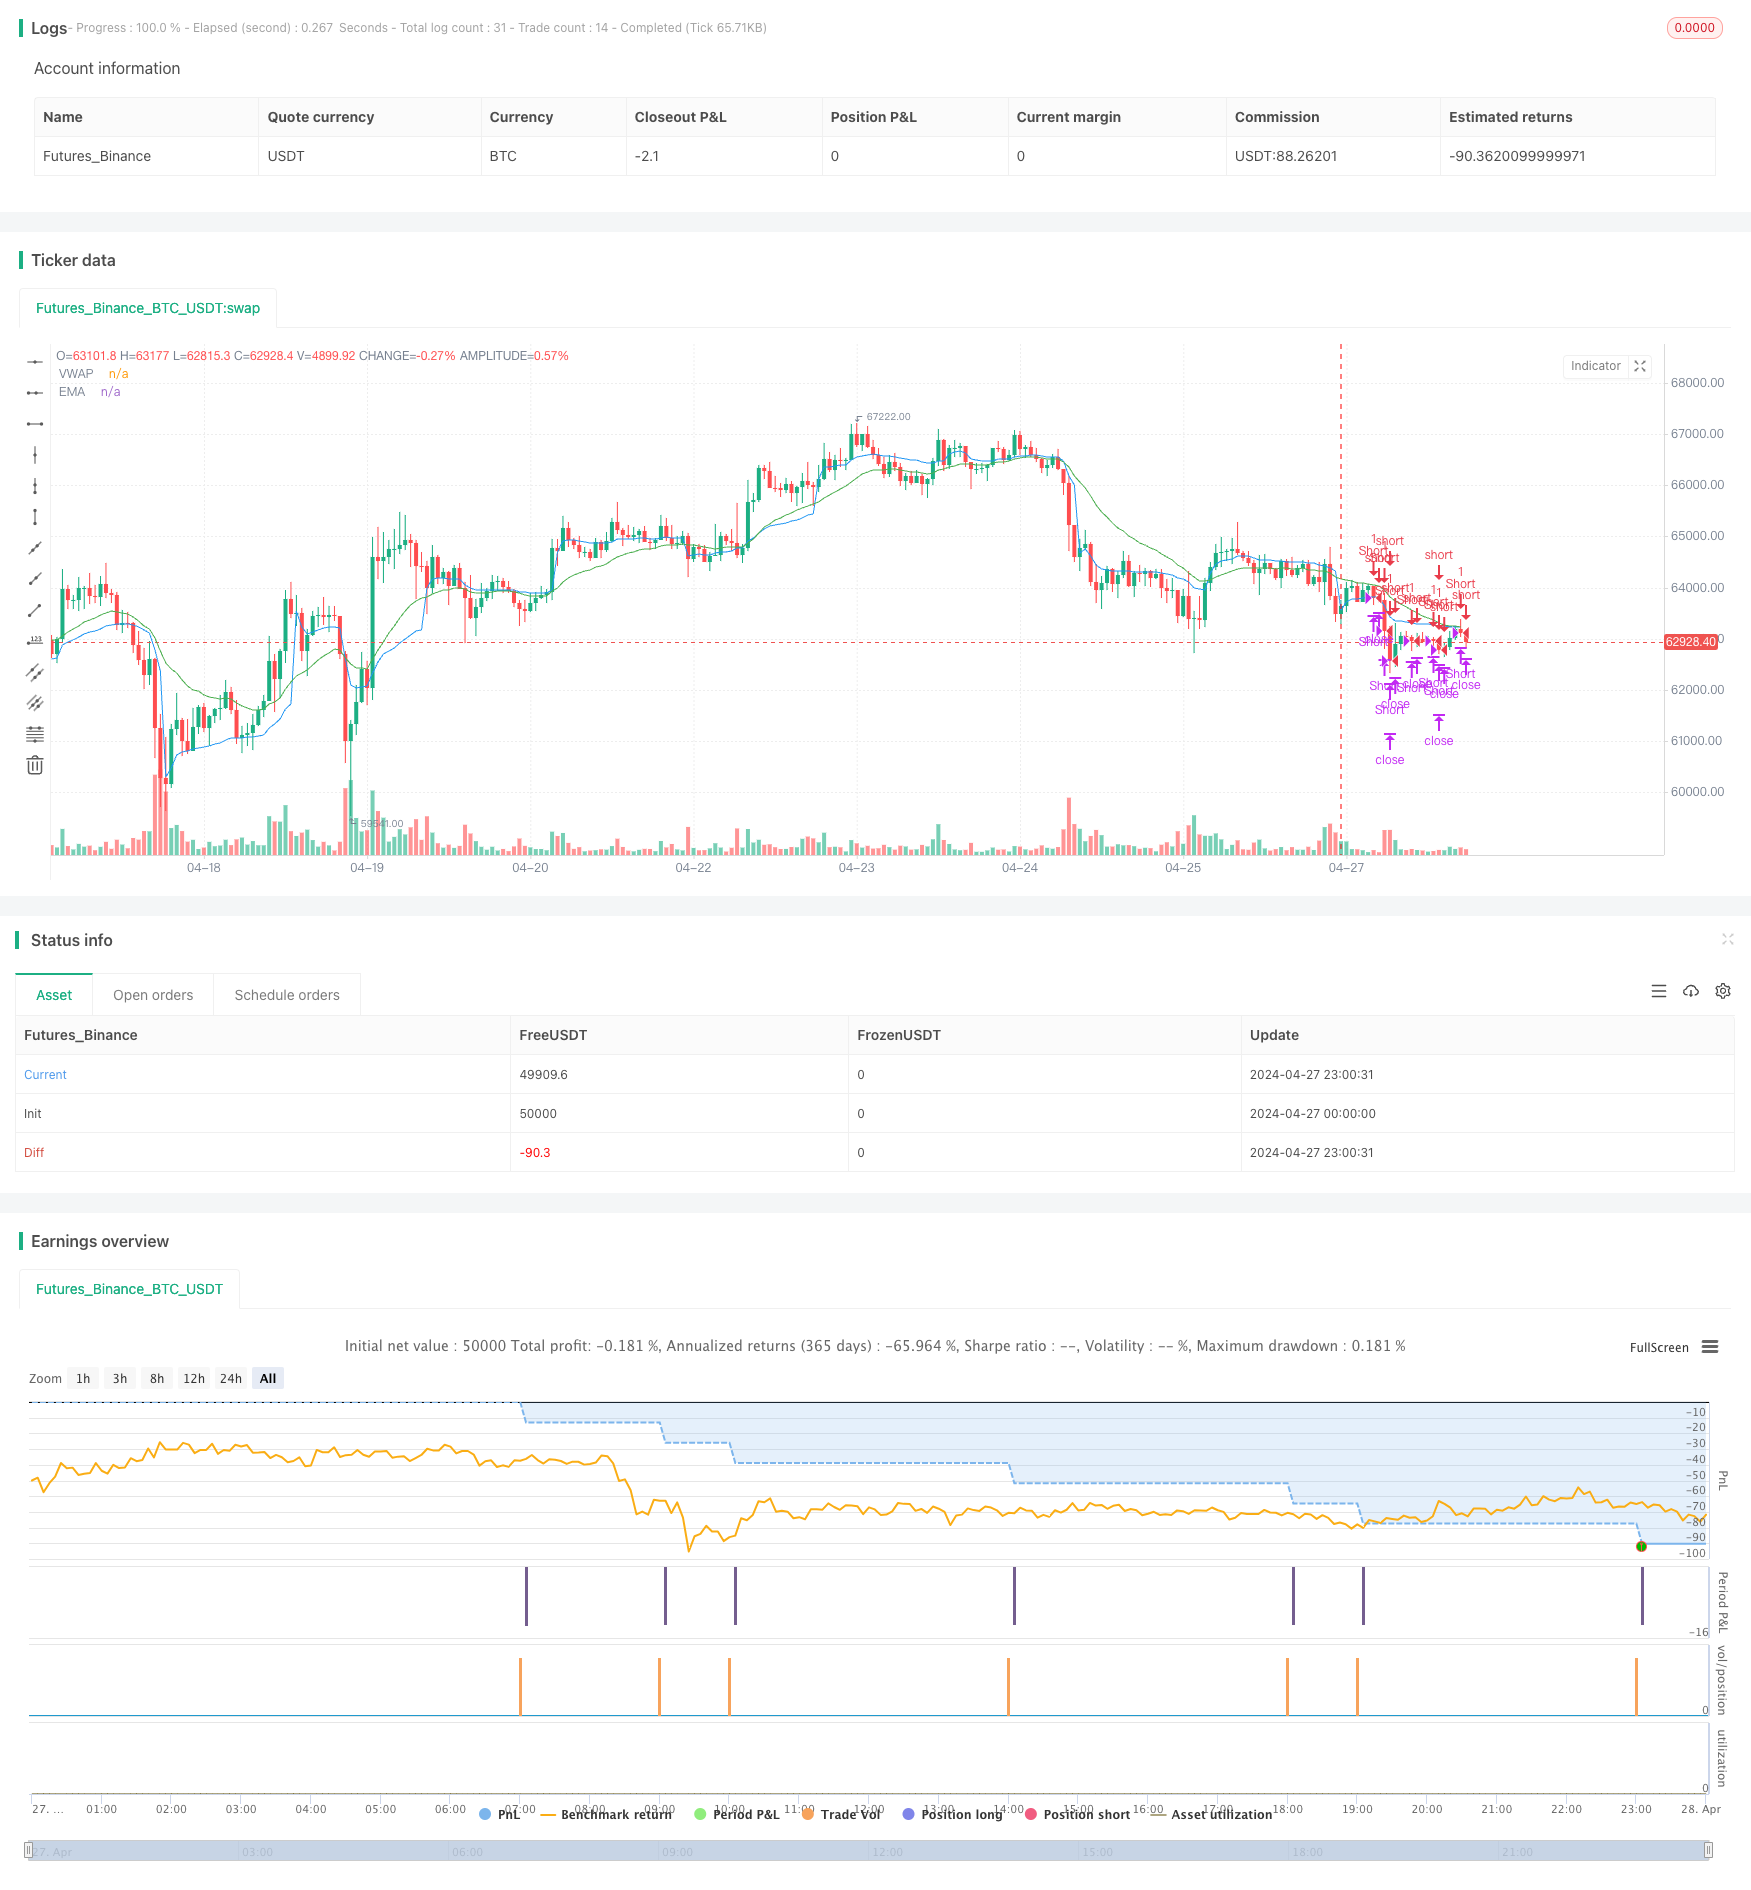
Overview
This strategy is a trading strategy based on EMA, VWAP, and volume. The main idea is to generate opening signals when the closing price breaks through VWAP and EMA, and the trading volume is greater than the previous candle's volume within a specific trading time. It also sets stop loss and take profit, as well as conditions for closing positions within a specific time period.
Strategy Principle
- Calculate EMA and VWAP indicators.
- Determine whether it is within the specified trading time.
- Long entry condition: closing price is greater than VWAP and EMA, volume is greater than the previous candle, and closing price is greater than opening price.
- Short entry condition: closing price is less than VWAP and EMA, volume is greater than the previous candle, and opening price is greater than closing price.
- Long exit condition: closing price falls below VWAP or EMA, reaches stop loss or take profit levels, or reaches the specified exit time.
- Short exit condition: closing price breaks above VWAP or EMA, reaches stop loss or take profit levels, or reaches the specified exit time.
Strategy Advantages
- It considers price trend (EMA), market fair value (VWAP), and trading volume simultaneously, making the opening conditions more strict, which helps to improve the strategy's win rate.
- It sets stop loss and take profit to control risk and lock in profits.
- It limits trading time and exit time to avoid risks during non-trading hours and overnight holding.
Strategy Risks
- The strategy may not perform well in a volatile market, as frequent breakthroughs and pullbacks may lead to multiple openings and closings, increasing transaction costs and slippage.
- The stop loss level is fixed, which may be triggered prematurely when the market fluctuates violently, causing the strategy to suffer significant losses.
- The strategy does not consider actual market depth and order status, which may face issues such as slippage and opening failures in real trading.
Strategy Optimization Direction
- Consider adding more filtering conditions, such as ATR and RSI indicators, to further confirm the strength of the trend and momentum.
- Stop loss and take profit levels can be set dynamically, such as following ATR or percentage stop loss, to adapt to different market volatilities.
- Optimize parameters, such as EMA length, VWAP source, stop loss and take profit levels, etc., to improve the stability and profitability of the strategy.
- Consider adding position management, such as adjusting the opening volume according to volatility or capital ratio, to control overall risk.
Summary
By comprehensively considering price trends, market fair value, and trading volume, this strategy trades within a specific trading time. Although stop loss, take profit, and limited trading time are set, it still needs to pay attention to risks such as volatile markets and slippage in actual application. In the future, the strategy's robustness and profitability can be improved by adding more filtering conditions, optimizing parameters, and managing positions.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_int_1 | 21 | EMA Length |
| v_input_source_1_hlc3 | 0 | VWAP Source: hlc3 | high | low | open | hl2 | close | hlcc4 | ohlc4 |
| v_input_float_1 | 100 | Stop Loss (points) |
| v_input_float_2 | 200 | Target (points) |
| v_input_1 | 0950-1430 | Only take entry during |
| v_input_2 | 1515-1525 | Exit Trade |
Source Pine Script
/*backtest
start: 2024-04-27 00:00:00
end: 2024-04-28 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("EMA, VWAP, Volume Strategy", overlay=true, process_orders_on_close=true)

// Inputs
emaLength = input.int(21, title="EMA Length")
vwapSource = input.source(defval=hlc3, title='VWAP Source')
stopLossPoints = input.float(100, title="Stop Loss (points)")
targetPoints = input.float(200, title="Target (points)")
session = input("0950-1430", title='Only take entry during')
exit = input(defval='1515-1525', title='Exit Trade')

tradein = not na(time(timeframe.period, session))
exit_time = not na(time(timeframe.period, exit))

// Calculate indicators
ema = ta.ema(close, emaLength)
vwapValue = ta.vwap(vwapSource)

// Entry Conditions
longCondition = close > vwapValue and close > ema and volume > volume[1] and close > open and tradein
shortCondition = close < vwapValue and close < ema and volume > volume[1] and open > close and tradein

// Exit Conditions
longExitCondition = ta.crossunder(close, vwapValue) or ta.crossunder(close, ema) or close - strategy.position_avg_price >= targetPoints or close - strategy.position_avg_price <= -stopLossPoints or exit_time
shortExitCondition = ta.crossover(close, vwapValue) or ta.crossover(close, ema) or strategy.position_avg_price - close >= targetPoints or strategy.position_avg_price - close <= -stopLossPoints or exit_time

// Plotting
plot(vwapValue, color=color.blue, title="VWAP")
plot(ema, color=color.green, title="EMA")

// Strategy
if longCondition
    strategy.entry("Long", strategy.long)

if shortCondition
    strategy.entry("Short", strategy.short)

if longExitCondition
    strategy.close('Long', immediately=true)

if shortExitCondition
    strategy.close("Short", immediately=true)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-04-29. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/VWAP-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Multi Filter Trend Breakthrough Smart Moving Average Trading StrategyPine Script · Breakout · 1h
- Dynamic Multi indicator Quantitative Trading StrategyPine Script · Breakout · 1d
- Cross Timeframe SuperTrend Breakout StrategyPine Script · Breakout · 1h
- Multi Indicator Breakout and Reversal Trading Strategy A Dual Entry System with Opening Range OptimizationPine Script · Breakout · 1h
- Trend Following Strategy Based on Moving Average BreakoutPine Script · Breakout · 1h
- Dual MA Momentum Breakout StrategyPine Script · Breakout · 1h