VWAP Volatility Reversal Strategy with Standard Deviation Channel Breakout System
This strategy is a trading system based on VWAP (Volume-Weighted Average Price) and standard deviation channels, which identifies reversal patterns at channel boundaries for trade execution. The strategy combines…
Overview
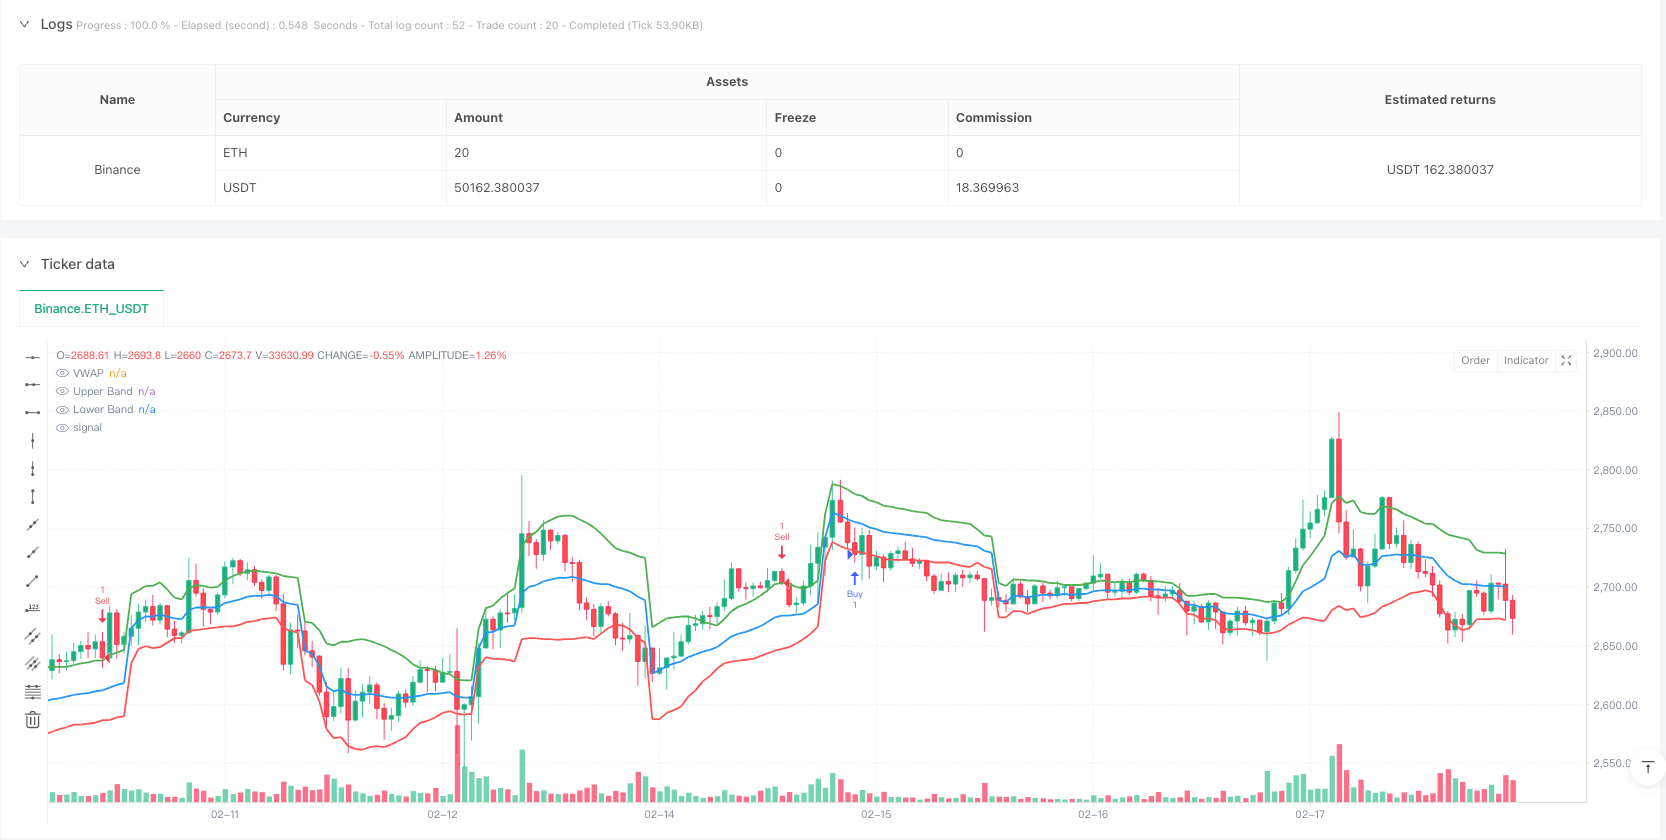
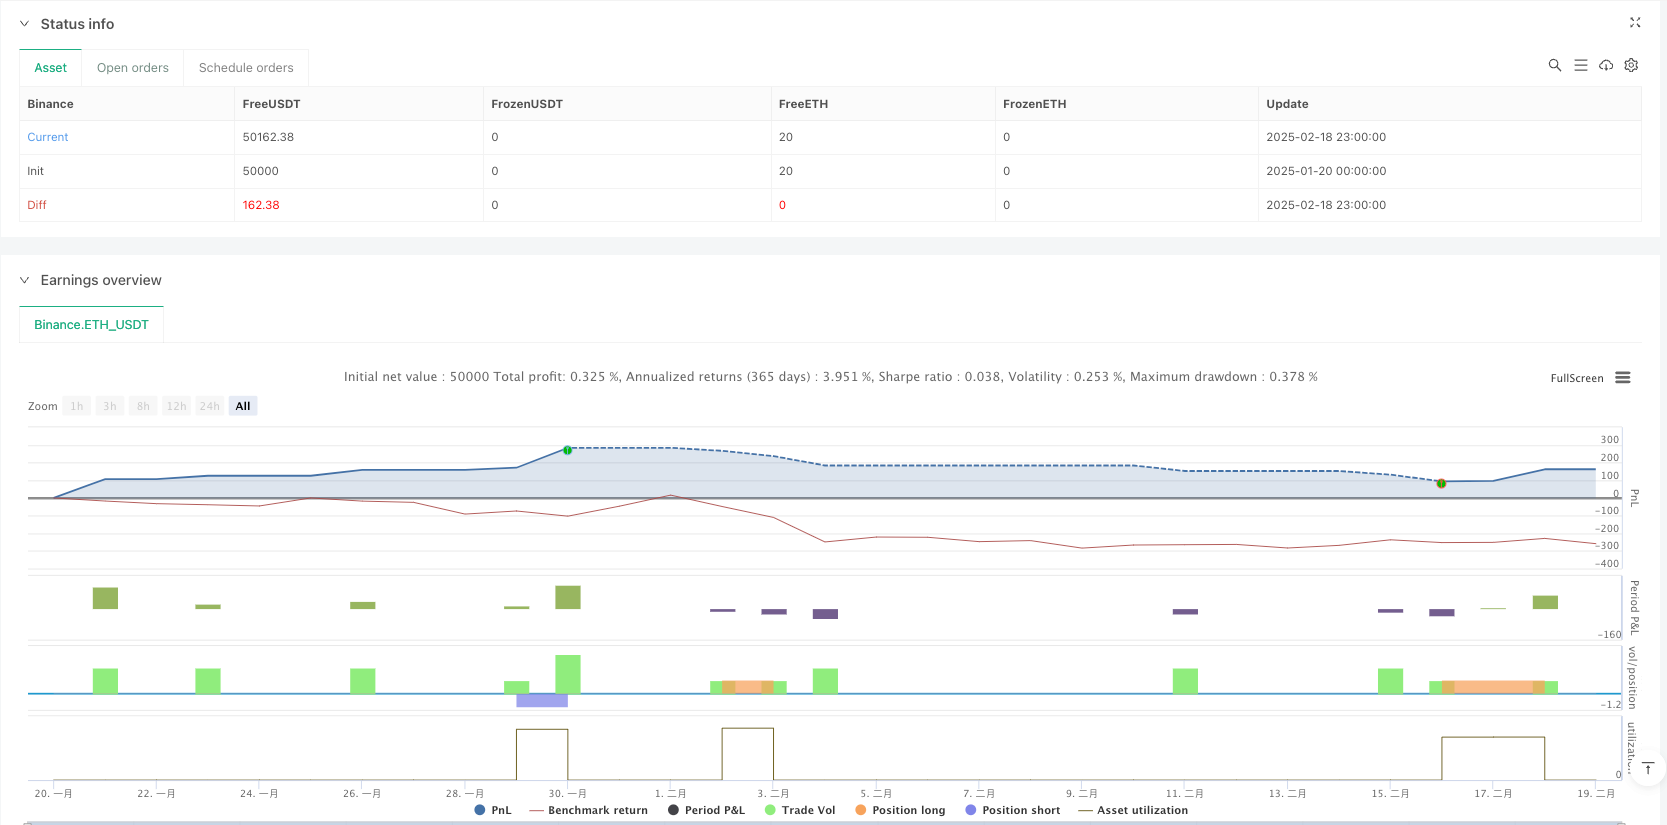
This strategy is a trading system based on VWAP (Volume-Weighted Average Price) and standard deviation channels, which identifies reversal patterns at channel boundaries for trade execution. The strategy combines momentum and mean reversion trading concepts, capturing opportunities when prices break through key technical levels.
Strategy Principles
The core of the strategy uses VWAP as a price pivot, constructing upper and lower channels using 20-period standard deviation. It looks for long opportunities near the lower band and short opportunities near the upper band. Specifically:
- Long entry: Price forms a bullish reversal pattern near the lower band, then breaks above the previous bullish candle's high
- Short entry: Price forms a bearish pattern near the upper band, then breaks below the previous bearish candle's low
- Take profit: VWAP and upper band for longs, lower band for shorts
- Stop loss: Below the reversal bullish candle for longs, above the reversal bearish candle for shorts
Strategy Advantages
- Combines benefits of trend-following and reversal trading, capturing both trend continuation and reversal opportunities
- Uses VWAP as core indicator, better reflecting true market supply and demand
- Implements staged profit-taking, realizing gains at different price levels
- Reasonable stop-loss settings for effective risk control
- Clear strategy logic with simple parameter settings, easy to understand and execute
Strategy Risks
- May trigger frequent stop losses in highly volatile markets
- Can generate excessive false signals during consolidation phases
- Sensitive to VWAP calculation timeframe
- Standard deviation channel width may not suit all market conditions
- Might miss some significant trending opportunities
Strategy Optimization Directions
- Introduce volume filters to improve signal quality
- Add trend confirmation indicators, such as moving average systems
- Dynamically adjust standard deviation periods to adapt to different market environments
- Optimize staged profit-taking ratios to enhance overall returns
- Add time filters to avoid trading during unfavorable periods
- Consider adding volatility indicators to optimize position management
Summary
This is a complete trading system combining VWAP, standard deviation channels, and price patterns. The strategy trades by seeking reversal signals at key price levels, managing risk through staged profit-taking and reasonable stop losses. While it has certain limitations, the suggested optimization directions can further enhance the strategy's stability and profitability. The strategy is suitable for markets with higher volatility and represents a worthy trading system for medium to long-term traders.
Source Pine Script
/*backtest
start: 2025-01-20 00:00:00
end: 2025-02-19 00:00:00
period: 1h
basePeriod: 1h
exchanges: [{"eid":"Binance","currency":"ETH_USDT"}]
*/

//@version=6
strategy("VRS Strategy", overlay=true)

// Calculate VWAP
vwapValue = ta.vwap(close)

// Calculate standard deviation for the bands
stdDev = ta.stdev(close, 20) // 20-period standard deviation for bands
upperBand = vwapValue + stdDev
lowerBand = vwapValue - stdDev

// Plot VWAP and its bands
plot(vwapValue, color=color.blue, title="VWAP", linewidth=2)
plot(upperBand, color=color.new(color.green, 0), title="Upper Band", linewidth=2)
plot(lowerBand, color=color.new(color.red, 0), title="Lower Band", linewidth=2)

// Signal Conditions
var float previousGreenCandleHigh = na
var float previousGreenCandleLow = na
var float previousRedCandleLow = na

// Detect bearish candle close below lower band
bearishCloseBelowLower = close[1] < lowerBand and close[1] < open[1]

// Detect bullish reversal candle after a bearish close below lower band
bullishCandle = close > open and low < lowerBand // Ensure it's near the lower band
candleReversalCondition = bearishCloseBelowLower and bullishCandle

if (candleReversalCondition)
    previousGreenCandleHigh := high[1]  // Capture the high of the previous green candle
    previousGreenCandleLow := low[1]     // Capture the low of the previous green candle
    previousRedCandleLow := na            // Reset previous red candle low

// Buy entry condition: next candle breaks the high of the previous green candle
buyEntryCondition = not na(previousGreenCandleHigh) and close > previousGreenCandleHigh

if (buyEntryCondition)
    // Set stop loss below the previous green candle
    stopLoss = previousGreenCandleLow
    risk = close - stopLoss // Calculate risk for position sizing

    // Target Levels
    target1 = vwapValue // Target 1 is at VWAP
    target2 = upperBand  // Target 2 is at the upper band

    // Ensure we only enter the trade near the lower band
    if (close < lowerBand)
        strategy.entry("Buy", strategy.long)

        // Set exit conditions based on targets
        strategy.exit("Take Profit 1", from_entry="Buy", limit=target1)
        strategy.exit("Take Profit 2", from_entry="Buy", limit=target2)
        strategy.exit("Stop Loss", from_entry="Buy", stop=stopLoss)

// Sell signal condition: Wait for a bearish candle near the upper band
bearishCandle = close < open and high > upperBand // A bearish candle should be formed near the upper band
sellSignalCondition = bearishCandle

if (sellSignalCondition)
    previousRedCandleLow := low[1] // Capture the low of the current bearish candle

    // Sell entry condition: next candle breaks the low of the previous bearish candle
    sellEntryCondition = not na(previousRedCandleLow) and close < previousRedCandleLow

    if (sellEntryCondition)
        // Set stop loss above the previous bearish candle
        stopLossSell = previousRedCandleLow + (high[1] - previousRedCandleLow) // Set stop loss above the bearish candle
        targetSell = lowerBand // Target for sell is at the lower band

        // Ensure we only enter the trade near the upper band
        if (close > upperBand)
            strategy.entry("Sell", strategy.short)

            // Set exit conditions for sell
            strategy.exit("Take Profit Sell", from_entry="Sell", limit=targetSell)
            strategy.exit("Stop Loss Sell", from_entry="Sell", stop=stopLossSell)

// Reset previous values when a trade occurs
if (strategy.position_size > 0)
    previousGreenCandleHigh := na
    previousGreenCandleLow := na
previousRedCandleLow := naPublished by ianzeng123 on the FMZ strategy square · last modified 2025-02-20. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/VWAP-Volatility-Reversal-Strategy-with-Standard-Deviation-Channel-Breakout-System.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Multi factor Intelligent Trading StrategyPine Script · Breakout · 1d
- Momentum Breakout Trading Strategy 435896Pine Script · Breakout · 1d
- Moving Average Based Supply Demand Zone Trading System with Dynamic Risk ManagementPine Script · Breakout · 1h
- Multi Filter Trend Breakthrough Smart Moving Average Trading StrategyPine Script · Breakout · 1h
- Advanced Long Only Dynamic Trendline Breakout StrategyPine Script · Breakout · 1d
- Bollinger Bands Breakout Strategy 442259Pine Script · Breakout · 1h