Weekend Volatility Trading Strategy
This strategy sets long and short entry conditions based on Friday's closing price, and goes long or short after Saturday's and Sunday's opening, exiting all positions before Monday's opening. The strategy aims to…
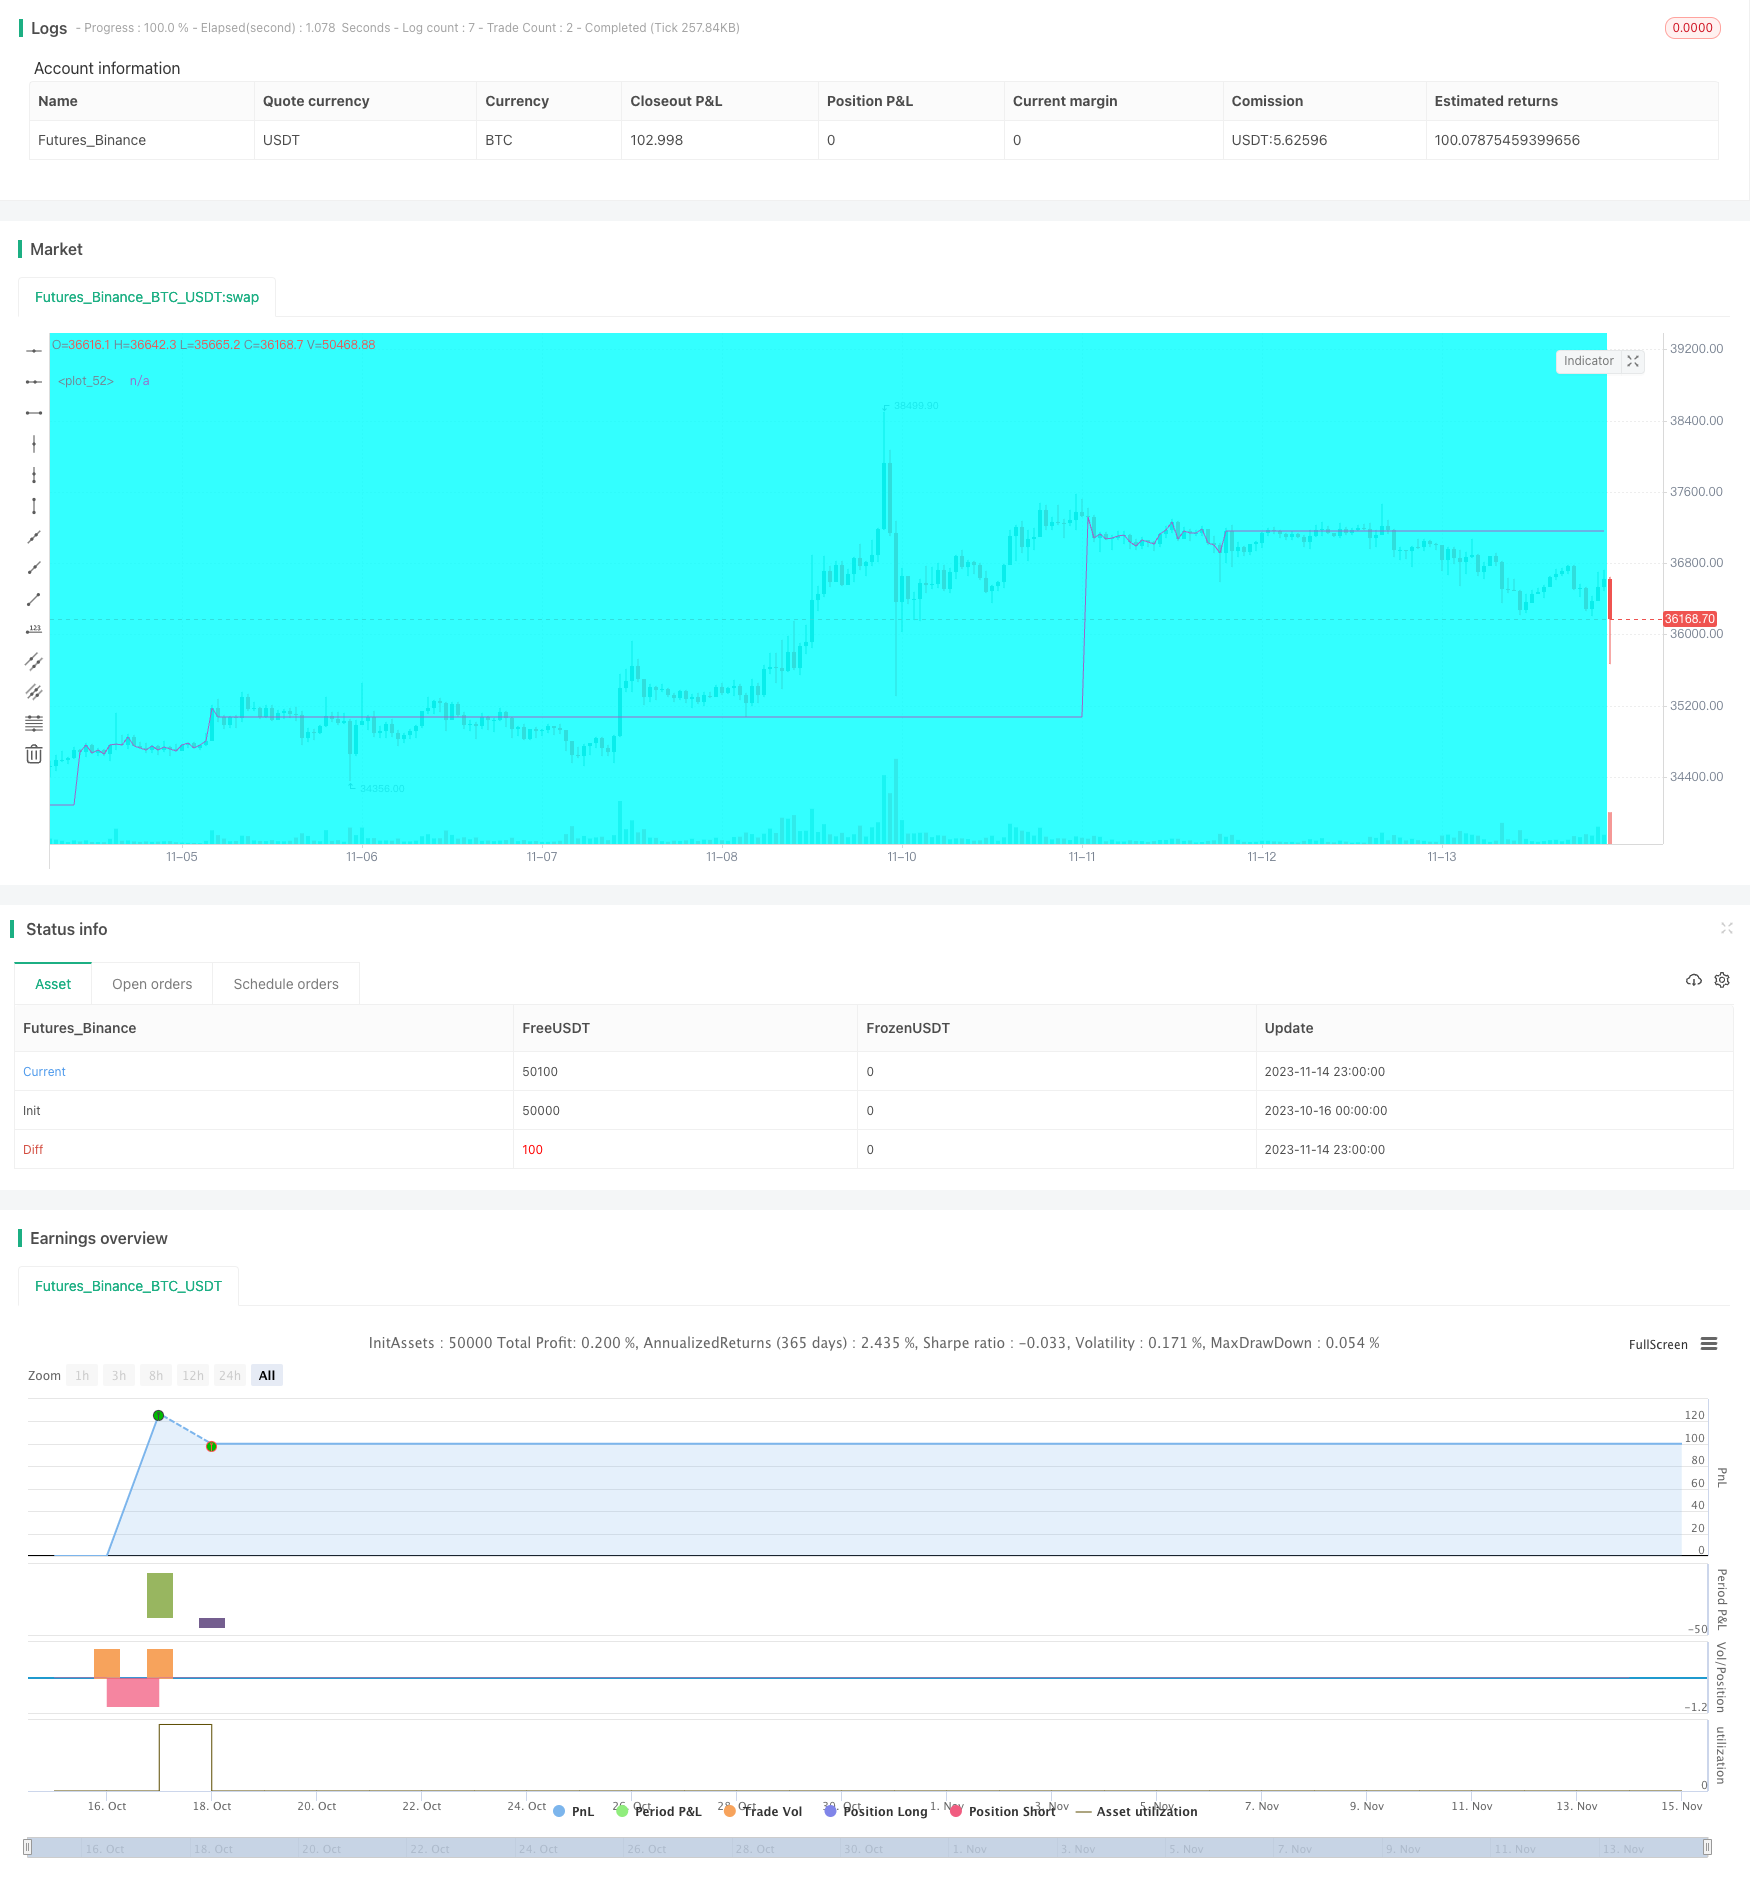
Overview
This strategy sets long and short entry conditions based on Friday's closing price, and goes long or short after Saturday's and Sunday's opening, exiting all positions before Monday's opening. The strategy aims to profit from price fluctuations around Friday's closing price over the weekend.
Principles
- Record Friday's closing price as the reference price
- On Saturday and Sunday's opening:
- If price is above 105% of Friday's close, go short
- If price is below 95% of Friday's close, go long
- Take profit is set at 3% of initial capital
- Close all positions before Monday's opening
Advantage Analysis
- Trade on weekend's low volume and volatility to reduce market risk
- Clear entry and exit rules simplify strategy execution
- Pursue steady small profits with short-term trades
- High capital turnover with short cycle
Risk Analysis
- Weekend price fluctuation may be smaller than expected, unable to open positions
- Excessive volatility may cause stop loss
- Significant events on Monday may cause price gaps, unable to stop loss in time
Risk Solutions:
- Adjust fluctuation range for entries
- Set proper stop loss points
- Close positions early, avoid holding over weekends
Optimization Guidelines
- Adjust entry thresholds based on different products' characteristics
- Optimize take profit rules based on backtest results
- Select leverage based on capital size
- Add indicator filters such as moving average to time entries
Summary
This short-term trading strategy has very clear logic and risk control measures. With proper parameter tuning and continuous testing and optimization, it can generate steady investment returns. At the same time, the risk of large weekend losses due to excessive volatility needs to be managed via proper risk control.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | Leverage |
| v_input_2 | 0.03 | Profit Taking Percent Threshold |
| v_input_3 | 2017 | Backtest Start Year |
| v_input_4 | 12 | Backtest Start Month |
| v_input_5 | 10 | Backtest Start Day |
| v_input_6 | 2025 | Backtest Stop Year |
| v_input_7 | 12 | Backtest Stop Month |
| v_input_8 | 30 | Backtest Stop Day |
| v_input_9 | true | Color Background? |
Source Pine Script
/*backtest
start: 2023-10-16 00:00:00
end: 2023-11-15 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3
//Copyright Boris Kozak
strategy("XBT Weekend Trade Strategy", overlay=true, default_qty_type=strategy.percent_of_equity,initial_capital=20000)
leverage = input(1,"Leverage")
profitTakingPercentThreshold = input(0.03,"Profit Taking Percent Threshold")

//****Code used for setting up backtesting.****///
testStartYear = input(2017, "Backtest Start Year")
testStartMonth = input(12, "Backtest Start Month")
testStartDay = input(10, "Backtest Start Day")
testPeriodStart = timestamp(testStartYear,testStartMonth,testStartDay,0,0)

testStopYear = input(2025, "Backtest Stop Year")
testStopMonth = input(12, "Backtest Stop Month")
testStopDay = input(30, "Backtest Stop Day")
testPeriodStop = timestamp(testStopYear,testStopMonth,testStopDay,0,0)

// A switch to control background coloring of the test period
testPeriodBackground = input(title="Color Background?", type=bool, defval=true)
testPeriodBackgroundColor = testPeriodBackground and (time >= testPeriodStart) and (time <= testPeriodStop) ? #00FFFF : na
bgcolor(testPeriodBackgroundColor, transp=50)

testPeriod() => true

//****END Code used for setting up backtesting.****///


//*** Main entry point is here***//
// Figure out how many days since the Friday close
days_since_friday = if dayofweek == 6
    0
else
    if dayofweek == 7
        1
    else
        if dayofweek == 1
            2
        else
            if dayofweek == 2
                3
            else
                if dayofweek == 3
                    4
                else
                    if dayofweek == 4
                        5
                    else
                        6

// Grab the Friday close price
fridaycloseprice = request.security(syminfo.tickerid,'D',close[days_since_friday])
plot(fridaycloseprice)
strategy.initial_capital = 50000
// Only perform backtesting during the window specified
if testPeriod()
    // If we've reached out profit threshold, exit all positions
    if ((strategy.openprofit/strategy.initial_capital) > profitTakingPercentThreshold)
        strategy.close_all()
    // Only execute this trade on saturday and sunday (UTC)
    if (dayofweek == 7.0 or dayofweek == 1.0)
        // Begin - Empty position (no active trades)
        if (strategy.position_size == 0)
            // If current close price > threshold, go short
            if ((close>fridaycloseprice*1.045))
                strategy.entry("Short Entry", strategy.short, leverage)
            else
                // If current close price < threshold, go long
                if (close<(fridaycloseprice*0.955))
                    strategy.entry("Long Entry",strategy.long, leverage)
        // Begin - we already have a position
        if (abs(strategy.position_size) > 0)
            // We are short
            if (strategy.position_size < 0)
                if ((close>strategy.position_avg_price*1.045))
                    // Add to the position
                    strategy.entry("Adding to Short Entry", strategy.short, leverage)
            else
                strategy.entry("Long Entry",strategy.long,leverage)
    // On Monday, if we have any open positions, close them
    if (dayofweek==2.0)
        strategy.close_all()
Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-16. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Weekend-Volatility-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Dual Bollinger Band Volatility Tracking StrategyPine Script · Volatility · 1d
- Dual EMA Volatility Adaptive Trading Strategy with Multi Tiered Profit Optimization SystemPine Script · Volatility · 1d
- Dual Moving Average Volatility Tracking StrategyPine Script · Volatility · 1h
- Dynamic ATR Trailing Stop Trading Strategy Market Volatility Adaptive SystemPine Script · Volatility · 1d
- Multi Indicator Dynamic Volatility Alert Trading SystemPine Script · Volatility · 1m
- Multi Indicator Volatility Trading RSI EMA ATR StrategyPine Script · Volatility · 3m