Strategy vault / Mean reversion
Williams Double Exponential Moving Average and Ichimoku Kinkou Hyo Strategy
This strategy combines the Williams Double Exponential Moving Average and Ichimoku Kinkou Hyo, two technical indicators, in order to utilize their respective advantages and improve the accuracy of trading decisions…
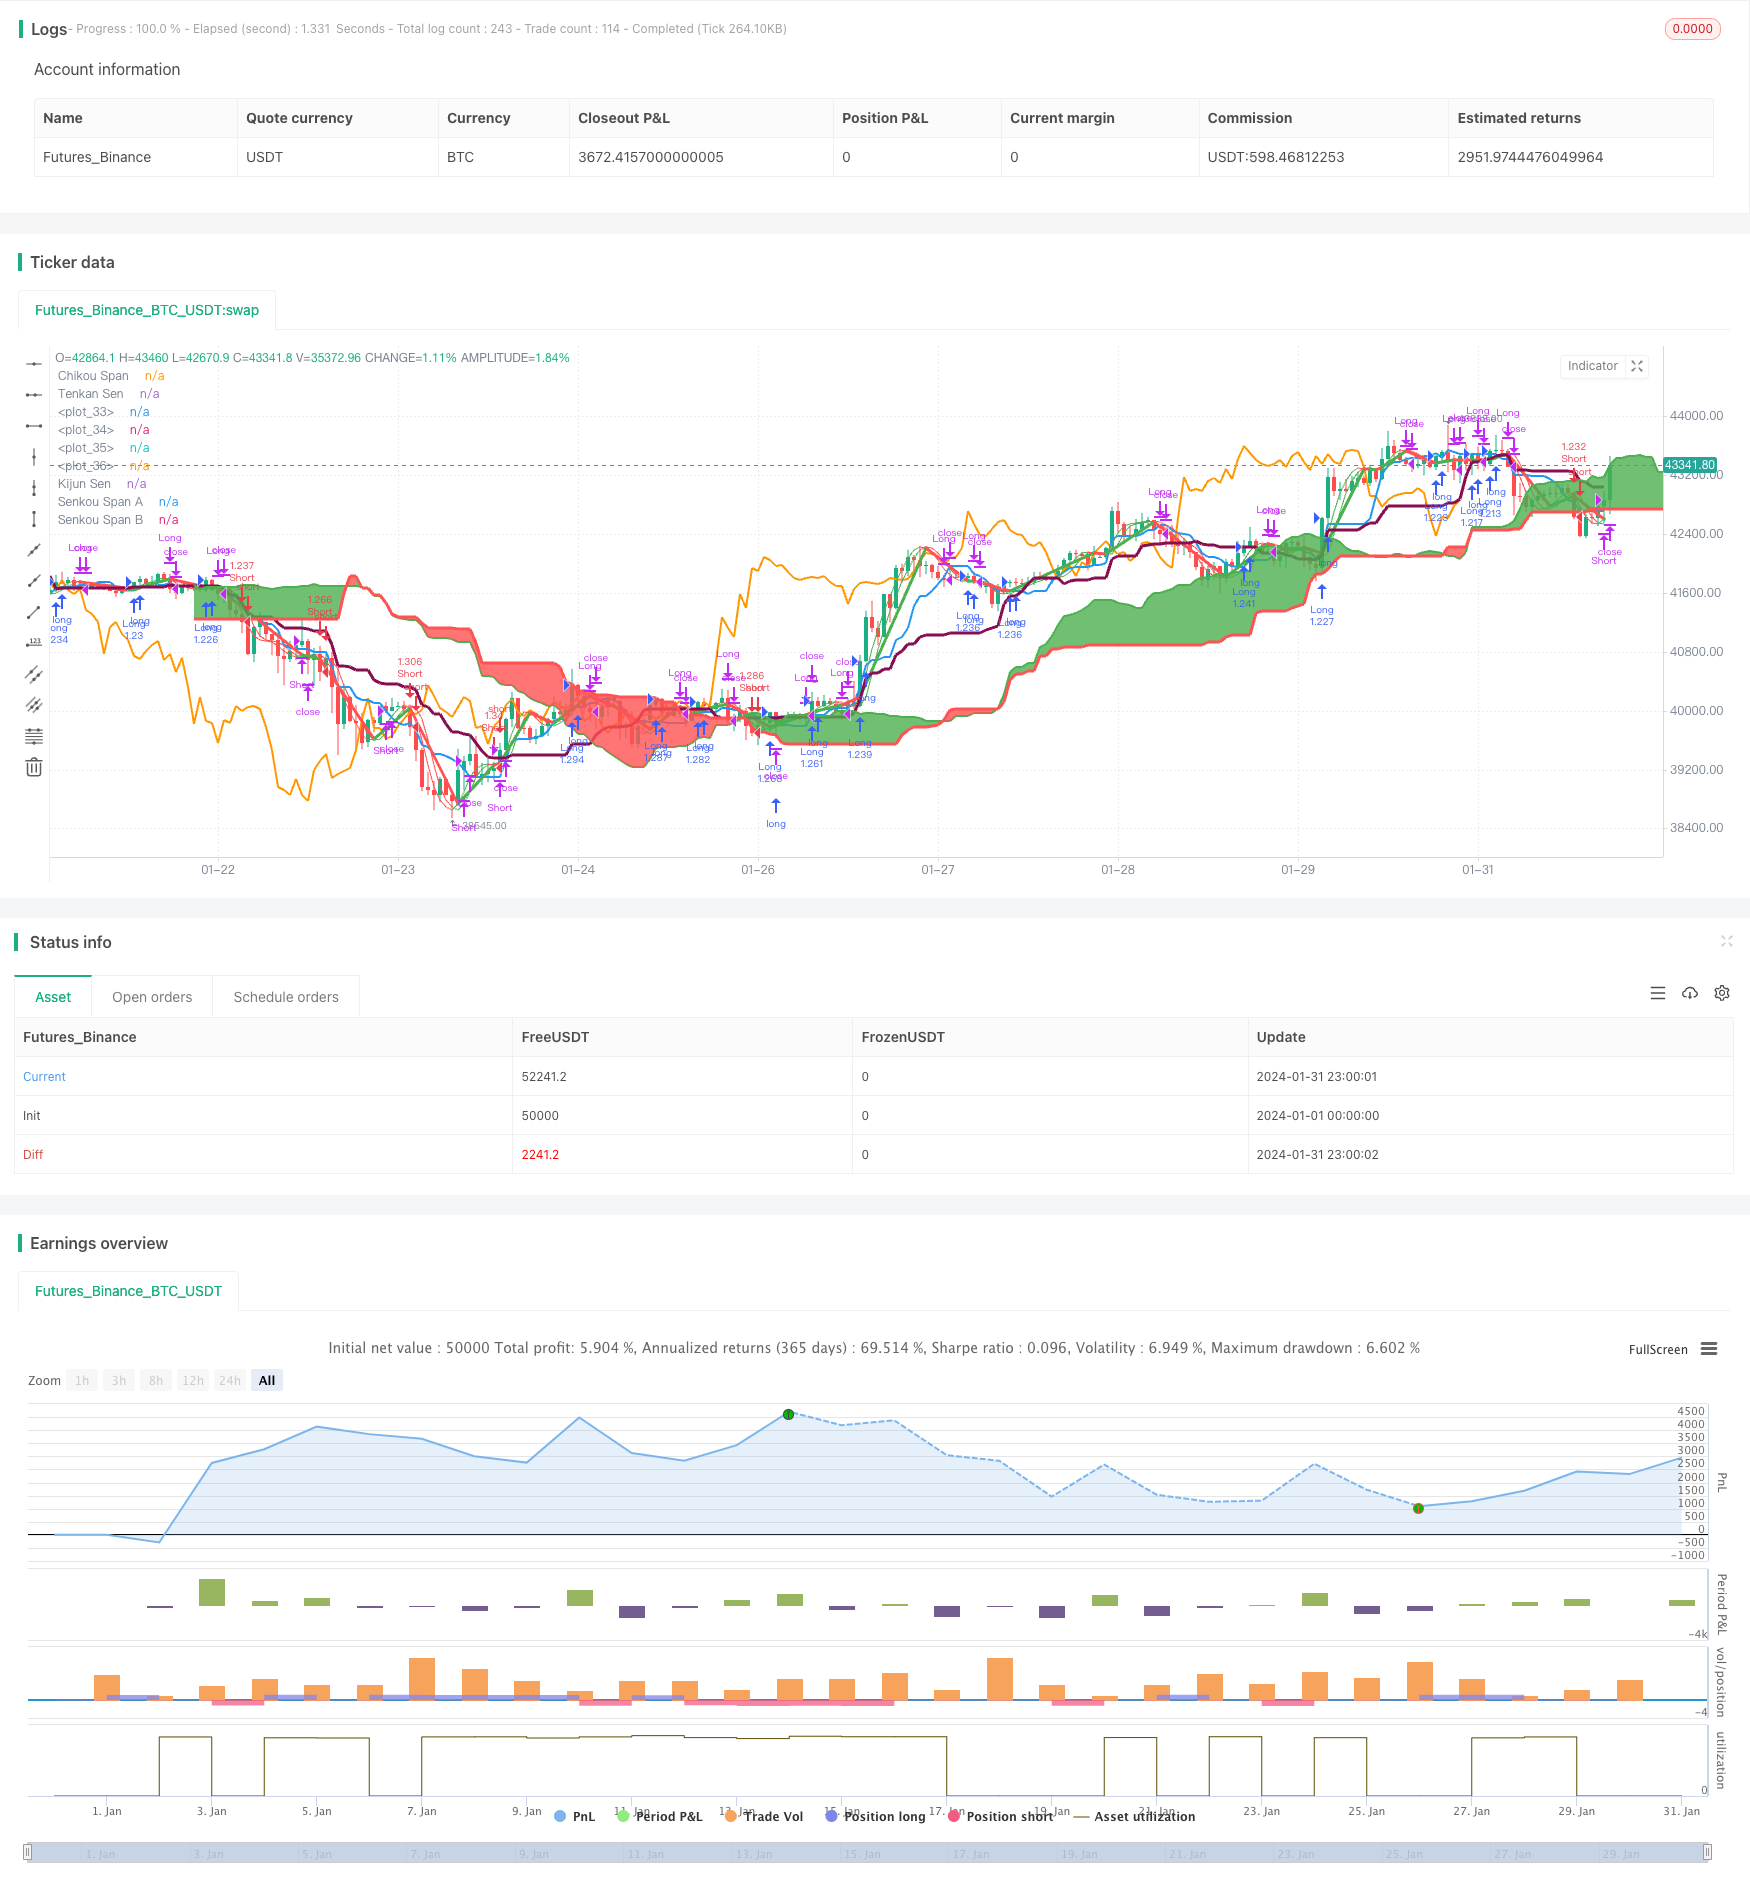
Overview
This strategy combines the Williams Double Exponential Moving Average and Ichimoku Kinkou Hyo, two technical indicators, in order to utilize their respective advantages and improve the accuracy of trading decisions. The Williams Double Exponential Moving Average can fully reflect trends in price changes, while Ichimoku Kinkou Hyo can provide early warnings of trend reversals.
Principles
The Williams Double Exponential Moving Average contains a fast line and a slow line. The fast line is calculated with the formula: 2*(n/2 period Weighted Moving Average), and the slow line is calculated with: n period Weighted Moving Average. When the fast line crosses above the slow line from below, it is a buy signal; when it crosses below from above, it is a sell signal.
Ichimoku Kinkou Hyo consists of four components: the tenkan sen, kijun sen, leading line and cloud layers. A golden cross between the tenkan sen and kijun sen is a buy signal, while a death cross is a sell signal. When prices break above or below the upper or lower edges of the cloud layers, it signals a buy or sell, respectively.
This strategy combines the strengths of both indicators. The first determinant is a signal from the Williams Indicator, and the second is confirmation from Ichimoku Kinkou Hyo, effectively filtering out false signals and improving decision accuracy.
Advantages
- The Williams Double Exponential Moving Average reacts sensitively and can determine a strong trend direction.
- Ichimoku Kinkou Hyo provides leading judgments and early warnings of trend reversals.
- Combining the two indicators allows them to validate each other and reduce false signals.
- Parameters can be optimized for adaption to different cycle lengths and products.
Risks and Optimization
- Frequent signals may occur in non-trending markets. Parameters can be adjusted to filter out some signals.
- There may be some lag in crossovers between the fast and slow lines. Cloud layers can be referenced to avoid missing optimal entry and exit points.
- It is recommended to combine with trend or volatility indicators to further avoid false signals.
Summary
This strategy fully utilizes the abilities of the Williams Indicator to judge trend directions and Ichimoku Kinkou Hyo to provide early warnings of reversals, significantly improving the accuracy of trading decisions. Further optimizations such as parameter tuning and combining with other indicators will allow sustainable enhancements for adapting to market changes.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 12 | Double HullMA |
| v_input_2 | 9 | Tenkan Sen Periods |
| v_input_3 | 24 | Kijun Sen Periods |
| v_input_4 | 51 | Senkou Span B Periods |
| v_input_5 | 24 | Displacement |
Source Pine Script
/*backtest
start: 2024-01-01 00:00:00
end: 2024-01-31 23:59:59
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3

strategy("Hull MA-X + Ichimoku Kinko Hyo", shorttitle="Hi", overlay=true, default_qty_type=strategy.percent_of_equity, max_bars_back=1000, default_qty_value=100, calc_on_order_fills= true, calc_on_every_tick=true, pyramiding=0)

keh=input(title="Double HullMA",defval=12, minval=1)
n2ma=2*wma(close,round(keh/2))
nma=wma(close,keh)
diff=n2ma-nma
sqn=round(sqrt(keh))
n2ma1=2*wma(close[1],round(keh/2))
nma1=wma(close[1],keh)
diff1=n2ma1-nma1
sqn1=round(sqrt(keh))
n1=wma(diff,sqn)
n2=wma(diff1,sqn)
b=n1>n2?lime:red
c=n1>n2?green:red
d=n1>n2?red:green

TenkanSenPeriods = input(9, minval=1, title="Tenkan Sen Periods")
KijunSenPeriods = input(24, minval=1, title="Kijun Sen Periods")
SenkouSpanBPeriods = input(51, minval=1, title="Senkou Span B Periods")
displacement = input(24, minval=1, title="Displacement")
donchian(len) => avg(lowest(len), highest(len))
TenkanSen = donchian(TenkanSenPeriods)
KijunSen = donchian(KijunSenPeriods)
SenkouSpanA = avg(TenkanSen, KijunSen)
SenkouSpanB = donchian(SenkouSpanBPeriods)
SenkouSpanH = max(SenkouSpanA[displacement - 1], SenkouSpanB[displacement - 1])
SenkouSpanL = min(SenkouSpanA[displacement - 1], SenkouSpanB[displacement - 1])
ChikouSpan = close[displacement-1]

Hullfast=plot(n1,color=c)
Hullslow=plot(n2,color=c)
plot(cross(n1, n2) ? n1:na, style = circles, color=b, linewidth = 4)
plot(cross(n1, n2) ? n1:na, style = line, color=d, linewidth = 3)
plot(TenkanSen, color=blue, title="Tenkan Sen", linewidth = 2)
plot(KijunSen, color=maroon, title="Kijun Sen", linewidth = 3)
plot(close, offset = -displacement, color=orange, title="Chikou Span", linewidth = 2)
sa=plot (SenkouSpanA, offset = displacement, color=green,  title="Senkou Span A", linewidth = 2)
sb=plot (SenkouSpanB, offset = displacement, color=red,  title="Senkou Span B", linewidth = 3)
fill(sa, sb, color = SenkouSpanA > SenkouSpanB ? green : red)

longCondition = n1>n2 and close>n2 and close>ChikouSpan and close>SenkouSpanH and (TenkanSen>KijunSen or close>KijunSen)
if (longCondition)
    strategy.entry("Long",strategy.long)

shortCondition = n1<n2 and close<n2 and close<ChikouSpan and close<SenkouSpanL and (TenkanSen<KijunSen or close<KijunSen)
if (shortCondition)
    strategy.entry("Short",strategy.short)

closelong = n1<n2 and close<n2 and (TenkanSen<KijunSen or close<TenkanSen or close<KijunSen or close<SenkouSpanL)
if (closelong)
    strategy.close("Long")

closeshort = n1>n2 and close>n2 and (TenkanSen>KijunSen or close>TenkanSen or close>KijunSen or close>SenkouSpanH)
if (closeshort)
strategy.close("Short")Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-18. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Williams-Double-Exponential-Moving-Average-and-Ichimoku-Kinkou-Hyo-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Random Oscillation StrategyPine Script · Mean reversion · 1d
- RSI Daredevil Squadron Fusion StrategyPine Script · Mean reversion · 3h
- Ichimoku Cloud Quant StrategyPine Script · Mean reversion · 1d
- Ichimoku Kinko Hyo Mean Reversion StrategyPine Script · Mean reversion · 1d
- Advanced Quantitative Trend Following and Cloud Reversal Composite Trading StrategyPine Script · Mean reversion · 1d
- Bidirectional Moving Average Reversion Trading StrategyPine Script · Mean reversion · 1h