Zero Lag Trend Momentum Indicator Trading Strategy
This strategy is a quantitative trading system based on zero-lag moving averages and trend strength scoring. It eliminates the lag of traditional moving averages, combining volatility channels and trend strength…
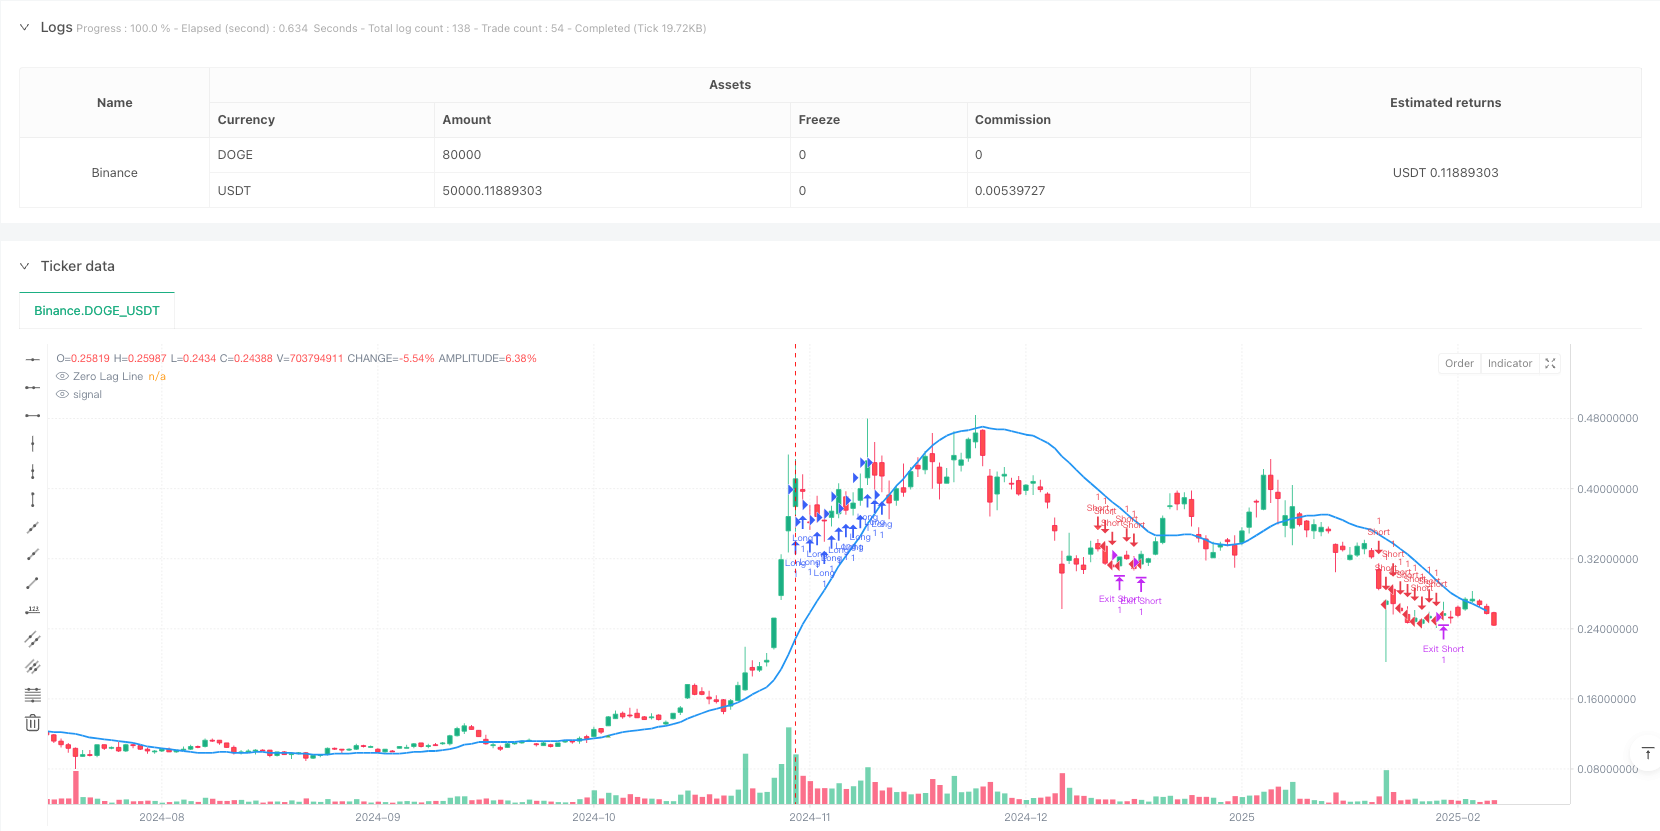
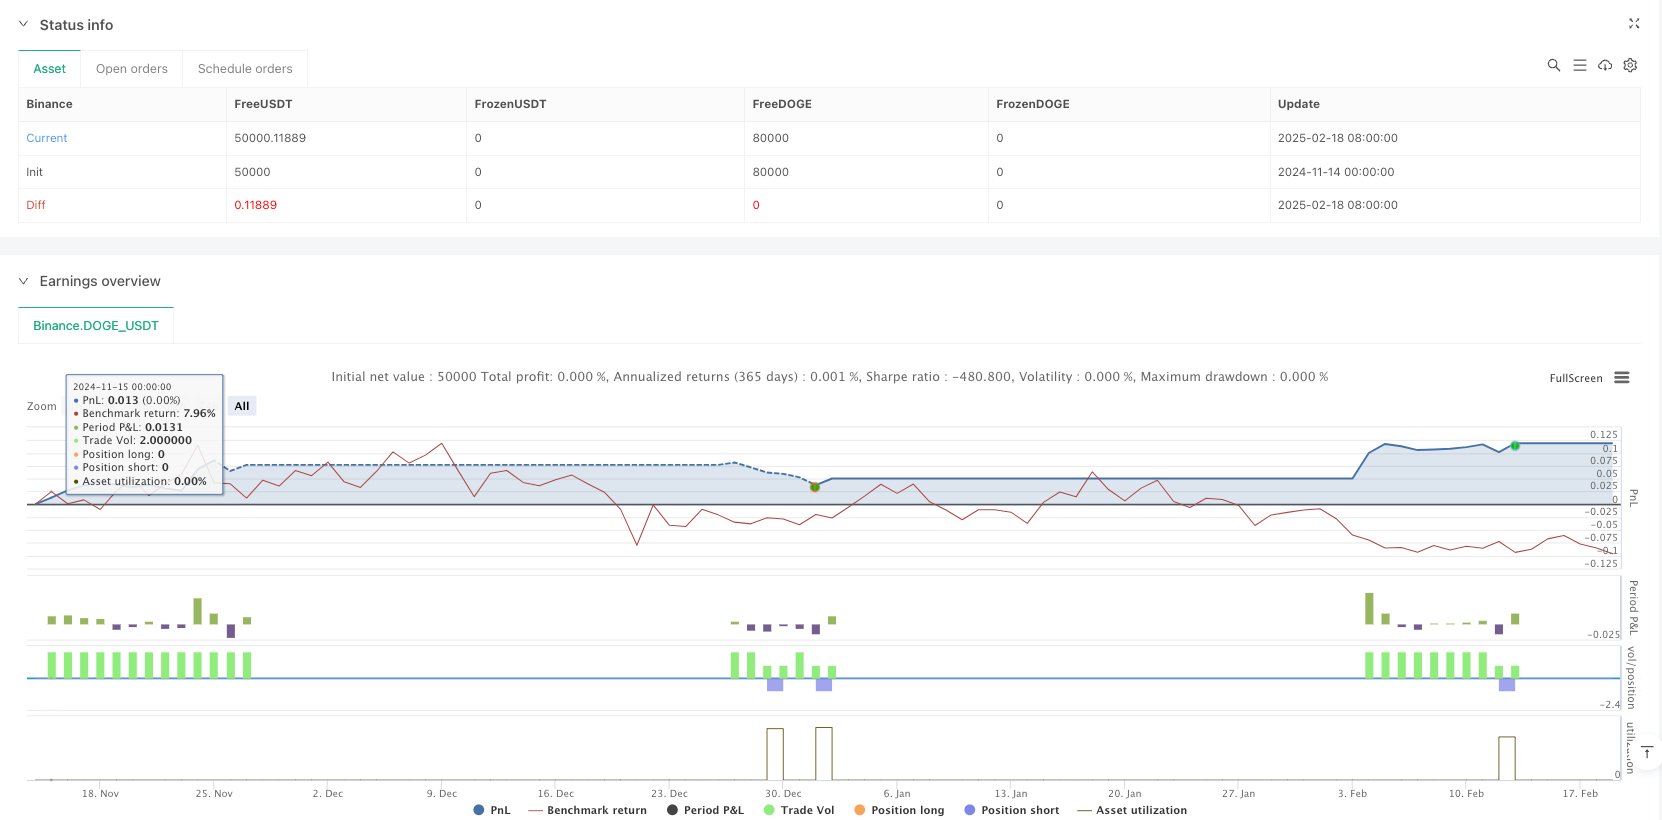
Overview
This strategy is a quantitative trading system based on zero-lag moving averages and trend strength scoring. It eliminates the lag of traditional moving averages, combining volatility channels and trend strength scoring to identify market trends and capture medium to short-term price movements. The strategy employs bi-directional trading, going long in uptrends and short in downtrends, with built-in stop-loss and take-profit mechanisms for risk control.
Strategy Principles
The core of the strategy lies in eliminating the lag effect of traditional moving averages through zero-lag calculation. This is achieved by first calculating the difference between current and lagged prices, adding this difference to the current price, and then applying moving average calculations to the result. The strategy also incorporates a trend strength scoring system that quantifies trend strength by comparing price levels across different timeframes. Additionally, it implements an ATR-based dynamic volatility channel to filter trading signals. Trade signals are only triggered when price breaks through the channel and trend score reaches the threshold.
Strategy Advantages
- Zero-lag characteristics enable faster capture of market trend changes, reducing losses associated with traditional moving average strategies.
- The trend strength scoring system provides quantitative measurement of market trends, helping filter false signals.
- Dynamic volatility channels adapt to market volatility, improving strategy stability.
- Bi-directional trading approach captures profit opportunities in both directions.
- Comprehensive stop-loss and take-profit mechanisms effectively control risk.
Strategy Risks
- May generate frequent false breakout signals in ranging markets, leading to overtrading.
- Complex parameter settings in the trend strength scoring system may require frequent adjustments under different market conditions.
- Zero-lag calculations may produce unstable results under extreme market conditions.
- Strategy relies on historical data for trend strength calculation, which may fail during severe market volatility.
Strategy Optimization Directions
- Introduce adaptive adjustment mechanism for volatility indicators (like ATR) to dynamically adjust trend strength score thresholds.
- Add volume analysis indicators to verify trend validity.
- Develop market state recognition module to use different parameter settings under different market conditions.
- Implement time filters to avoid trading during highly volatile market periods.
- Optimize stop-loss and take-profit mechanisms by dynamically adjusting ratios based on market volatility.
Summary
This strategy effectively addresses the lag issues in traditional trend-following strategies through innovative zero-lag calculation methods and trend strength scoring system. By incorporating dynamic volatility channels and comprehensive risk control mechanisms, it enhances strategy stability and reliability. While there is room for improvement in parameter optimization and market adaptability, the overall design is clear and shows good practical application value. Traders are advised to adjust parameters according to specific market characteristics and trading instruments when implementing the strategy in live trading.
Source Pine Script
/*backtest
start: 2024-11-14 00:00:00
end: 2025-02-19 08:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Binance","currency":"DOGE_USDT"}]
*/

// This Pine Script™ code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © josephdelvecchio

//@version=6
strategy("Zero Lag Trend Strategy", overlay=true)

// -- Input Parameters --
timeframe = input.timeframe("10", "Timeframe")
zeroLagMovAvg = input.string("ema", "Zero Lag Moving Average", options=["ema", "sma"])
length = input.int(50, "Lookback Period")
volatility_mult = input.float(1.5, "Volatility Multiplier")
loop_start = input.int(1, "Loop Start")
loop_end = input.int(50, "Loop End")
threshold_up = input.int(5, "Threshold Up")
threshold_down = input.int(-5, "Threshold Down")
signalpct = input.float(8, "Signal Percentage")
stoppct = input.float(0, "Stop Percentage")

// -- Helper Variables --
nATR = ta.atr(length)
lag = math.floor((length - 1) / 2)
zl_basis = zeroLagMovAvg == "ema" ? ta.ema(2 * close - close[lag], length) : ta.sma(2 * close - close[lag], length)
volatility = ta.highest(nATR, length * 3) * volatility_mult

// -- Trend Strength Scoring Function --
forloop_analysis(basis_price, loop_start, loop_end) =>
    int sum = 0 // Use 'sum' as you did originally, for the +/- logic
    for i = loop_start to loop_end
        if basis_price > basis_price[i]
            sum += 1
        else if basis_price < basis_price[i] // Explicitly check for less than
            sum -= 1
        // If they are equal, do nothing (sum remains unchanged)
    sum

score = forloop_analysis(zl_basis, loop_start, loop_end)

// -- Signal Generation --
long_signal = score > threshold_up and close > zl_basis + volatility
short_signal = score < threshold_down and close < zl_basis - volatility

// -- Trend Detection (Ensure One Trade Until Reversal) --
var int trend = na
trend := long_signal ? 1 : short_signal ? -1 : trend[1]
trend_changed = trend != trend[1]

// -- Stop-Loss & Take-Profit --
stop_loss = close * (1 - stoppct / 100)
take_profit = close * (1 + signalpct / 100)

// -- Strategy Orders (Enter Only When Trend Changes) --

if long_signal
    strategy.entry("Long", strategy.long)
else if short_signal
    strategy.entry("Short", strategy.short)

// -- Strategy Exits --
strategy.exit("Exit Long", from_entry="Long", stop=stop_loss, limit=take_profit)
strategy.exit("Exit Short", from_entry="Short", stop=take_profit, limit=stop_loss)

// -- Visualization --
p_basis = zl_basis
plot(p_basis, title="Zero Lag Line", color=color.blue, linewidth=2)

// -- Buy/Sell Arrows --
plotshape(series=trend_changed and trend == 1, location=location.belowbar, color=color.green, style=shape.triangleup, size=size.large, title="Buy Signal")
plotshape(series=trend_changed and trend == -1, location=location.abovebar, color=color.red, style=shape.triangledown, size=size.large, title="Sell Signal")
Published by ianzeng123 on the FMZ strategy square · last modified 2025-02-21. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Zero-Lag-Trend-Momentum-Indicator-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- KST EMA Momentum Trend Following StrategyPine Script · Momentum · 1d
- Momentum Strategy Based on DEMA and EMA Crossover with ATR Volatility FilterPine Script · Momentum · 1h
- Momentum Trend Optimization Combination StrategyPine Script · Momentum · 1h
- Moving Average Candle Regression StrategyPine Script · Momentum · 15m
- Multi EMA Trend Momentum Trading Strategy with Risk Management SystemPine Script · Momentum · 1h
- Multi Indicator Trend Momentum Trading Strategy with Dynamic Risk Management SystemPine Script · Momentum · 1h