Strategy vault / Mean reversion
123 Reversal and STARC Bands Combo Strategy
This strategy generates more accurate trading signals by combining the 123 Reversal strategy and the STARC Bands strategy. The 123 Reversal strategy judges bottom rebound opportunities through K-line reversal…
Overview
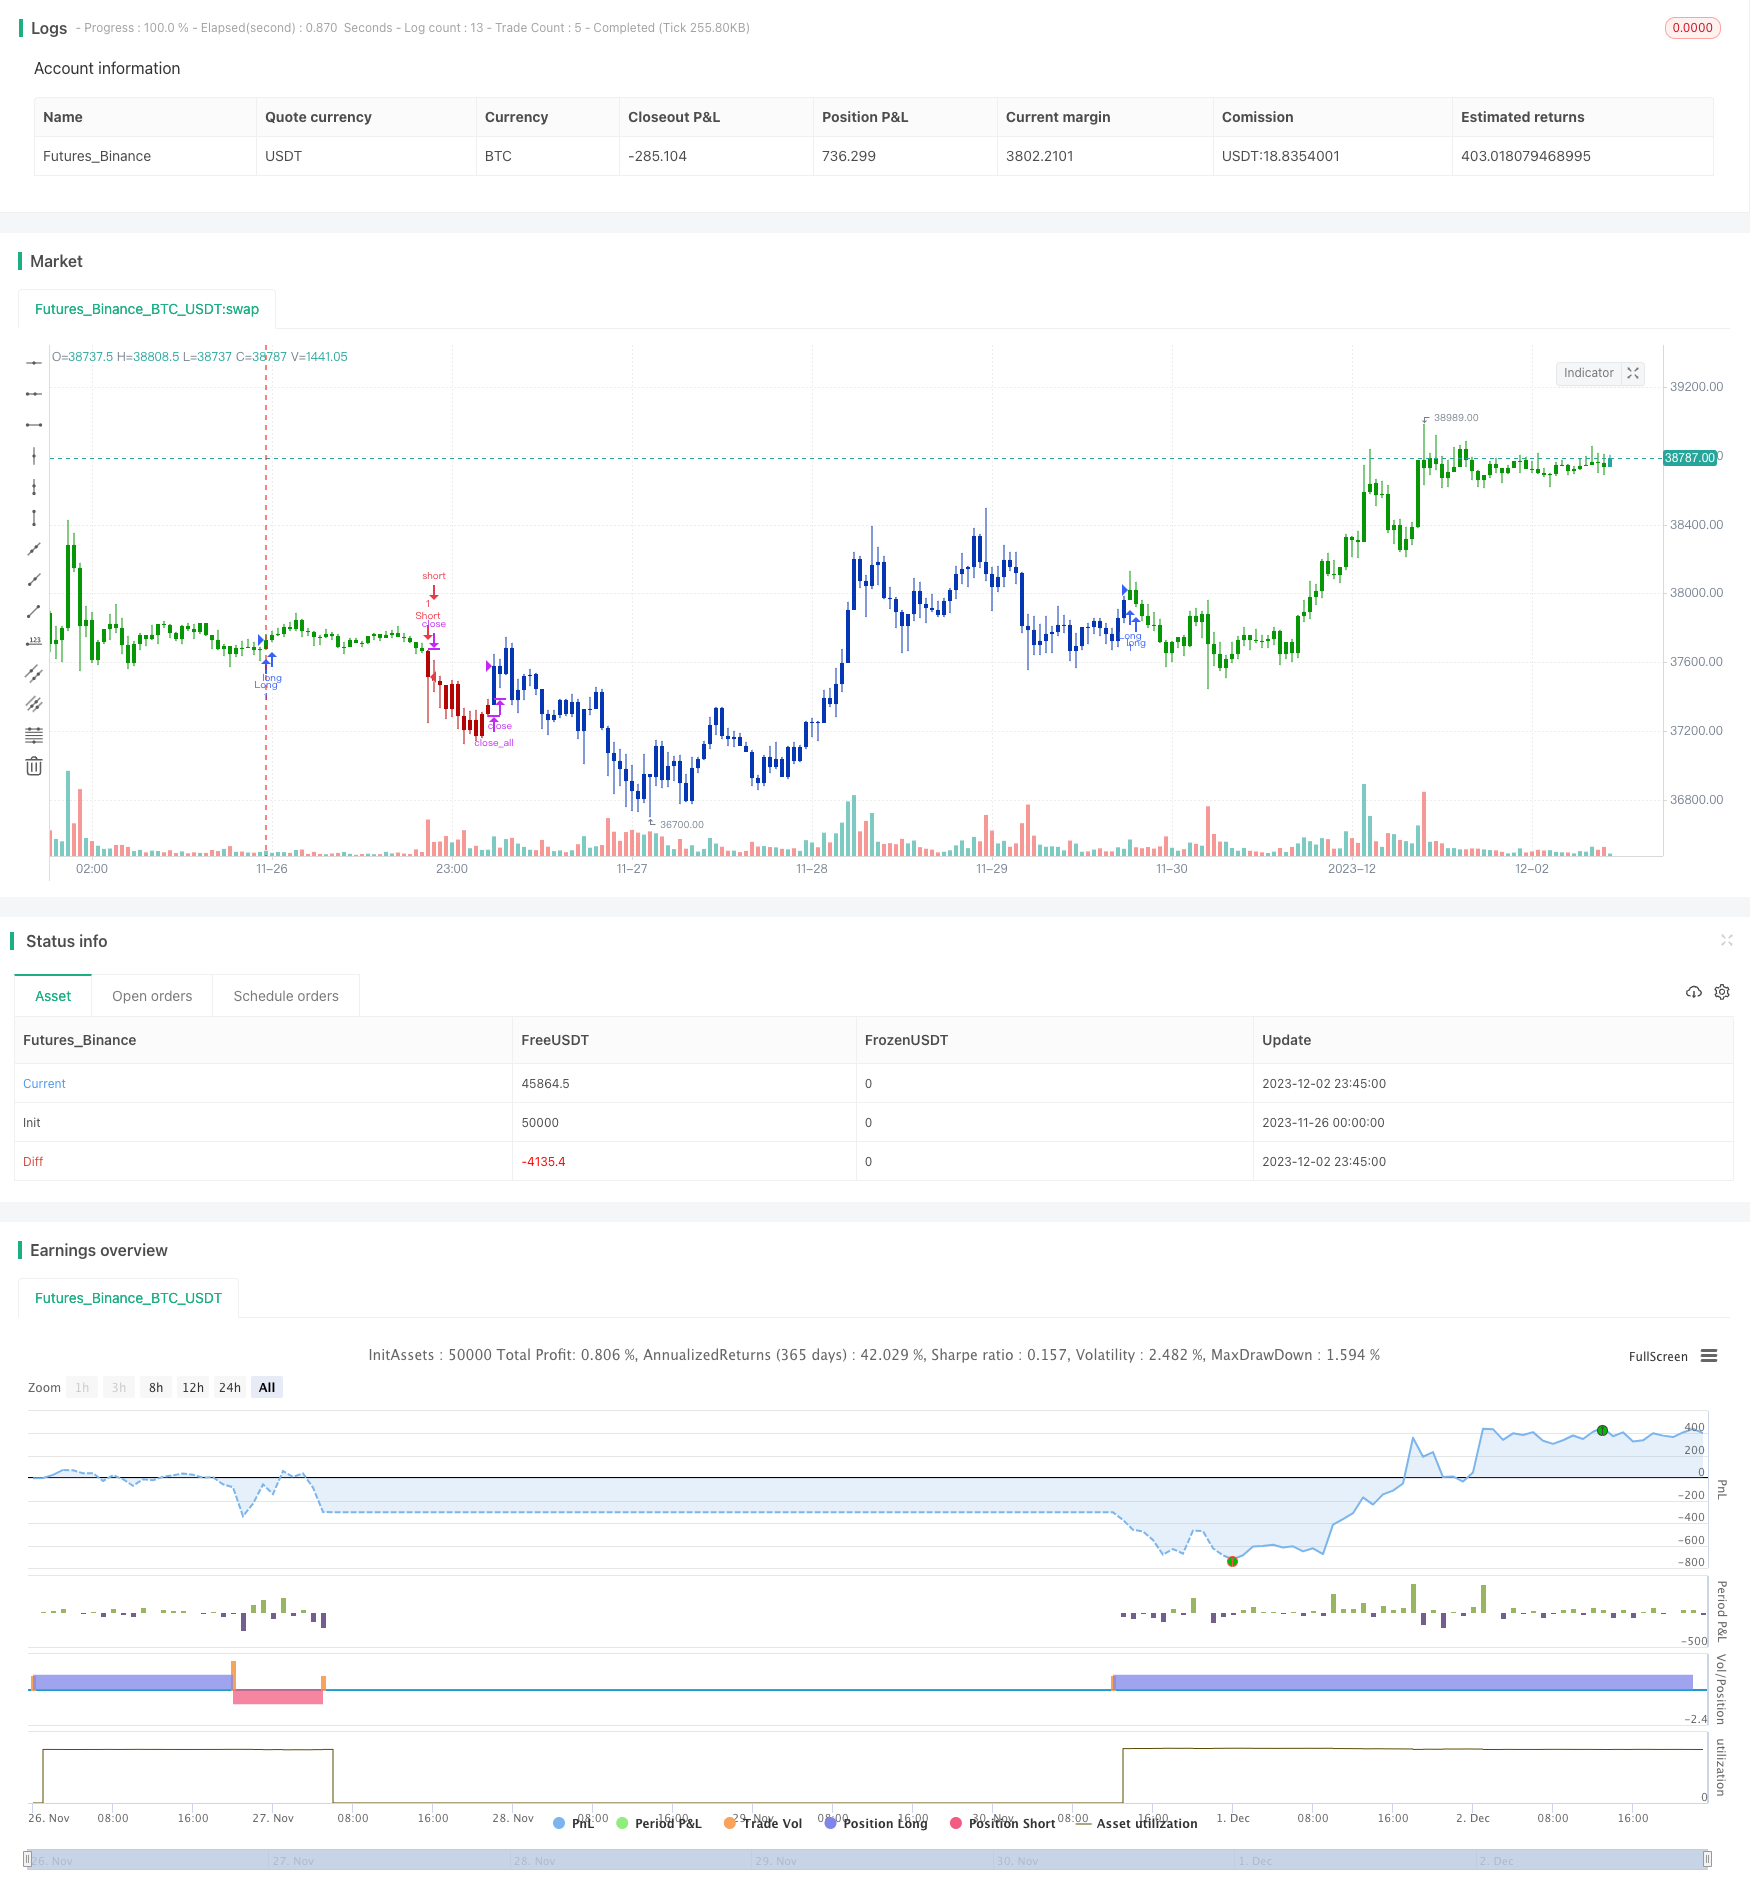
This strategy generates more accurate trading signals by combining the 123 Reversal strategy and the STARC Bands strategy. The 123 Reversal strategy judges bottom rebound opportunities through K-line reversal patterns. The STARC Bands strategy uses price breakouts of bands to determine trend direction. Using both strategies can make trading signals more reliable while utilizing the advantages of each strategy.
Strategy Logic
123 Reversal Strategy
This strategy originated from page 183 of the book "How I Tripled My Money in The Futures Market" by Ulf Jensen. The trading idea is to take long positions when prices show downward reversals as opportunities for bottom rebounds, and take short positions when prices show upward reversals as opportunities for trend reversals. The specific rules are:
Long signal: When the closing price is higher than the previous day's closing price for two consecutive days, and the 9-day moving average of slow K-line is below 50, go long.
Short signal: When the closing price is lower than the previous day's closing price for two consecutive days, and the 9-day moving average of fast K-line is above 50, go short.
STARC Bands Strategy
This strategy judges trend direction by plotting bands around a short-term simple moving average of the price. The upper band is constructed by adding average true range (ATR) above the moving average. The lower band is constructed by subtracting ATR from the moving average. Breaking above the upper band indicates an uptrend, while breaking below the lower band indicates a downtrend.
STARC stands for Stoller Average Range Channels. The indicator is named after its creator, Manning Stoller.
Advantage Analysis
Using both 123 Reversal and STARC Bands strategies improves the accuracy of trading signals. The 123 Reversal strategy captures reversal opportunities. The STARC Bands strategy judges trend direction. The two strategies complement each other to reduce false signals and improve win rate.
In addition, the 123 Reversal strategy helps avoid chasing new highs or lows after market breakouts. The STARC Bands strategy utilizes adaptive ATR bands to accommodate market changes.
Risk Analysis
The biggest risk of this strategy is the inability to completely avoid losing trades and consecutive losses. Although combining the two strategies can reduce false signals, incorrect judgments may still occur under certain market conditions. Timely stop losses should be used then to control losses.
Another risk lies in improper parameter settings that may lead to poor strategy performance. Parameters need to be tested and optimized according to different products and timeframes to fit their characteristics.
Optimization Directions
There is room for further optimization of this strategy:
Add stop loss strategies, such as price stops or indicator stops to avoid large losing trades;
Add entry conditions like price confirmation to avoid unfavorable entry prices;
Conduct parameter optimization to find the most suitable parameter combinations for the product and timeframe;
Add dynamic exit ideas to adjust positions based on market changes.
Summary
This strategy combines the 123 Reversal and STARC Bands strategies, utilizing both strategies' advantages in judging trend reversals and direction. It can effectively reduce false signals and improve trading efficiency. It also optimizes problems existing in using either strategy alone. Through continuous optimization, this strategy can become a stable and reliable quantitative trading strategy.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | ---- 123 Reversal ---- |
| v_input_2 | 14 | Length |
| v_input_3 | true | KSmoothing |
| v_input_4 | 3 | DLength |
| v_input_5 | 50 | Level |
| v_input_6 | true | ---- STARC Bands ---- |
| v_input_7 | 5 | LengthMA |
| v_input_8 | 15 | LengthATR |
| v_input_9 | 1.33 | K |
| v_input_10 | false | Trade reverse |
Source Pine Script
/*backtest
start: 2023-11-26 00:00:00
end: 2023-12-03 00:00:00
period: 45m
basePeriod: 5m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
////////////////////////////////////////////////////////////
//  Copyright by HPotter v1.0 28/07/2021
// This is combo strategies for get a cumulative signal.
//
// First strategy
// This System was created from the Book "How I Tripled My Money In The
// Futures Market" by Ulf Jensen, Page 183. This is reverse type of strategies.
// The strategy buys at market, if close price is higher than the previous close
// during 2 days and the meaning of 9-days Stochastic Slow Oscillator is lower than 50.
// The strategy sells at market, if close price is lower than the previous close price
// during 2 days and the meaning of 9-days Stochastic Fast Oscillator is higher than 50.
//
// Second strategy
// A type of technical indicator that is created by plotting two bands around
// a short-term simple moving average (SMA) of an underlying asset's price.
// The upper band is created by adding a value of the average true range
// (ATR) - a popular indicator used by technical traders - to the moving average.
// The lower band is created by subtracting a value of the ATR from the SMA.
// STARC is an acronym for Stoller Average Range Channels. The indicator is
// named after its creator, Manning Stoller.
//
// WARNING:
// - For purpose educate only
// - This script to change bars colors.
////////////////////////////////////////////////////////////
Reversal123(Length, KSmoothing, DLength, Level) =>
    vFast = sma(stoch(close, high, low, Length), KSmoothing)
    vSlow = sma(vFast, DLength)
    pos = 0.0
    pos := iff(close[2] < close[1] and close > close[1] and vFast < vSlow and vFast > Level, 1,
	         iff(close[2] > close[1] and close < close[1] and vFast > vSlow and vFast < Level, -1, nz(pos[1], 0)))
	pos


STARC(LengthMA,LengthATR,K) =>
    pos = 0.0
    xMA = sma(close, LengthMA)
    xATR = atr(LengthATR)
    xSTARCBandUp = xMA + xATR * K
    xSTARCBandDn = xMA - xATR * K
    pos := iff(close > xSTARCBandUp, 1,
             iff(close < xSTARCBandDn, -1, nz(pos[1], 0)))
    pos

strategy(title="Combo Backtest 123 Reversal & STARC Bands", shorttitle="Combo", overlay = true)
line1 = input(true, "---- 123 Reversal ----")
Length = input(14, minval=1)
KSmoothing = input(1, minval=1)
DLength = input(3, minval=1)
Level = input(50, minval=1)
//-------------------------
line2 = input(true, "---- STARC Bands ----")
LengthMA = input(5, minval=1)
LengthATR = input(15, minval=1)
K = input(1.33, minval=0.01, step = 0.01)
reverse = input(false, title="Trade reverse")
posReversal123 = Reversal123(Length, KSmoothing, DLength, Level)
posSTARC = STARC(LengthMA,LengthATR,K)
pos = iff(posReversal123 == 1 and posSTARC == 1 , 1,
	   iff(posReversal123 == -1 and posSTARC == -1, -1, 0))
possig = iff(reverse and pos == 1, -1,
          iff(reverse and pos == -1 , 1, pos))
if (possig == 1 )
    strategy.entry("Long", strategy.long)
if (possig == -1 )
    strategy.entry("Short", strategy.short)
if (possig == 0)
    strategy.close_all()
barcolor(possig == -1 ? #b50404: possig == 1 ? #079605 : #0536b3 )Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-04. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/123-Reversal-and-STARC-Bands-Combo-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive Trading Strategy Combining Dynamic Trend Reversal and Stochastic IndicatorPine Script · Mean reversion · 1d
- BuySell Strategy depends on AOStochRSIATRPine Script · Mean reversion · 30m
- Dual Momentum Trend Reversal Strategy Based on RSI and Stochastic RSIPine Script · Mean reversion · 1h
- Dynamic Adaptive Multi Timeframe Trend Following and Range Reversal Hybrid StrategyPine Script · Mean reversion · 2d
- Momentum Reversal Trading Strategy 428631Pine Script · Mean reversion · 2h
- Moving Average and Stochastic RSI Combination Trading StrategyPine Script · Mean reversion · 1d