Strategy vault / Trend following
Adaptive Bollinger Bands Trend Following Strategy with Multi Level Risk Management
This strategy is a trend-following system that combines Bollinger Bands and EMA indicators with a multi-layer risk control mechanism to optimize trading performance. The core strategy utilizes Bollinger Bands…
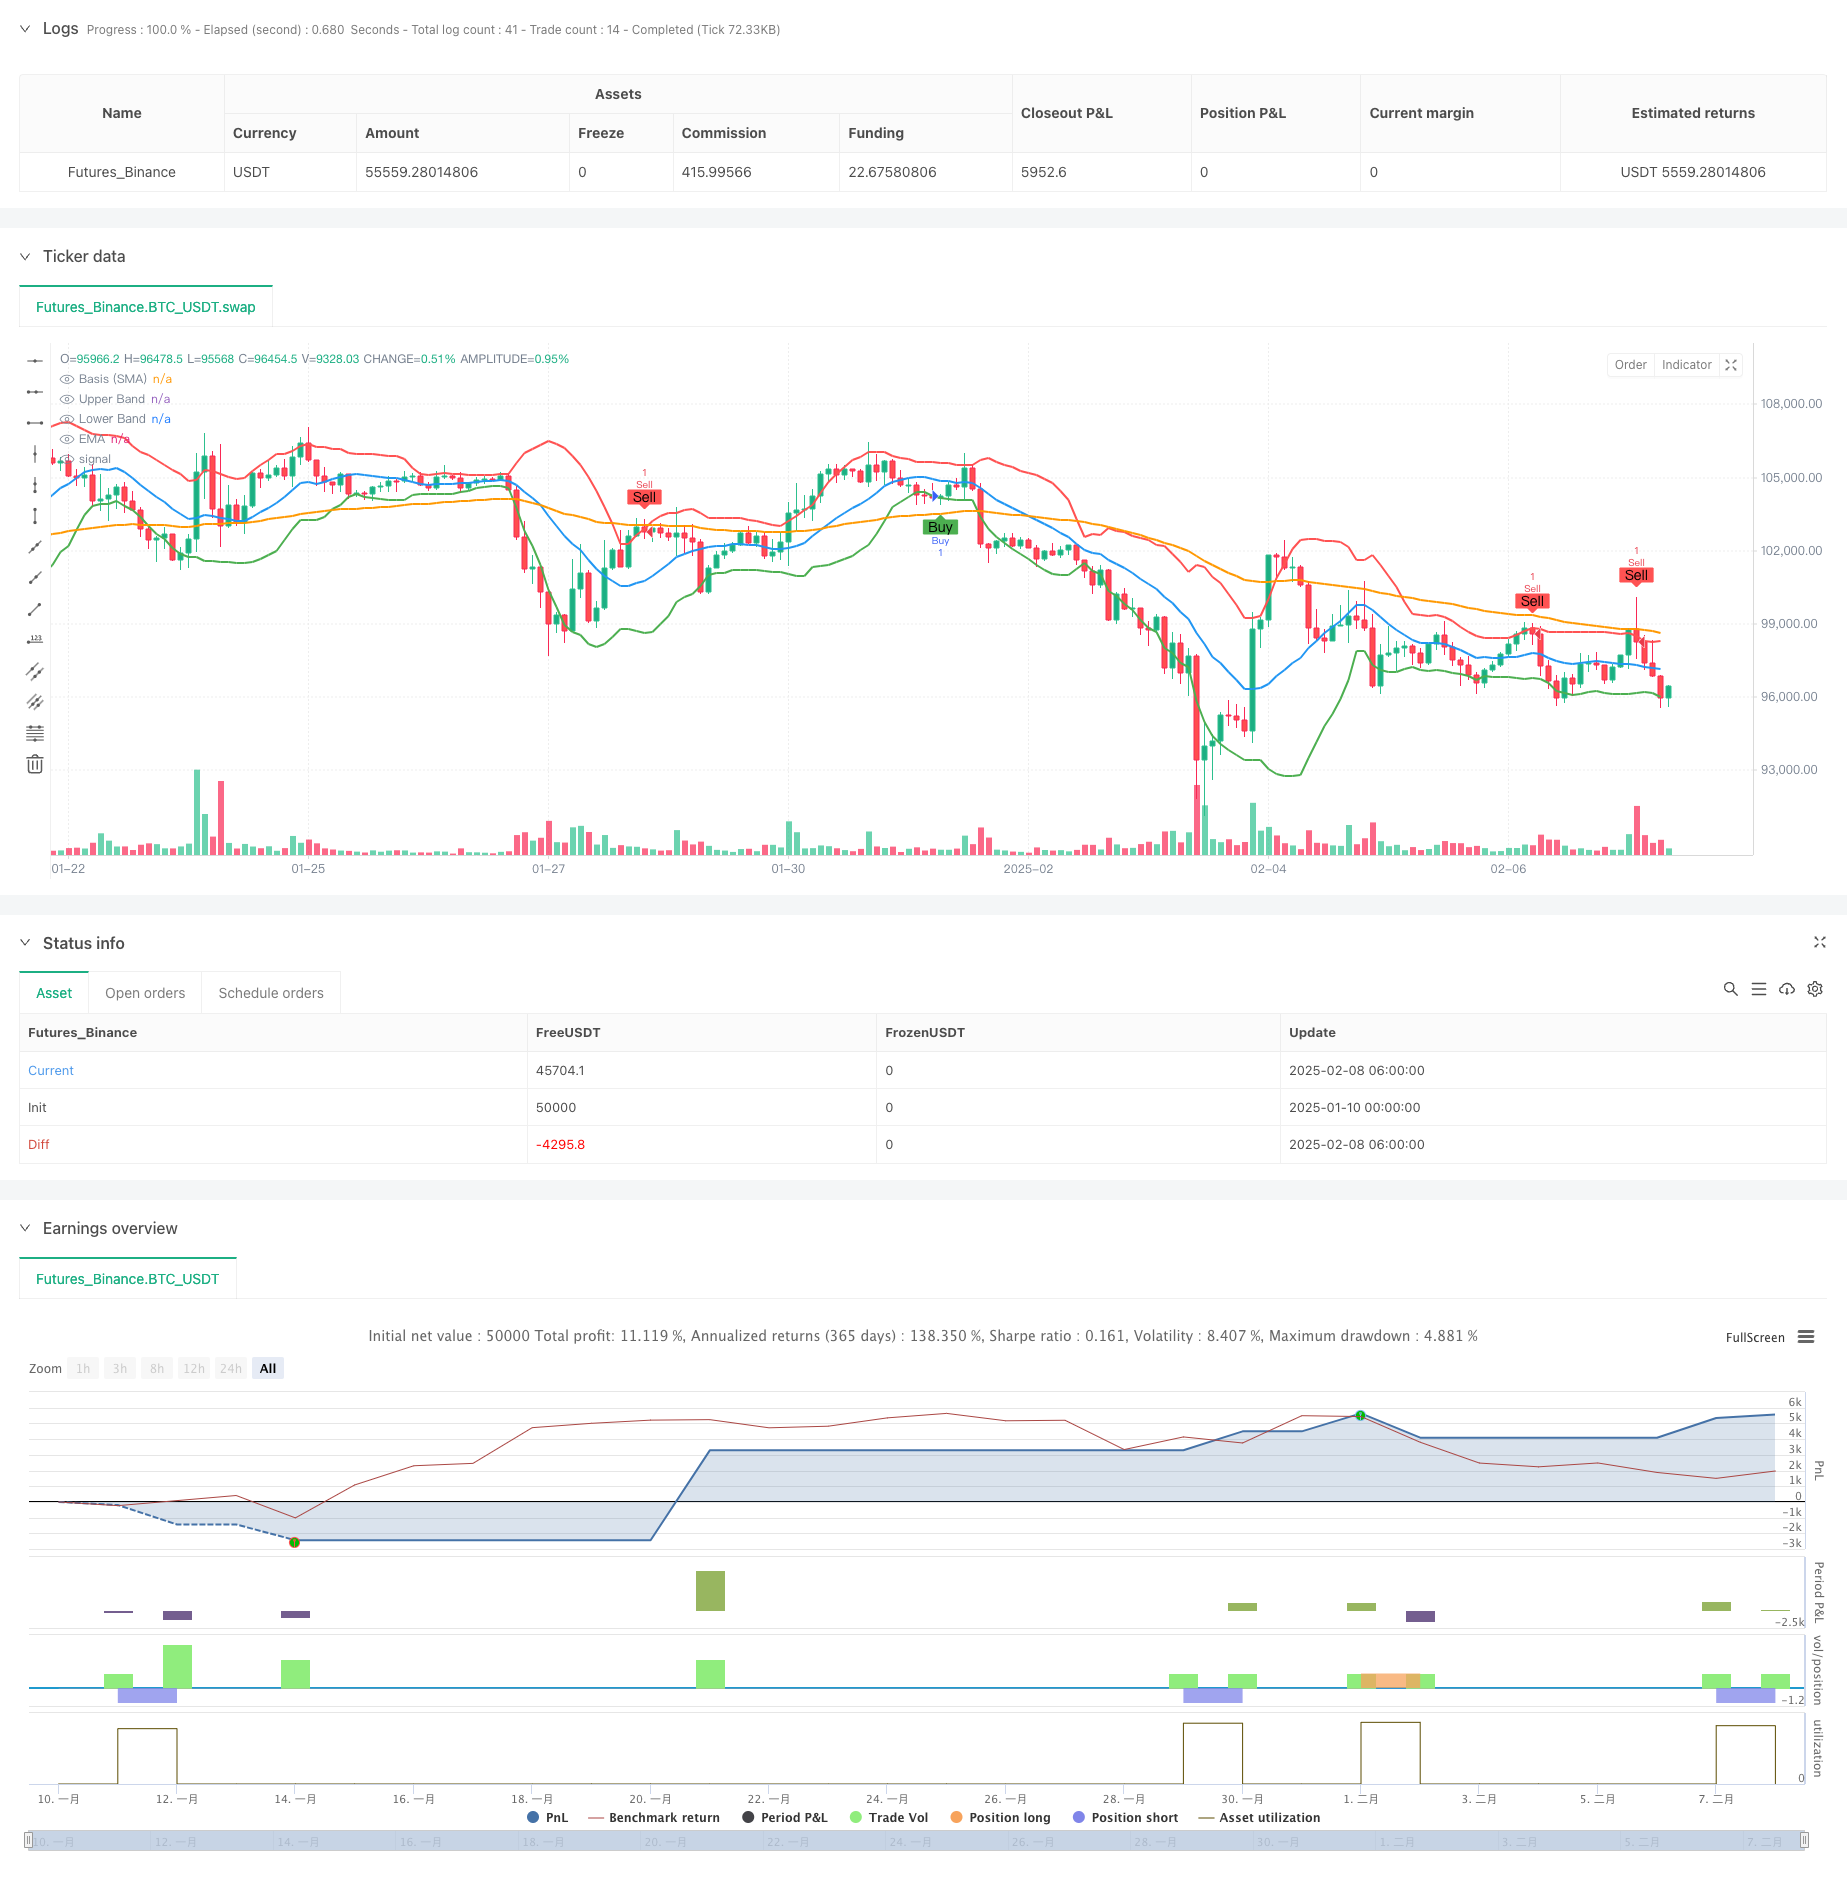
Overview
This strategy is a trend-following system that combines Bollinger Bands and EMA indicators with a multi-layer risk control mechanism to optimize trading performance. The core strategy utilizes Bollinger Bands breakout-reversion patterns to capture market trends while incorporating an EMA trend filter to enhance trading accuracy. The system includes a comprehensive risk management framework with trailing stops, fixed stop losses, profit targets, and time-based position closure.
Strategy Principles
The trading logic is based on the following core elements:
- Uses Bollinger Bands with 1.5 standard deviation and 14-period length as the primary trading signal indicator
- Triggers short signals when the previous candle closes above the upper band and current candle reverses
- Triggers long signals when the previous candle closes below the lower band and current candle turns bullish
- Optionally applies an 80-period EMA as a trend filter, only entering positions when trend direction aligns
- Activates trailing stops when price crosses the Bollinger Bands middle line
- Allows setting fixed stop loss and take profit amounts
- Supports automatic position closure based on bar count
Strategy Advantages
- Combines trend-following and reversal trading characteristics for stable performance across different market conditions
- Multi-layered risk control system provides comprehensive money management
- Flexible parameter settings allow strategy adaptation to different market conditions
- EMA filter effectively reduces false breakout risks
- Trailing stop mechanism effectively locks in profits
- Time-dimensional closure mechanism prevents long-term position trapping
Strategy Risks
- May generate frequent false breakout signals in ranging markets
- Fixed monetary stop losses may not suit all market conditions
- EMA filtering might cause missing important trading opportunities
- Trailing stops may close positions prematurely in highly volatile markets
- Parameter optimization may lead to overfitting historical data
Strategy Optimization Directions
- Introduce adaptive Bollinger Bands periods based on market volatility
- Develop dynamic stop-loss system based on money management
- Add volume analysis to confirm breakout validity
- Implement intelligent parameter optimization system
- Add market environment recognition module for different parameter settings in different market conditions
Summary
This is a well-designed trend-following system that provides reliable trading signals through the combination of Bollinger Bands and EMA, while ensuring trading safety through multi-layered risk control. The strategy offers strong configurability to adapt to different trading styles and market environments. While there are some inherent risks, the suggested optimization directions can further enhance the strategy's stability and profitability.
Source Pine Script
/*backtest
start: 2025-01-10 00:00:00
end: 2025-02-08 08:00:00
period: 2h
basePeriod: 2h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("AI Bollinger Bands Strategy with SL, TP, and Bars Till Close", overlay=true)

// Input parameters
bb_length           = input.int(14, title="Bollinger Bands Length", minval=1)
bb_stddev           = input.float(1.5, title="Bollinger Bands Standard Deviation", minval=0.1)
use_ema             = input.bool(true, title="Use EMA Filter")
ema_length          = input.int(80, title="EMA Length", minval=1)
use_trailing_stop   = input.bool(true, title="Use Trailing Stop")
use_sl              = input.bool(true, title="Use Stop Loss")
use_tp              = input.bool(false, title="Use Take Profit")
sl_dollars          = input.float(300.0, title="Stop Loss (\$)", minval=0.0)
tp_dollars          = input.float(1000.0, title="Take Profit (\$)", minval=0.0)
use_bars_till_close = input.bool(true, title="Use Bars Till Close")
bars_till_close     = input.int(10, title="Bars Till Close", minval=1)
// New input to toggle indicator plotting
plot_indicators     = input.bool(true, title="Plot Bollinger Bands and EMA on Chart")

// Calculate Bollinger Bands and EMA
basis      = ta.sma(close, bb_length)
upper_band = basis + bb_stddev * ta.stdev(close, bb_length)
lower_band = basis - bb_stddev * ta.stdev(close, bb_length)
ema        = ta.ema(close, ema_length)

// Plot Bollinger Bands and EMA conditionally
plot(plot_indicators  ? basis : na, color=color.blue, linewidth=2, title="Basis (SMA)")
plot(plot_indicators ? upper_band : na, color=color.red, linewidth=2, title="Upper Band")
plot(plot_indicators  ? lower_band : na, color=color.green, linewidth=2, title="Lower Band")
plot(plot_indicators   ? ema   : na, color=color.orange, linewidth=2, title="EMA")

// EMA conditions
ema_long_condition  = ema > ema[1]
ema_short_condition = ema < ema[1]

// Entry conditions
sell_condition = close[1] > upper_band[1] and close[1] > open[1] and close < open
if sell_condition and (not use_ema or ema_short_condition)
    strategy.entry("Sell", strategy.short)

buy_condition = close[1] < lower_band[1] and close > open
if buy_condition and (not use_ema or ema_long_condition)
    strategy.entry("Buy", strategy.long)

// Trailing stop logic
if use_trailing_stop
    if strategy.position_size > 0 and close >= basis
        strategy.exit("Trailing Stop Long", from_entry="Buy", stop=low)
    if strategy.position_size < 0 and close <= basis
        strategy.exit("Trailing Stop Short", from_entry="Sell", stop=high)

// Stop Loss and Take Profit logic
if use_sl or use_tp
    if strategy.position_size > 0
        long_entry = strategy.position_avg_price
        long_sl    = long_entry - sl_dollars
        long_tp    = long_entry + tp_dollars
        if use_sl and close <= long_sl
            strategy.close("Buy", comment="Long SL Hit")
        if use_tp and close >= long_tp
            strategy.close("Buy", comment="Long TP Hit")
    if strategy.position_size < 0
        short_entry = strategy.position_avg_price
        short_sl    = short_entry + sl_dollars
        short_tp    = short_entry - tp_dollars
        if use_sl and close >= short_sl
            strategy.close("Sell", comment="Short SL Hit")
        if use_tp and close <= short_tp
            strategy.close("Sell", comment="Short TP Hit")

// Bars Till Close logic
var int bars_since_entry = na
if strategy.position_size != 0
    bars_since_entry := na(bars_since_entry) ? 0 : bars_since_entry + 1
else
    bars_since_entry := na

if use_bars_till_close and not na(bars_since_entry) and bars_since_entry >= bars_till_close
    strategy.close("Buy", comment="Bars Till Close Hit")
    strategy.close("Sell", comment="Bars Till Close Hit")

// Plot buy/sell signals
plotshape(sell_condition and (not use_ema or ema_short_condition), title="Sell Signal", location=location.abovebar, color=color.red, style=shape.labeldown, text="Sell")
plotshape(buy_condition and (not use_ema or ema_long_condition), title="Buy Signal", location=location.belowbar, color=color.green, style=shape.labelup, text="Buy")Published by ChaoZhang on the FMZ strategy square · last modified 2025-02-10. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Adaptive-Bollinger-Bands-Trend-Following-Strategy-with-Multi-Level-Risk-Management.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- Bollinger Band Moving Average Crossover StrategyPine Script · Trend following · 1h
- Bollinger Bands and EMA Trend Following StrategyPine Script · Trend following · 1h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual Moving Average Crossover Dynamic Position Optimization Strategy with EMA Cross Signal SystemPine Script · Trend following · 1h
- EMA Cross Trend Following Strategy with SMA Stop Loss and Re Entry MechanismPine Script · Trend following · 1h