Adaptive Fibonacci Bollinger Bands Strategy Analysis
This strategy is an innovative trading system combining Fibonacci sequence and Bollinger Bands. It replaces traditional Bollinger Bands' standard deviation multipliers with Fibonacci ratios (1.618, 2.618, 4.236)…
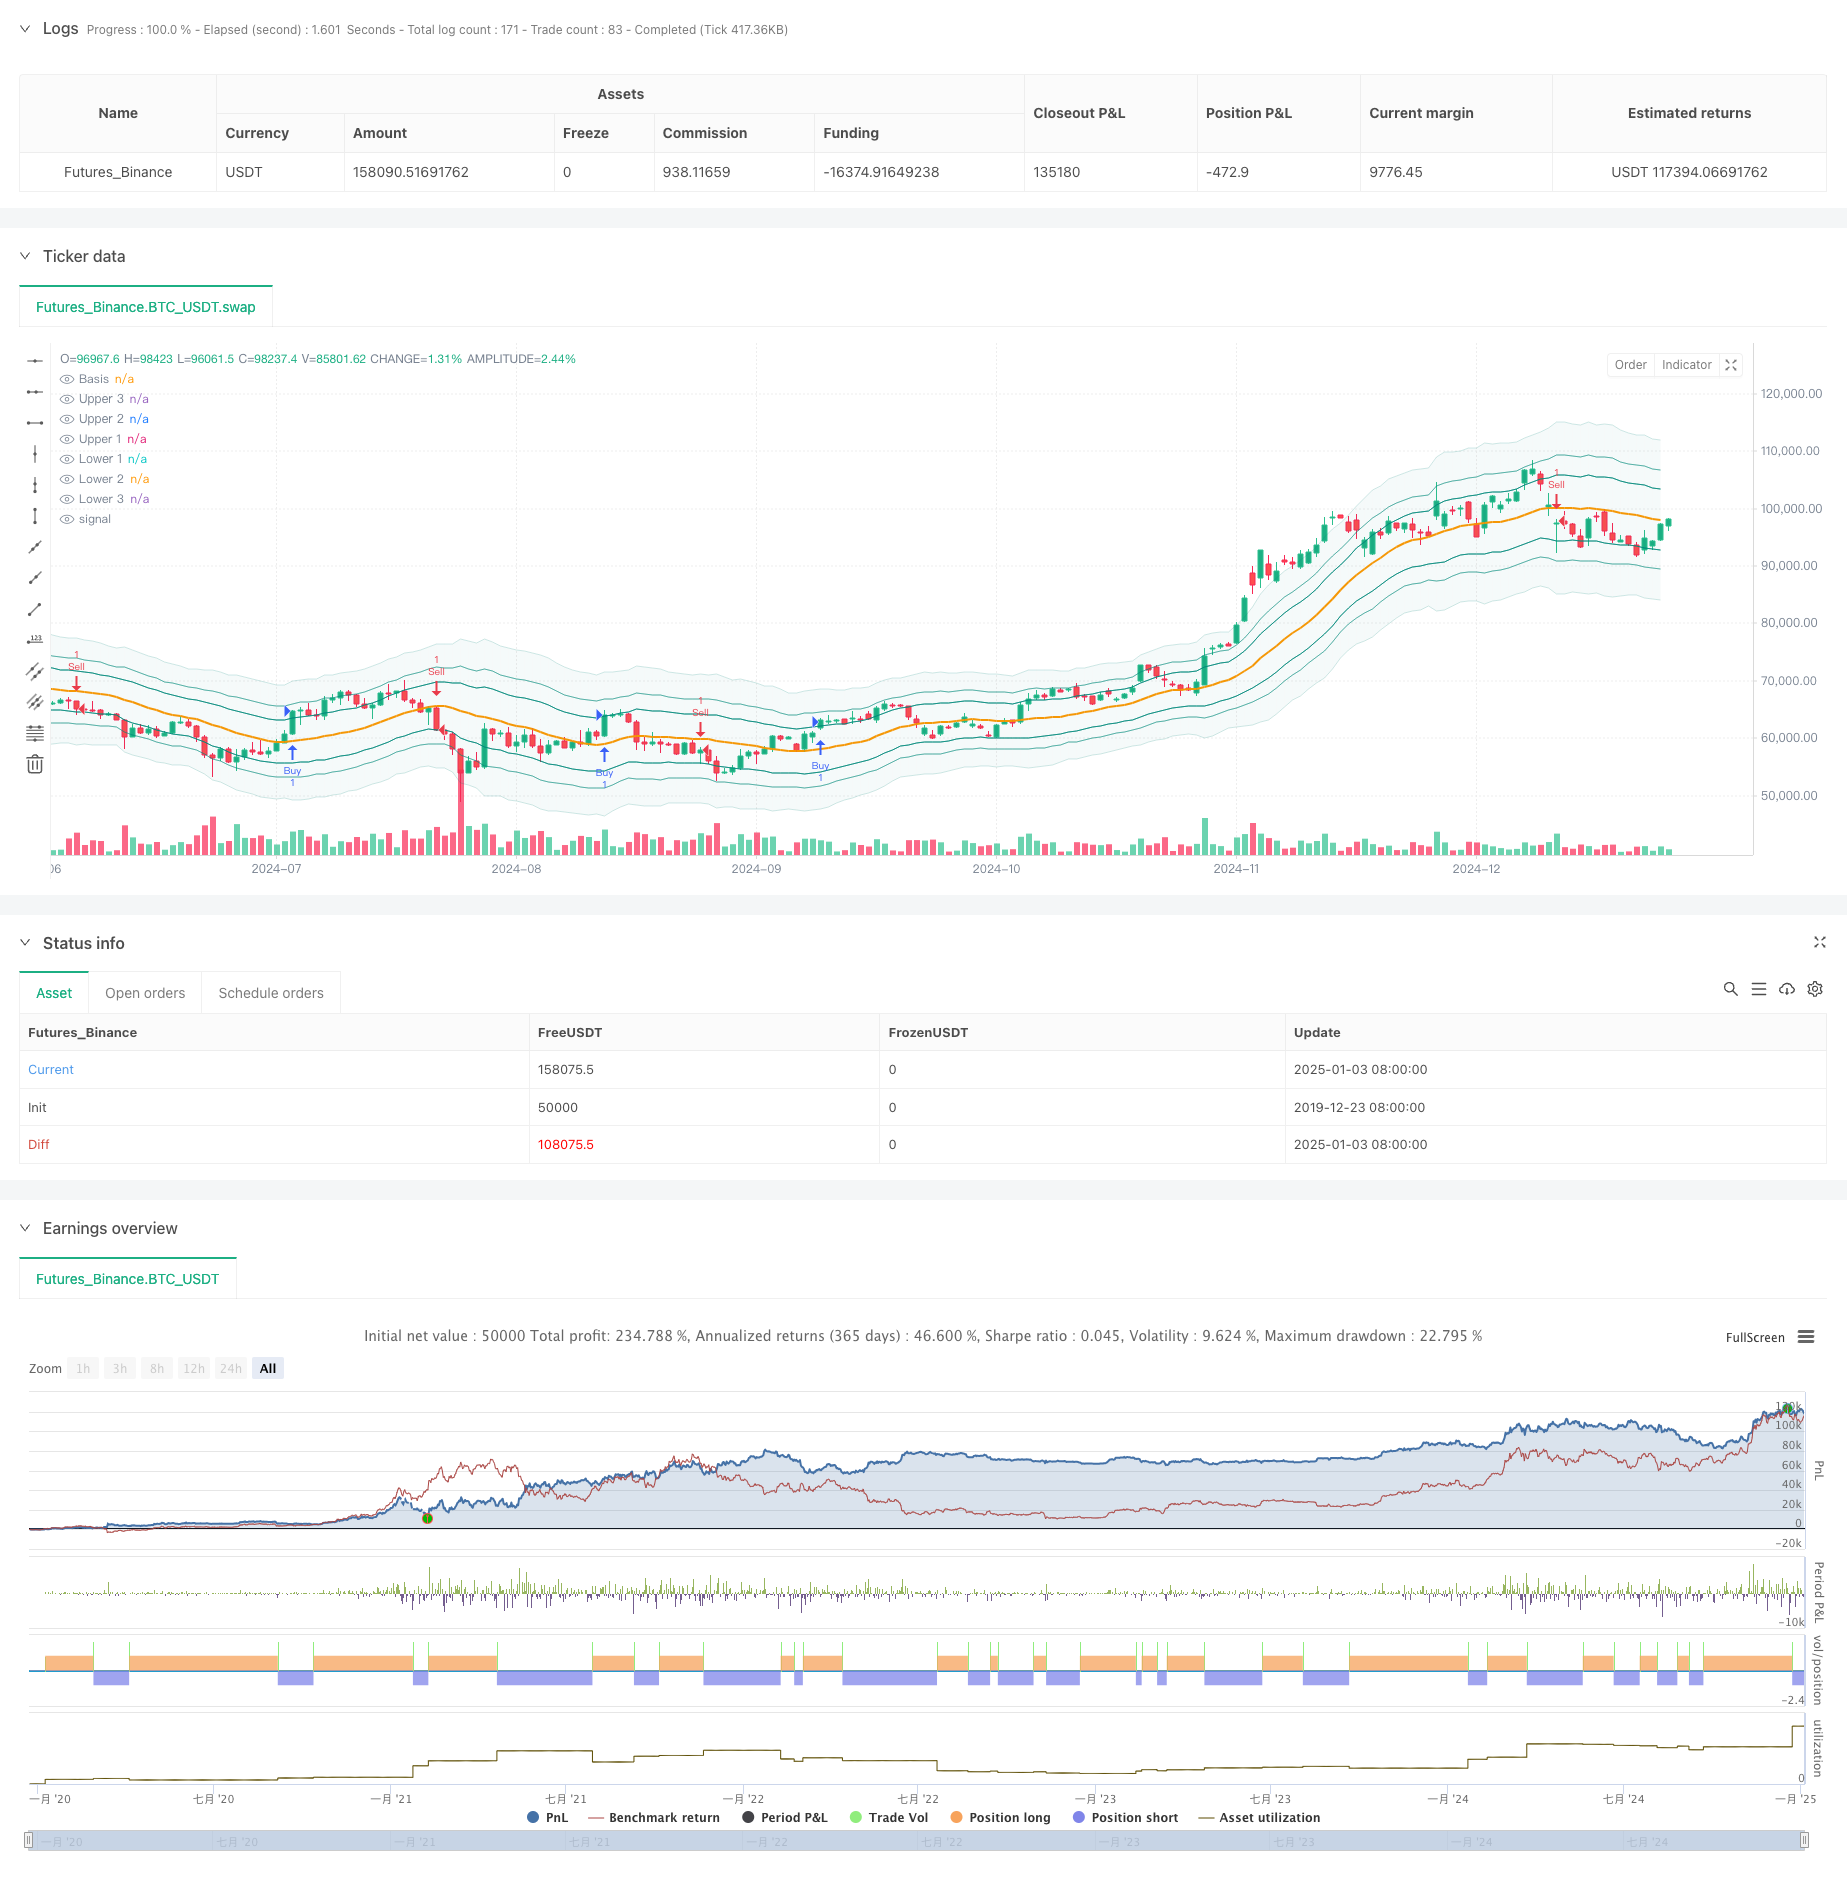
Overview
This strategy is an innovative trading system combining Fibonacci sequence and Bollinger Bands. It replaces traditional Bollinger Bands' standard deviation multipliers with Fibonacci ratios (1.618, 2.618, 4.236), creating a unique price volatility assessment system. The strategy includes comprehensive trade management features, including stop-loss/take-profit settings and trading time window filters, making it highly practical and flexible.
Strategy Principle
The core logic is based on price interactions with Fibonacci Bollinger Bands. It first calculates a Simple Moving Average (SMA) as the middle band, then uses ATR multiplied by different Fibonacci ratios to form upper and lower bands. Trading signals are generated when price breaks through user-selected Fibonacci bands. Specifically, a long signal is triggered when the low price is below and high price is above the target buy band; a short signal is triggered when the low price is below and high price is above the target sell band.
Strategy Advantages
- Strong Adaptability: Dynamically adjusts band width through ATR, better adapting to different market conditions
- High Flexibility: Users can choose different Fibonacci bands as trading signals based on their trading style
- Comprehensive Risk Management: Built-in take-profit/stop-loss and time filtering functions effectively control risk
- Visual Intuitiveness: Different transparency levels of band areas help traders understand market structure
- Clear Calculation Logic: Uses classic technical indicator combinations, easy to understand and maintain
Strategy Risks
- False Breakout Risk: Price may immediately retrace after breakout, generating false signals
- Parameter Sensitivity: Different Fibonacci ratio choices significantly affect strategy performance
- Time Dependency: When trading window is enabled, might miss important trading opportunities
- Market Environment Dependency: May generate excessive signals in ranging markets
Strategy Optimization Directions
- Signal Confirmation Mechanism: Suggest adding volume or momentum indicators for breakout confirmation
- Dynamic Parameter Optimization: Automatically adjust Fibonacci ratios based on market volatility
- Market Environment Filtering: Add trend identification functionality, use different parameters in different market conditions
- Signal Weighting System: Establish multi-timeframe analysis to improve signal reliability
- Position Management Optimization: Dynamically adjust position size based on market volatility and signal strength
Summary
This strategy innovatively combines classic technical analysis tools by optimizing traditional Bollinger Bands with Fibonacci sequence. Its main advantages lie in adaptability and flexibility, but attention must be paid to parameter selection and market environment compatibility. The strategy has significant improvement potential through adding additional confirmation indicators and optimizing signal generation mechanisms.
Source Pine Script
/*backtest
start: 2019-12-23 08:00:00
end: 2025-01-04 08:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
// © sapphire_edge

// # ========================================================================= #
// #
// #        _____                   __    _              ______    __
// #      / ___/____ _____  ____  / /_  (_)_______     / ____/___/ /___ ____
// #      \__ \/ __ `/ __ \/ __ \/ __ \/ / ___/ _ \   / __/ / __  / __ `/ _ \
// #     ___/ / /_/ / /_/ / /_/ / / / / / /  /  __/  / /___/ /_/ / /_/ /  __/
// #    /____/\__,_/ .___/ .___/_/ /_/_/_/   \___/  /_____/\__,_/\__, /\___/
// #              /_/   /_/                                     /____/
// #
// # ========================================================================= #

strategy(shorttitle="⟡Sapphire⟡ FiboBands Strategy", title="[Sapphire] Fibonacci Bollinger Bands Strategy", initial_capital= 50000, currency= currency.USD,default_qty_value = 1,commission_type= strategy.commission.cash_per_contract,overlay= true )

// # ========================================================================= #
// #                       // Settings Menu //
// # ========================================================================= #

// --------------------    Main Settings    -------------------- //
groupFiboBands = "FiboBands"
length = input.int(20, minval = 1, title = 'Length', group=groupFiboBands)
src = input(close, title = 'Source', group=groupFiboBands)
offset = input.int(0, 'Offset', minval = -500, maxval = 500, group=groupFiboBands)

fibo1 = input(defval = 1.618, title = 'Fibonacci Ratio 1', group=groupFiboBands)
fibo2 = input(defval = 2.618, title = 'Fibonacci Ratio 2', group=groupFiboBands)
fibo3 = input(defval = 4.236, title = 'Fibonacci Ratio 3', group=groupFiboBands)

fiboBuy = input.string(options = ['Fibo 1', 'Fibo 2', 'Fibo 3'], defval = 'Fibo 1', title = 'Fibonacci Buy', group=groupFiboBands)
fiboSell = input.string(options = ['Fibo 1', 'Fibo 2', 'Fibo 3'], defval = 'Fibo 1', title = 'Fibonacci Sell', group=groupFiboBands)

showSignals = input.bool(true, title="Show Signals", group=groupFiboBands)
signalOffset = input.int(5, title="Signal Vertical Offset", group=groupFiboBands)

// --------------------    Trade Management Inputs    -------------------- //
groupTradeManagement = "Trade Management"
useProfitPerc    = input.bool(false, title="Enable Profit Target", group=groupTradeManagement)
takeProfitPerc  = input.float(1.0, title="Take Profit (%)", step=0.1, group=groupTradeManagement)
useStopLossPerc    = input.bool(false, title="Enable Stop Loss", group=groupTradeManagement)
stopLossPerc    = input.float(1.0, title="Stop Loss (%)", step=0.1, group=groupTradeManagement)

// --------------------    Time Filter Inputs    -------------------- //
groupTimeOfDayFilter = "Time of Day Filter"
useTimeFilter1  = input.bool(false, title="Enable Time Filter 1", group=groupTimeOfDayFilter)
startHour1      = input.int(0, title="Start Hour (24-hour format)", minval=0, maxval=23, group=groupTimeOfDayFilter)
startMinute1    = input.int(0, title="Start Minute", minval=0, maxval=59, group=groupTimeOfDayFilter)
endHour1        = input.int(23, title="End Hour (24-hour format)", minval=0, maxval=23, group=groupTimeOfDayFilter)
endMinute1      = input.int(45, title="End Minute", minval=0, maxval=59, group=groupTimeOfDayFilter)
closeAtEndTimeWindow = input.bool(false, title="Close Trades at End of Time Window", group=groupTimeOfDayFilter)

// --------------------    Trading Window    -------------------- //
isWithinTradingWindow(startHour, startMinute, endHour, endMinute) =>
    nyTime            = timestamp("America/New_York", year, month, dayofmonth, hour, minute)
    nyHour            = hour(nyTime)
    nyMinute          = minute(nyTime)
    timeInMinutes     = nyHour * 60 + nyMinute
    startInMinutes    = startHour * 60 + startMinute
    endInMinutes      = endHour * 60 + endMinute
    timeInMinutes    >= startInMinutes and timeInMinutes <= endInMinutes

timeCondition =  (useTimeFilter1 ? isWithinTradingWindow(startHour1, startMinute1, endHour1, endMinute1) : true)

// Check if the current bar is the last one within the specified time window
isEndOfTimeWindow() =>
    nyTime            = timestamp("America/New_York", year, month, dayofmonth, hour, minute)
    nyHour            = hour(nyTime)
    nyMinute          = minute(nyTime)
    timeInMinutes     = nyHour * 60 + nyMinute
    endInMinutes      = endHour1 * 60 + endMinute1
    timeInMinutes == endInMinutes

// Logic to close trades if the time window ends
if timeCondition and closeAtEndTimeWindow and isEndOfTimeWindow()
    strategy.close_all(comment="Closing trades at end of time window")

// # ========================================================================= #
// #                       // Calculations //
// # ========================================================================= #

sma = ta.sma(src, length)
atr = ta.atr(length)

ratio1 = atr * fibo1
ratio2 = atr * fibo2
ratio3 = atr * fibo3

upper3 = sma + ratio3
upper2 = sma + ratio2
upper1 = sma + ratio1

lower1 = sma - ratio1
lower2 = sma - ratio2
lower3 = sma - ratio3

// # ========================================================================= #
// #                       // Signal Logic //
// # ========================================================================= #

// --------------------    Entry Logic    -------------------- //
targetBuy = fiboBuy == 'Fibo 1' ? upper1 : fiboBuy == 'Fibo 2' ? upper2 : upper3
buy = low < targetBuy and high > targetBuy

// --------------------    User-Defined Exit Logic    -------------------- //
targetSell = fiboSell == 'Fibo 1' ? lower1 : fiboSell == 'Fibo 2' ? lower2 : lower3
sell = low < targetSell and high > targetSell

// # ========================================================================= #
// #                       // Strategy Management //
// # ========================================================================= #

// --------------------    Trade Execution Flags    -------------------- //
var bool buyExecuted = false
var bool sellExecuted = false

float labelOffset = ta.atr(14) * signalOffset

// --------------------    Buy Logic    -------------------- //
if buy and timeCondition
    if useProfitPerc or useStopLossPerc
        strategy.entry("Buy", strategy.long, stop=(useStopLossPerc ? close * (1 - stopLossPerc / 100) : na), limit=(useProfitPerc ? close * (1 + takeProfitPerc / 100) : na))
    else
        strategy.entry("Buy", strategy.long)

    if showSignals and not buyExecuted
        buyExecuted := true
        sellExecuted := false
        label.new(bar_index, high - labelOffset, "◭", style=label.style_label_up, color = color.rgb(119, 0, 255, 20), textcolor=color.white)

// --------------------    Sell Logic    -------------------- //
if sell and timeCondition
    if useProfitPerc or useStopLossPerc
        strategy.entry("Sell", strategy.short, stop=(useStopLossPerc ? close * (1 + stopLossPerc / 100) : na), limit=(useProfitPerc ? close * (1 - takeProfitPerc / 100) : na))
    else
        strategy.entry("Sell", strategy.short)

    if showSignals and not sellExecuted
        sellExecuted := true
        buyExecuted := false
        label.new(bar_index, low + labelOffset, "⧩", style=label.style_label_down, color = color.rgb(255, 85, 0, 20), textcolor=color.white)


// # ========================================================================= #
// #                         // Plots and Charts //
// # ========================================================================= #

plot(sma, style = plot.style_line, title = 'Basis', color = color.new(color.orange, 0), linewidth = 2, offset = offset)

upp3 = plot(upper3, title = 'Upper 3', color = color.new(color.teal, 90), offset = offset)
upp2 = plot(upper2, title = 'Upper 2', color = color.new(color.teal, 60), offset = offset)
upp1 = plot(upper1, title = 'Upper 1', color = color.new(color.teal, 30), offset = offset)

low1 = plot(lower1, title = 'Lower 1', color = color.new(color.teal, 30), offset = offset)
low2 = plot(lower2, title = 'Lower 2', color = color.new(color.teal, 60), offset = offset)
low3 = plot(lower3, title = 'Lower 3', color = color.new(color.teal, 90), offset = offset)

fill(upp3, low3, title = 'Background', color = color.new(color.teal, 95))
Published by ChaoZhang on the FMZ strategy square · last modified 2025-01-06. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Adaptive-Fibonacci-Bollinger-Bands-Strategy-Analysis.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Moving Average Crossover and Upper Rail Breakthrough Impulse StrategyPine Script · Breakout · 1m
- Dual MA Indicator Oscillating Price Tracking StrategyPine Script · Breakout · 2h
- BB Breakout StrategyPine Script · Breakout · 1d
- Bollinger Band Breakout Trend Following StrategyPine Script · Breakout · 1d
- EMA and Bollinger Bands Breakout StrategyPine Script · Breakout · 1h
- Follow Line StrategyPine Script · Breakout · 10m