Moving Average Crossover and Upper Rail Breakthrough Impulse Strategy
This strategy utilizes the crossover signals of the MACD fast line and slow line, combined with judgments based on multiple other indicators, to capture the breakthrough signals of the moving average index line in a…
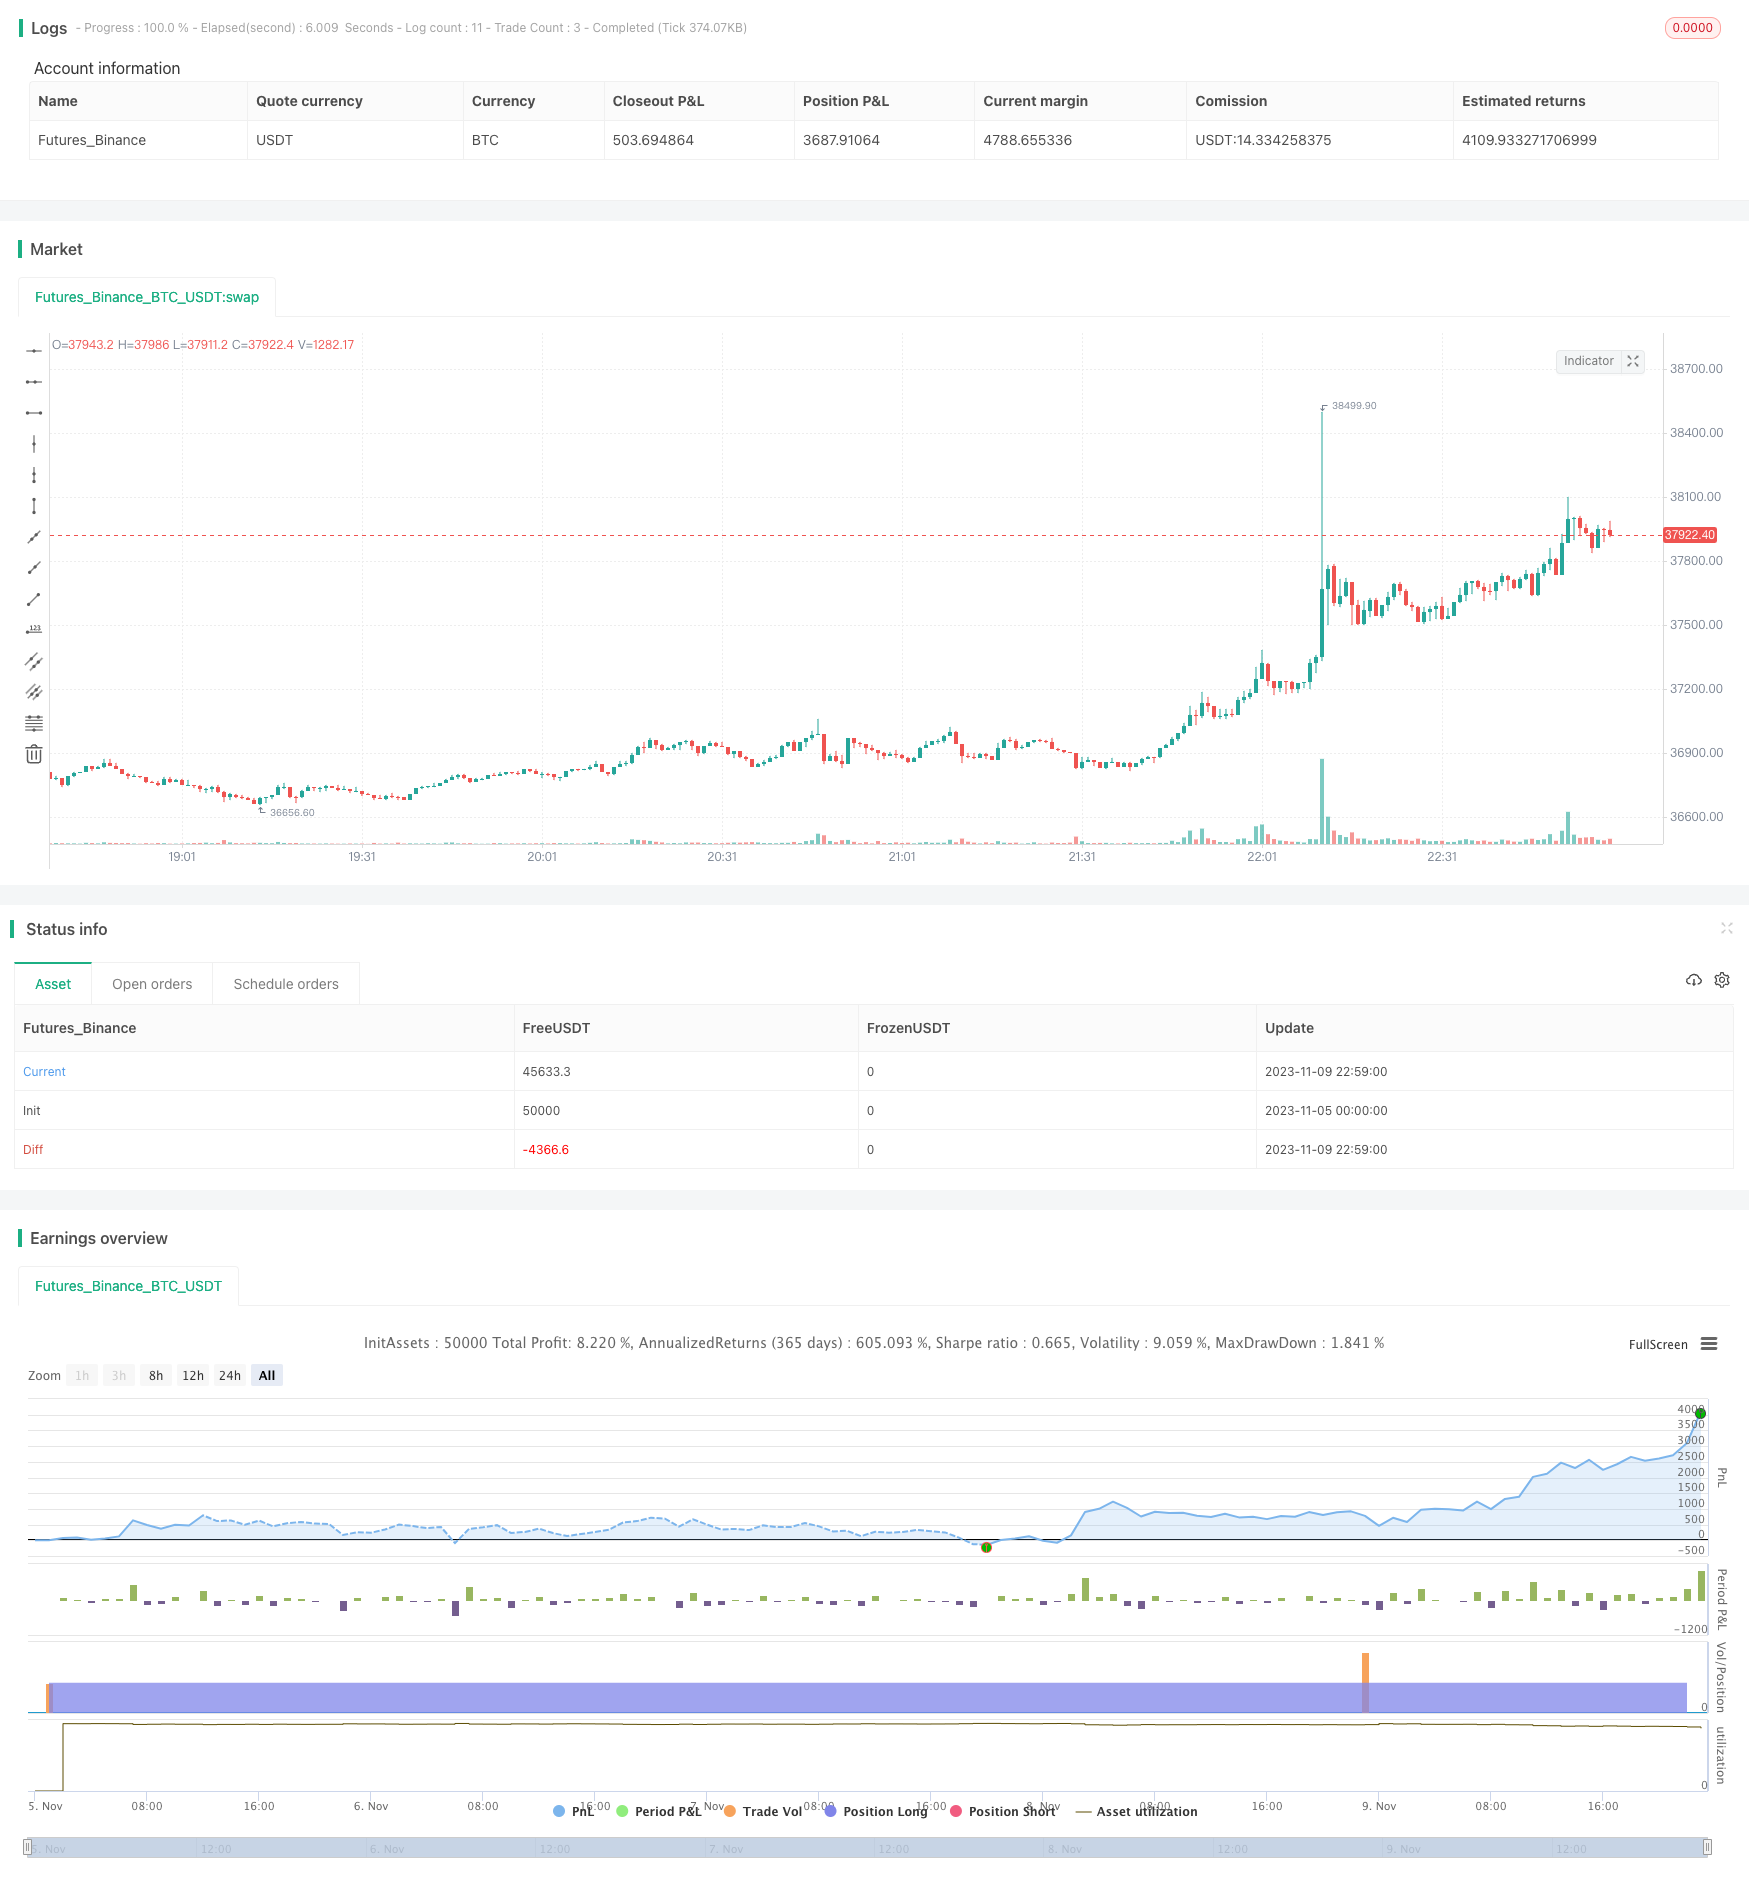
Overview
This strategy utilizes the crossover signals of the MACD fast line and slow line, combined with judgments based on multiple other indicators, to capture the breakthrough signals of the moving average index line in a timely manner and make buy or sell decisions. It belongs to a short-term trading strategy.
Strategy Logic
Use the crossover of the MACD fast line and slow line as the primary trading signal. When the fast line crosses above the slow line, take a long position. When the fast line crosses below the slow line, take a short position.
Incorporate the RSI indicator to determine overbought and oversold conditions. Below the centerline suggests long, while above suggests short.
Compare the current closing price to the SMA line of a certain period. Closing price below SMA suggests long, while above suggests short.
Calculate the 0.5 Fibonacci level of the Highest value of a certain period as the resistance for long. Calculate the 0.5 Fibonacci level of the Lowest value of a certain period as the support for short.
Take long when the fast line crosses above and the price is below support. Take short when the fast line crosses below and the price is above resistance.
Adopt a trailing stop loss mechanism. The stop loss is fixed at a certain percentage of the entry price initially. When the loss reaches a certain level, switch to a gradual trailing stop loss.
Advantages
The strategy makes full use of the MACD crossover signals, which is a classic and effective technical indicator trading signal.
Incorporating confirmations from multiple indicators like RSI and SMA can filter false signals and improve reliability.
Calculating dynamic support and resistance levels for breakout trading can capture larger trends.
The trailing stop loss can lock in most profits while controlling risk.
The strategy logic is clear and simple, easy to understand and master for beginners.
Risks
The MACD indicator has lagging issues and may miss the optimal entry and exit points.
Combining multiple indicators increases complexity and risks of conflicting signals.
There are risks of incorrect breakouts when dynamically calculating support and resistance.
Trailing stop loss may exit prematurely in strong trends, failing to ride trends.
Parameters require repetitive testing and optimization, improper parameters negatively impact performance.
Optimization Directions
Test different parameter combinations to optimize MACD periods.
Introduce more indicators like Bollinger Bands, KDJ for multidimensional analysis.
Incorporate more factors to judge the reasonableness of support and resistance.
Research more advanced stop loss mechanisms like time-based or volatility-based stops.
Add an auto-optimization module for automatic parameter optimization.
Summary
This strategy combines MACD, RSI, SMA and other indicators to capture moving average breakthrough signals opportunistically. It belongs to typical short-term breakout trading strategies. There is some lag in its signal generation, but accuracy can be improved through parameter optimization. Overall, this is a strategy with simple and clear logic, easy to grasp for most, and worth further testing and optimization.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_2 | 60 | Strategy Decision Time Frame |
| v_input_1 | BINANCE:BTCUSDT | (?SYMBOL)Symbol |
| v_input_3 | 14 | (?ADX)ADX Smoothing |
| v_input_4 | 14 | ADX DI Length |
| v_input_5 | 30 | ADX EMA |
| v_input_6 | 19 | ADX CONSTANT |
| v_input_7 | 50 | (?FIBO MACD SMA)Fibo Look Back Canles |
| v_input_8 | 30 | SMA Look Back Candles |
| v_input_9 | 15 | MACD Fast Lenght |
| v_input_10 | 30 | MACD Slow Lenght |
| v_input_11 | 9 | MACD Signal Smoothing |
| v_input_12 | 100 | MACD Look Back Candles |
| v_input_13 | 2 | (?TP & SL)Trailing Long Stop % |
| v_input_14 | 2 | Trailing Short Stop % |
| v_input_15 | 2 | Long Profit Start % |
| v_input_16 | 2 | Short Profit Start % |
| v_input_17 | 3 | Max Long Stop Loss (%) |
| v_input_18 | 2.5 | Max Short Stop Loss (%) |
| v_input_19 | 100 | Long Take Profit (%) |
| v_input_20 | 100 | Short Take Profit (%) |
| v_input_21 | 95 | (?CAPITAL TO INVEST)Capital Percentage to Invest (%) |
Source Pine Script
/*backtest
start: 2023-11-05 00:00:00
end: 2023-11-09 23:00:00
period: 1m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © onurenginogutcu

//@version=4
strategy("R19 STRATEGY", overlay=true, calc_on_every_tick=true , margin_long=100, margin_short=100 ,  process_orders_on_close=true )


sym = input(title="Symbol", type=input.symbol, defval="BINANCE:BTCUSDT" , group = "SYMBOL")
timeFrame = input(title="Strategy Decision Time Frame", type = input.resolution ,  defval="60")

adxlen = input(14, title="ADX Smoothing" , group = "ADX")
dilen = input(14, title="ADX DI Length", group = "ADX")
adxemalenght = input(30, title="ADX EMA", group = "ADX")
adxconstant = input(19, title="ADX CONSTANT", group = "ADX")

fibvar = input (title = "Fibo Look Back Canles" , defval = 50 , minval = 0 , group = "FIBO MACD SMA")
smaLookback = input (title = "SMA Look Back Candles" , defval = 30 , minval = 0 , group = "FIBO MACD SMA")
MACDFast = input (title = "MACD Fast Lenght" , defval = 15 , minval = 0 , group = "FIBO MACD SMA")
MACDSlow = input (title = "MACD Slow Lenght" , defval = 30 , minval = 0 , group = "FIBO MACD SMA")
MACDSmooth = input (title = "MACD Signal Smoothing" , defval = 9 , minval = 0 , group = "FIBO MACD SMA")
MACDLookback = input (title = "MACD Look Back Candles" , defval = 100 , minval = 0 , group = "FIBO MACD SMA")

trailingStopLong = input (title = "Trailing Long Stop %" , defval = 2.0 , step = 0.1, group = "TP & SL") * 0.01
trailingStopShort = input (title = "Trailing Short Stop %" , defval = 2.0 , step = 0.1 , group = "TP & SL") * 0.01
LongTrailingProfitStart = input (title = "Long Profit Start %" , defval = 2.0 , step = 0.1 , group = "TP & SL") * 0.01
ShortTrailingProfitStart = input (title = "Short Profit Start %" , defval = 2.0 , step = 0.1, group = "TP & SL") * 0.01

lsl = input(title="Max Long Stop Loss (%)",
     minval=0.0, step=0.1, defval=3.0, group = "TP & SL") * 0.01

ssl = input(title="Max Short Stop Loss (%)",
     minval=0.0, step=0.1, defval=2.5, group = "TP & SL") * 0.01

longtp = input(title="Long Take Profit (%)",
     minval=0.0, step=0.1, defval=100, group = "TP & SL") * 0.01

shorttp = input(title="Short Take Profit (%)",
     minval=0.0, step=0.1, defval=100, group = "TP & SL") * 0.01

capperc = input(title="Capital Percentage to Invest (%)",
     minval=0.0, maxval=100, step=0.1, defval=95, group = "CAPITAL TO INVEST") * 0.01


symClose = security(sym, timeFrame, close)
symHigh = security(sym, timeFrame, high)
symLow = security(sym, timeFrame, low)

atr = atr (14)

/////////adx code

dirmov(len) =>
	up = change(symHigh)
	down = -change(symLow)
	plusDM = na(up) ? na : (up > down and up > 0 ? up : 0)
	minusDM = na(down) ? na : (down > up and down > 0 ? down : 0)
	truerange = rma(tr, len)
	plus = fixnan(100 * rma(plusDM, len) / truerange)
	minus = fixnan(100 * rma(minusDM, len) / truerange)
	[plus, minus]
adx(dilen, adxlen) =>
	[plus, minus] = dirmov(dilen)
	sum = plus + minus
	adx = 100 * rma(abs(plus - minus) / (sum == 0 ? 1 : sum), adxlen)
sig = adx(dilen, adxlen)
emasig = ema (sig , adxemalenght )


////////adx code over


i = ema (symClose , MACDFast) - ema (symClose , MACDSlow)
r = ema (i , MACDSmooth)

sapust = highest (i , MACDLookback) * 0.729
sapalt = lowest (i , MACDLookback) * 0.729


simRSI = rsi (symClose , 50 )


fibtop = lowest (symLow , fibvar) + ((highest (symHigh , fibvar) - lowest (symLow , fibvar)) * 0.50)
fibbottom = lowest (symLow , fibvar) + ((highest (symHigh , fibvar) - lowest (symLow , fibvar)) * 0.50)


cond1 = 0
cond2 = 0
cond3 = 0
cond4 = 0


longCondition = crossover(i, r) and i < sapalt and sig > adxconstant and symClose < sma (symClose , smaLookback) and simRSI < sma (simRSI , 50) and symClose < fibbottom
shortCondition = crossunder(i, r) and i > sapust and sig > adxconstant and  symClose > sma (symClose , smaLookback) and simRSI > sma (simRSI , 50) and symClose > fibtop


//////////////////////probability long/short
if (crossover(i, r) and i < sapalt)
    cond1 := 35
else if (crossunder(i, r) and i > sapust)
    cond1 := -35
else
    cond1 := 0

if (symClose < sma (symClose , smaLookback))
    cond2 := 30
else if (symClose > sma (symClose , smaLookback))
    cond2 := -30
else
    cond2 := 0

if (simRSI < sma (simRSI , 50))
    cond3 := 25
else if (simRSI > sma (simRSI , 50))
    cond3 := -25
else
    cond3 := 0

if (symClose < fibbottom)
    cond4 := 10
else if (symClose > fibbottom)
    cond4 := -10
else
    cond4 := 0

probab = cond1 + cond2 + cond3 + cond4
////////////////////////////////////////////////////////////////

///////////////////////////////////////////STRATEGY ENTRIES AND STOP LOSSES /////
var startTrail = 0
var trailingLongPrice = 0.0
var trailingShortPrice = 0.0

if (longCondition and strategy.position_size == 0)
    strategy.entry("Long", strategy.long , qty = capperc * strategy.equity / close )

if (shortCondition and strategy.position_size == 0)
    strategy.entry("Short" , strategy.short , qty = capperc * strategy.equity / close )


if (strategy.position_size == 0)
    trailingShortPrice := 0.0
    trailingLongPrice := 0.0
    startTrail := 0
/////////////////////////////////strategy exit

if (strategy.position_size > 0 and close >= strategy.position_avg_price * (1 + LongTrailingProfitStart))
    startTrail := 1

if (strategy.position_size < 0 and close <= strategy.position_avg_price * (1 - ShortTrailingProfitStart))
    startTrail := -1


trailingLongPrice := if strategy.position_size > 0 and startTrail == 1
    stopMeasure = close * (1 - trailingStopLong)
    max (stopMeasure , trailingLongPrice [1])
else if strategy.position_size > 0 and startTrail == 0
    strategy.position_avg_price * (1 - lsl)


trailingShortPrice := if strategy.position_size < 0 and startTrail == -1
    stopMeasure = close * (1 + trailingStopShort)
    min (stopMeasure , trailingShortPrice [1])
else if strategy.position_size < 0 and startTrail == 0
    strategy.position_avg_price * (1 + ssl)


if (strategy.position_size > 0)
    strategy.exit("Exit Long", "Long", stop = trailingLongPrice , limit=strategy.position_avg_price*(1 + longtp))


if (strategy.position_size < 0)
    strategy.exit("Exit Short", "Short", stop = trailingShortPrice , limit=strategy.position_avg_price*(1 - shorttp))


////////////////////////vertical colouring signals
bgcolor(color=longCondition ? color.new (color.green , 70) : na)
bgcolor(color=shortCondition ? color.new (color.red , 70) : na)

plot (trailingLongPrice , color = color.green) ///long price trailing stop
plot (trailingShortPrice , color = color.red) /// short price trailing stop
plot (startTrail , color = color.yellow)
plot (probab , color = color.white) ////probability
Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-13. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Moving-Average-Crossover-and-Upper-Rail-Breakthrough-Impulse-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Momentum Breakout Moving Average StrategyPine Script · Breakout · 1d
- Momentum Breakout Trading Strategy 440964Pine Script · Breakout · 5m
- Quantitative Trading Strategy Based on Ichimoku with Multiple SignalsPine Script · Breakout · 1h
- Volatility Breakthrough StrategyPine Script · Breakout · 10m
- Cross Timeframe SuperTrend Breakout StrategyPine Script · Breakout · 1h
- Momentum Breakout Intraday Trading StrategyPine Script · Breakout · 5m