Adaptive Fluctuation Strategy Based on Quantitative Range Breakthrough
This strategy calculates the highest and lowest transaction volume over a certain recent period to form an adaptive fluctuation range. When the transaction volume of the current cycle breaks through this range…
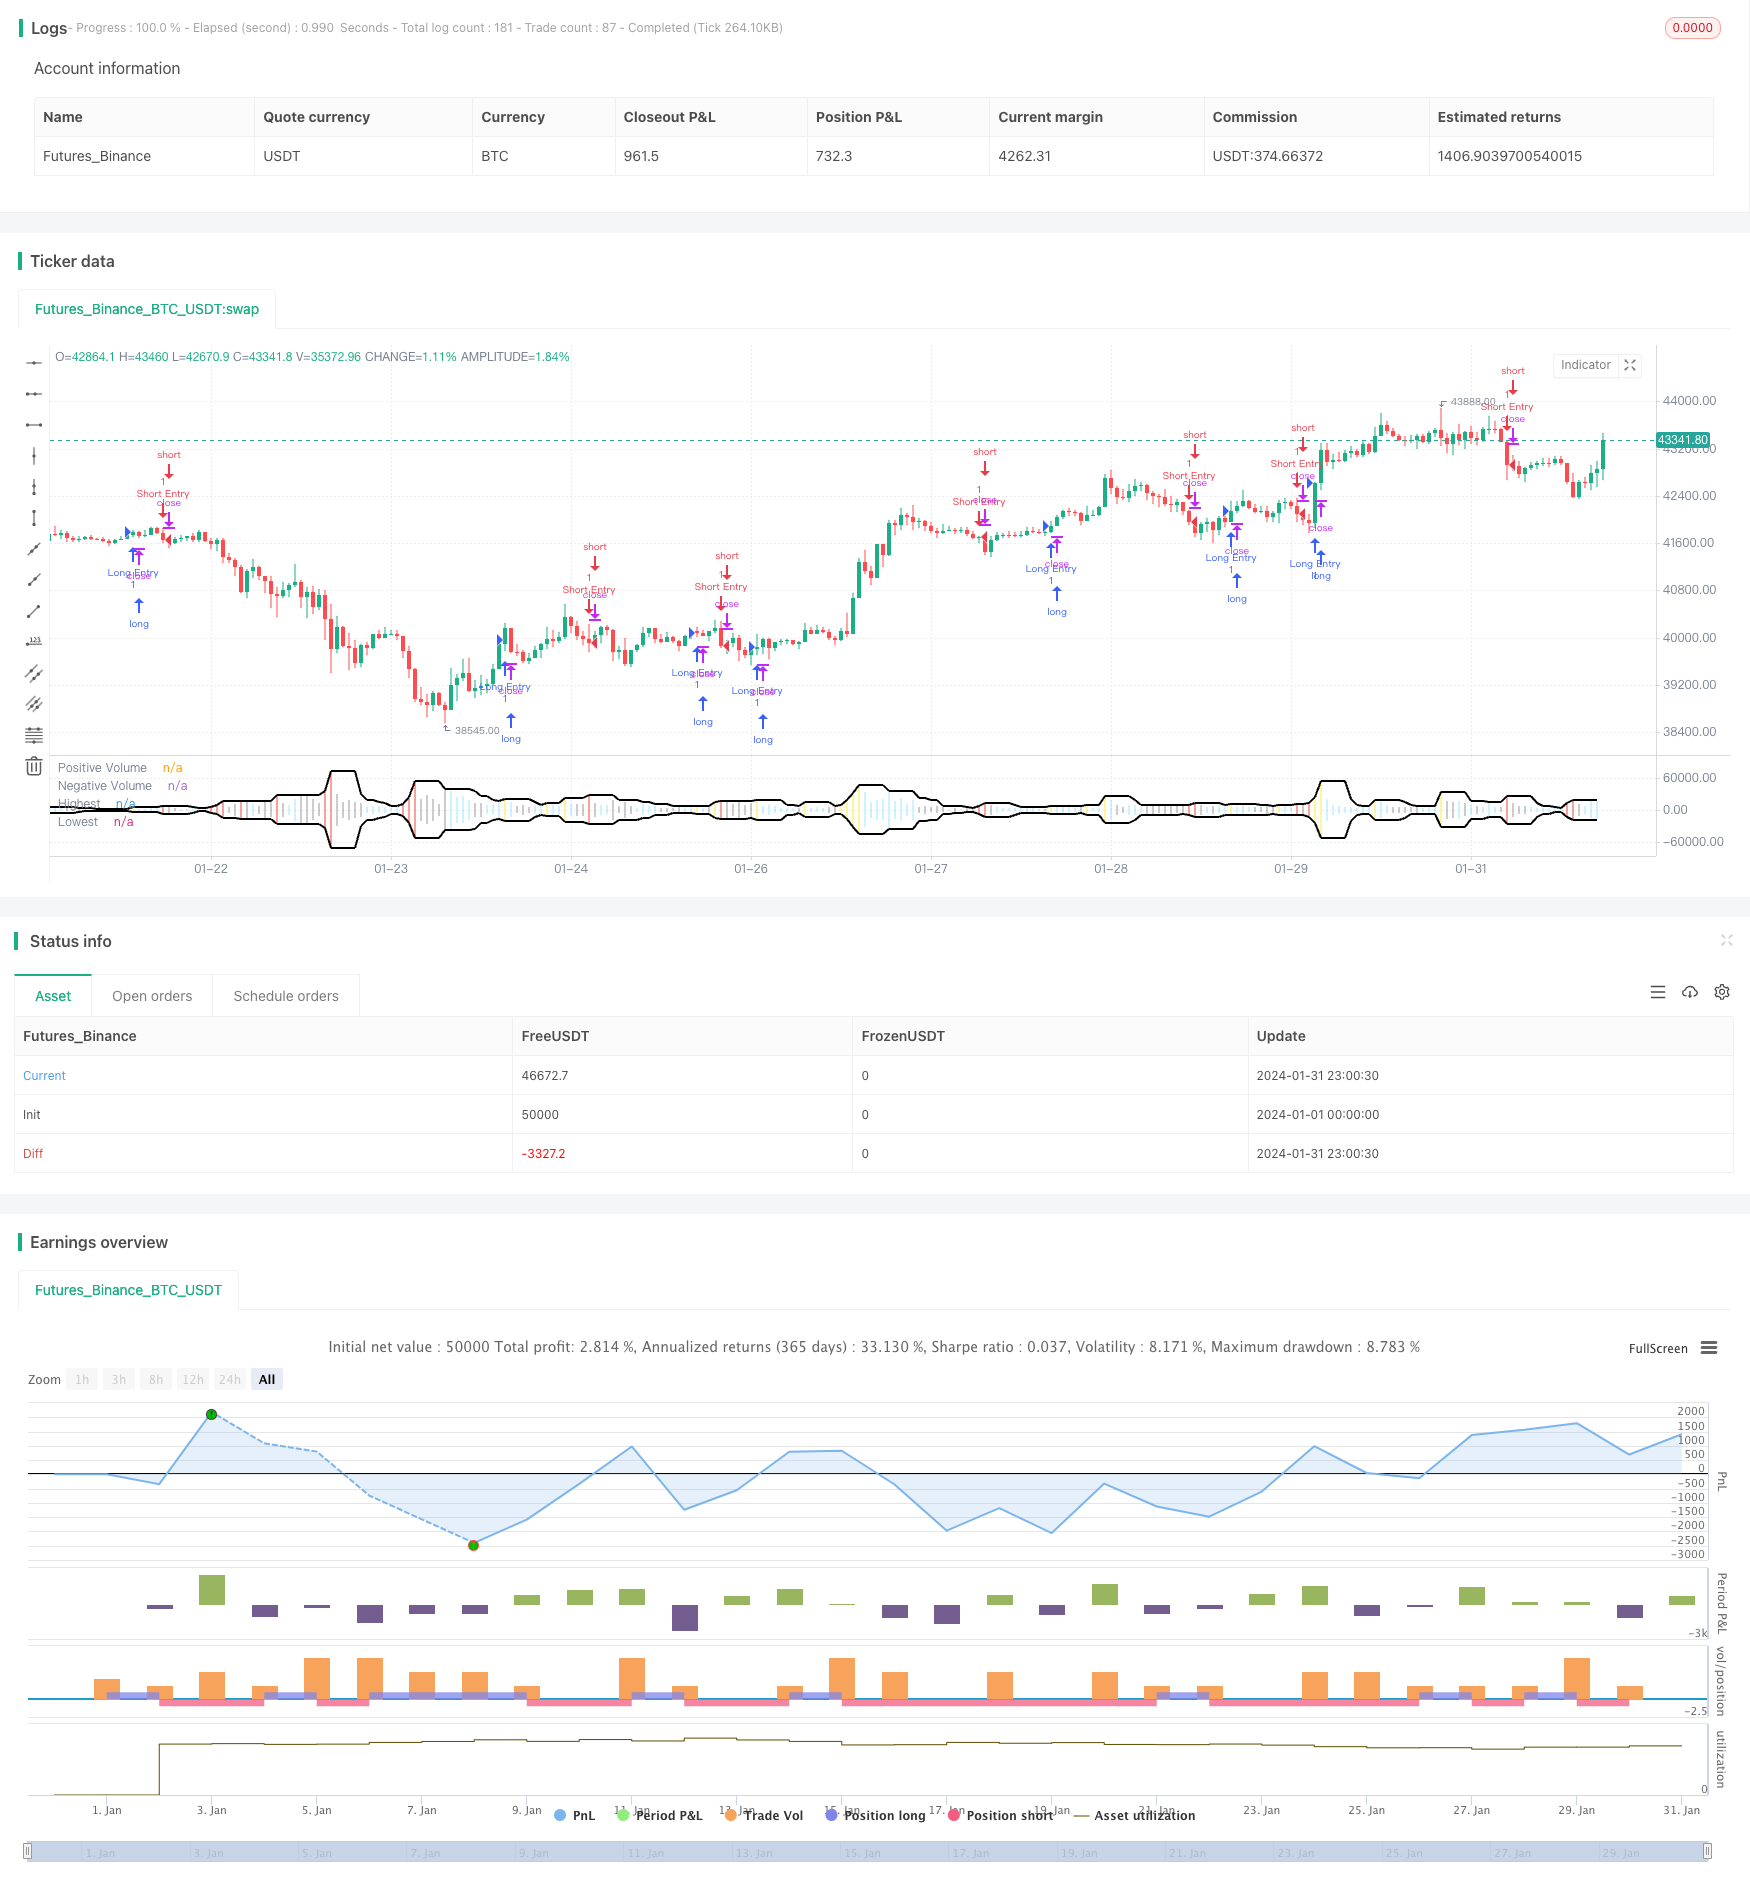
Overview
This strategy calculates the highest and lowest transaction volume over a certain recent period to form an adaptive fluctuation range. When the transaction volume of the current cycle breaks through this range, trading signals are generated. The signal direction is determined by the Yin Yang candlestick, which is a simple and effective strategy to track sudden large single transactions in the market.
Strategy Logic
The core logic is to calculate the highest and lowest values of positive and negative transaction volumes in the most recent N cycles to form an adaptive fluctuation range. Determine if a breakthrough occurs in the current period based on this range while taking into account the Yin Yang line signal to complete the judgment.
The specific calculation process is:
- Calculate the highest transaction volume Highest and the lowest transaction volume Lowest in the most recent N cycles
- Determine if the transaction volume Volume of the current cycle is higher than Highest
- Combine whether the current candlestick is Yin or Yang to complete the breakthrough signal judgment
- Generate long and short signals
Advantage Analysis
The main advantages of this strategy are:
- Adaptive range setting is sensitive to market changes
- Capture high volatility surge trends, reduce rate of missing transactions
- Combine candle shape judgments to avoid false breakthroughs
- Simple to implement and modify
- Parameters are adjustable to suit different products
Risk Analysis
The strategy also has some risks:
- Prone to chasing highs and killing lows, need to adjust parameters to control
- May frequently generate false signals in large cycle oscillating markets
- Cannot distinguish normal and abnormal breakthroughs, need to incorporate other indicators or patterns for judgment
- Only one entry opportunity for each breakthrough, cannot track trends
Adjusting cycle parameters and incorporating other indicators for filtering can optimize.
Optimization Directions
The strategy can be optimized in several ways:
- Increase intervals to adjust range length to suit different market cycles
- Incorporate MA, Bollinger Bands etc. to filter signals
- Optimize combinations with candlestick patterns to avoid false signals
- Add re-entry and stop loss modules so strategy can track trends
Summary
The strategy is overall simple and practical. By combining adaptive range and volume price analysis it can effectively capture one-sided explosive markets. However there are also certain risk of false signals, requiring appropriate parameter tweak and complementary tools before it can achieve maximum impact.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 5 | Range Length |
| v_input_2 | true | Heikin Ashi Colors |
| v_input_3 | true | Show Bar Colors |
| v_input_4 | true | Show Break-Out |
| v_input_5 | true | Show Range |
Source Pine Script
/*backtest
start: 2024-01-01 00:00:00
end: 2024-01-31 23:59:59
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © EvoCrypto

//@version=4
strategy("Ranged Volume Strategy - evo", shorttitle="Ranged Volume", format=format.volume)

// INPUTS {
Range_Length    =   input(5,        title="Range Length",                       minval=1)

Heikin_Ashi     =   input(true,     title="Heikin Ashi Colors")
Display_Bars    =   input(true,     title="Show Bar Colors")
Display_Break   =   input(true,     title="Show Break-Out")
Display_Range   =   input(true,     title="Show Range")
// }

// SETTINGS {
Close           =   Heikin_Ashi ? security(heikinashi(syminfo.tickerid), timeframe.period, close)    : close
Open            =   Heikin_Ashi ? security(heikinashi(syminfo.tickerid), timeframe.period, open)     : open

Positive        =    volume
Negative        =   -volume

Highest         =   highest(volume, Range_Length)
Lowest          =   lowest(-volume, Range_Length)

Up              =   Highest > Highest[1] and Close > Open
Dn              =   Highest > Highest[1] and Close < Open

Volume_Color    =
 Display_Break and Up   ? color.new(#ffeb3b, 0)     :
 Display_Break and Dn   ? color.new(#f44336, 0)     :
 Close > Open           ? color.new(#00c0ff, 60)    :
 Close < Open           ? color.new(#000000, 60)    : na
// }

//PLOTS {
plot(Positive,                      title="Positive Volume",    color=Volume_Color,             style=plot.style_histogram,  linewidth=4)
plot(Negative,                      title="Negative Volume",    color=Volume_Color,             style=plot.style_histogram,  linewidth=4)

plot(Display_Range ? Highest : na,  title="Highest",            color=color.new(#000000, 0),    style=plot.style_line,       linewidth=2)
plot(Display_Range ? Lowest  : na,  title="Lowest",             color=color.new(#000000, 0),    style=plot.style_line,       linewidth=2)

barcolor(Display_Bars ? Volume_Color : na)
// }

if (Up)
    strategy.entry("Long Entry", strategy.long)
if (Dn)
    strategy.entry("Short Entry", strategy.short)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-22. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Adaptive-Fluctuation-Strategy-Based-on-Quantitative-Range-Breakthrough.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Momentum Breakout Trading Strategy 440964Pine Script · Breakout · 5m
- Moving Average Bollinger Bands Breakout StrategyPine Script · Breakout · 1h
- Multi Indicator Momentum Breakout with Smoothed Candlestick Trading StrategyPine Script · Breakout · 6h
- Hybrid Moving Average Breakout Turtle Trading StrategyPine Script · Breakout · 1d
- Momentum Breakout Strategy 432076Pine Script · Breakout · 1d
- MACD Bollinger Turtle Trading StrategyPine Script · Breakout · 1d