Advanced RSI Indicator Trading Strategy
The S&P500 Advanced RSI Indicator Trading Strategy is a medium to long term trend following strategy for trading the S&P500 index. This strategy combines multiple filters with RSI overbought and oversold signals to…
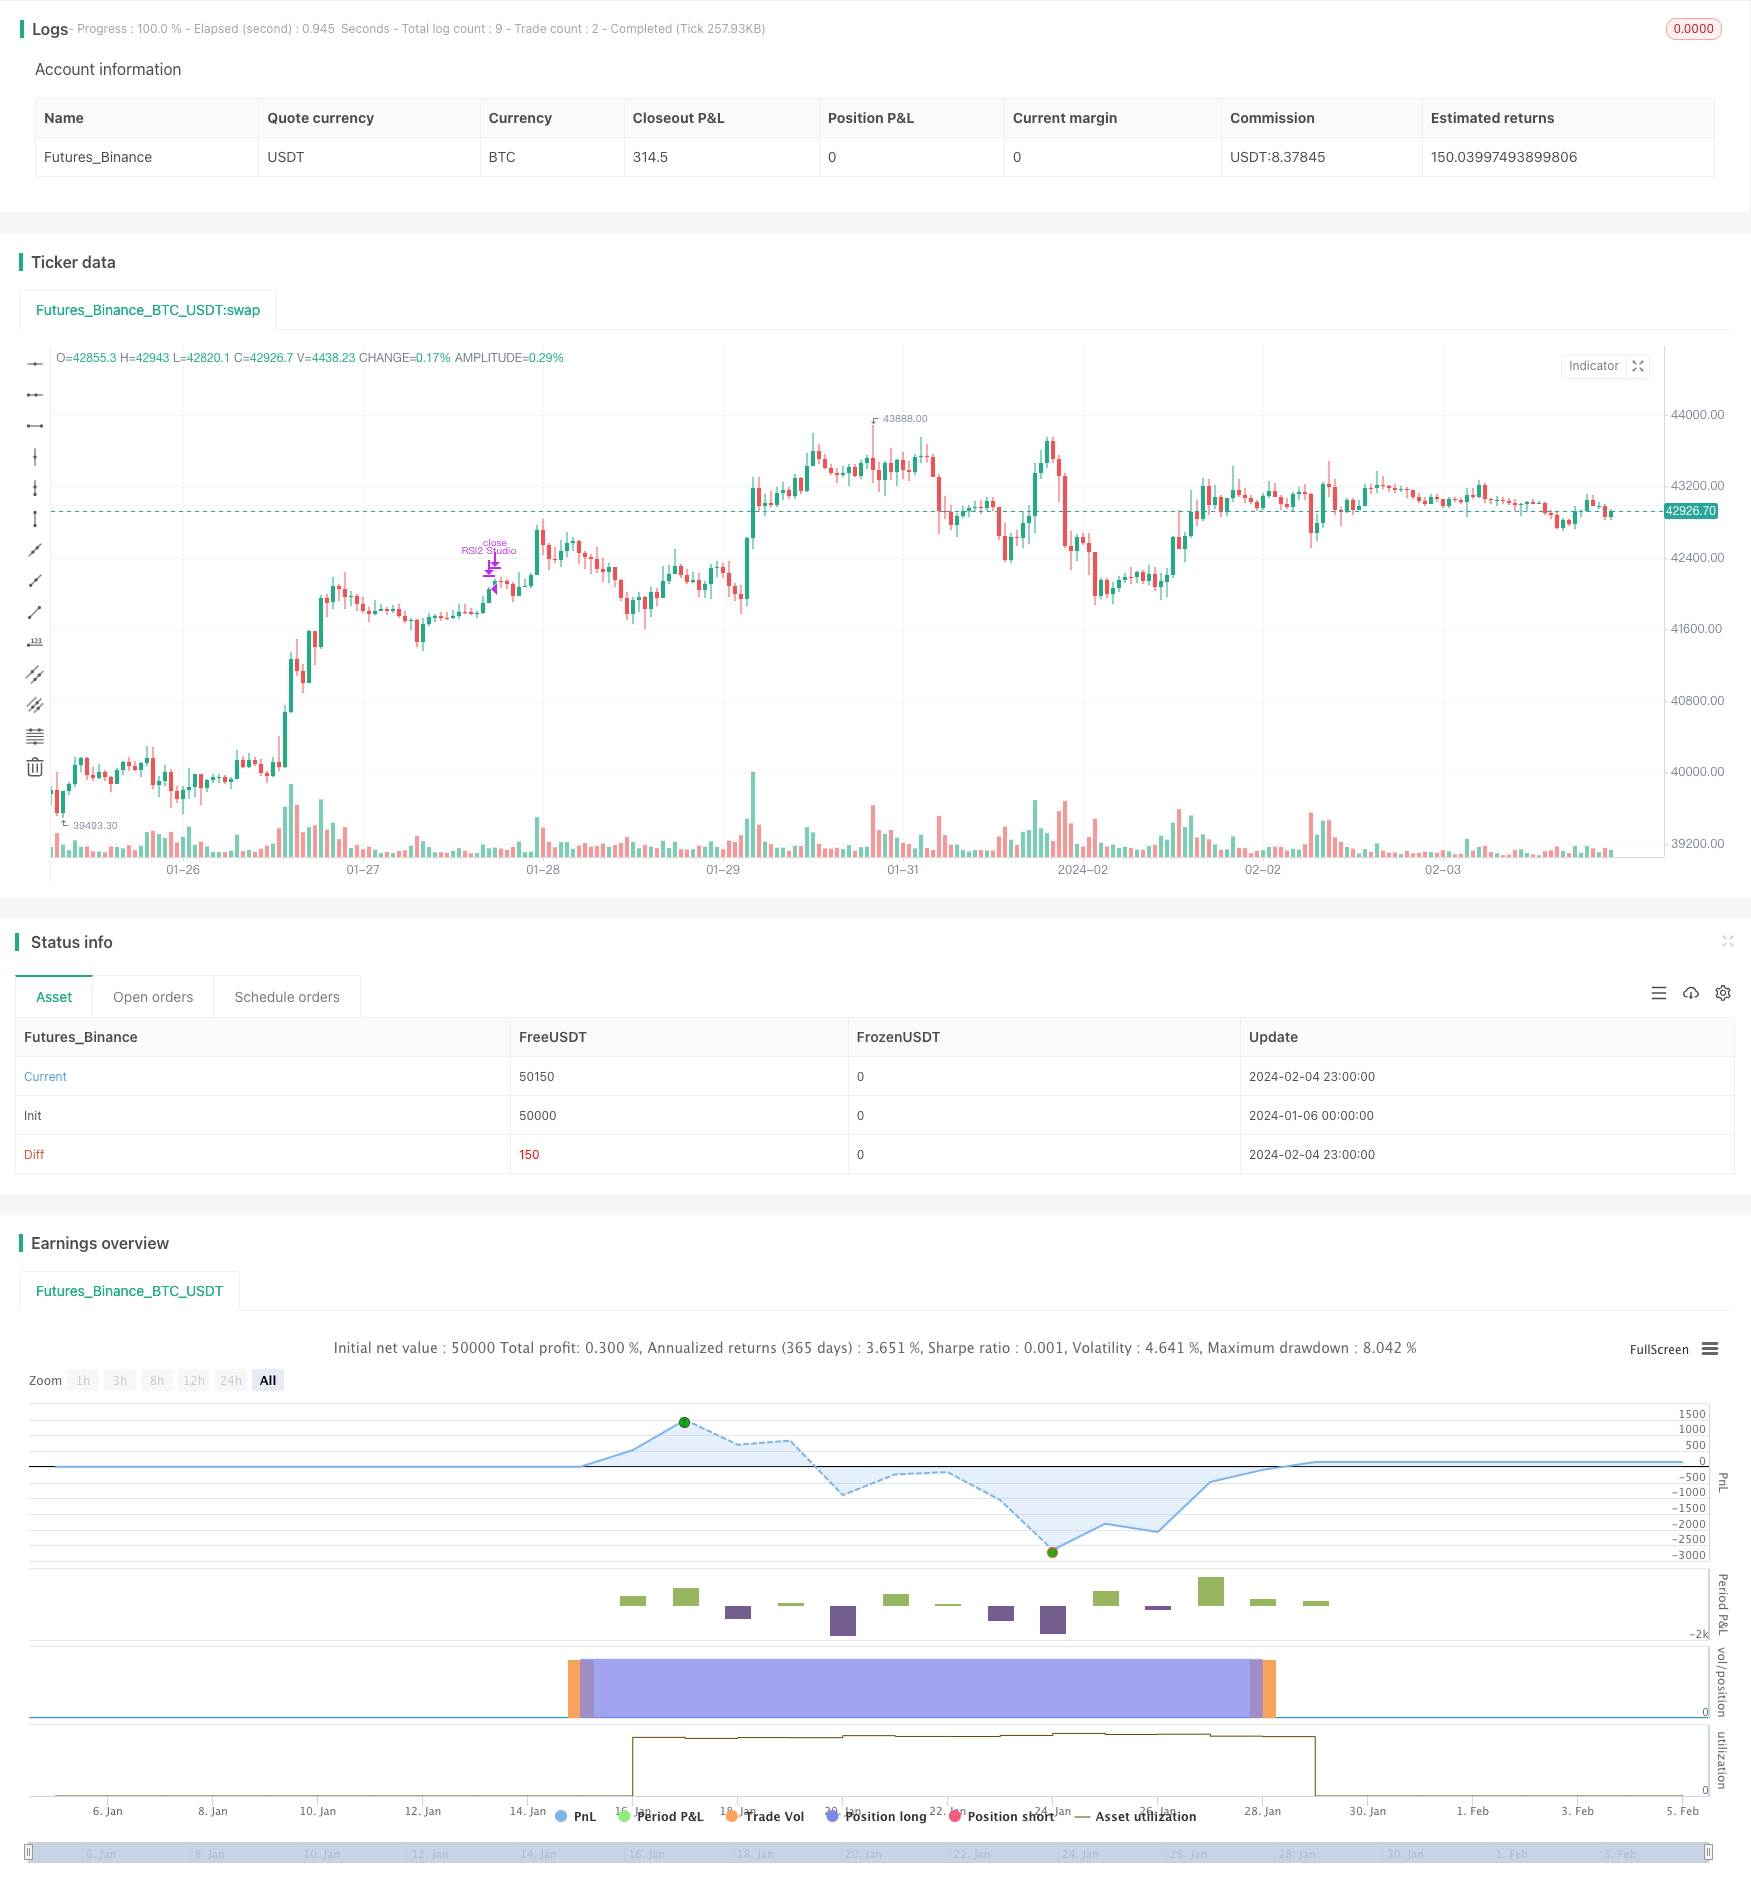
Overview
The S&P500 Advanced RSI Indicator Trading Strategy is a medium to long term trend following strategy for trading the S&P500 index. This strategy combines multiple filters with RSI overbought and oversold signals to control risk and reduce false signals.
Strategy Logic
The core indicator of this strategy is RSI, using 2 period RSI to determine price overbought and oversold levels. It goes long when RSI drops below the oversold line and closes position when RSI rises above the overbought line. In addition, the strategy has a series of auxiliary filters to control risk:
Weekly RSI Filter: Requires weekly RSI to be below a threshold to avoid overly aggressive longs in a bull market.
MA Filter: Requires price to be above a certain MA period to ensure entering after an uptrend has started.
Secondary RSI Filter: Requires the secondary RSI indicator also drops below oversold line to avoid false breakouts.
ATR Breakout Filter: Avoids going long after a sharp price drop to control risk.
The combination of these multiple filters can effectively identify medium to long term price reversal points, control trade frequency and reduce risk.
Advantage Analysis
The S&P500 Advanced RSI Indicator Trading Strategy has the following advantages:
Combining multiple auxiliary indicators reduces false signals and improves reliability.
The ATR breakout filter controls risk by avoiding buying after a price crash.
Weekly RSI filter prevents overly aggressive longs in a bull market.
MA filter ensures entering after an uptrend has started.
Secondary RSI filter avoids false RSI breakouts.
Suitable for medium to long term holding and avoids overtrading.
Risk Analysis
The main risks of this strategy come from the following aspects:
RSI as the main indicator has some lagging.
Filter conditions could be too strict and miss opportunities.
Stop loss could be taken out during flash crashes.
Simple RSI and filters have limited capabilities in complex market conditions.
Corresponding mitigations:
Adjust parameters to avoid missing trades.
Increase position sizing to account for some missed trades.
Relax filter conditions moderately to increase trade frequency.
Consider combining more indicators for complex market analysis.
Optimization Directions
The strategy can be further optimized in the following directions:
Test adjusting RSI parameters to find optimal overbought/oversold lines.
Test MA period parameters to determine optimal values.
Test adjusting ATR parameters to optimize price breakout filters.
Try combining other indicators for better analysis of complex markets.
Optimize weekly RSI parameters to find optimal settings.
Optimize secondary RSI parameters including period and overbought/oversold lines.
Conclusion
The S&P500 Advanced RSI Indicator Trading Strategy identifies medium to long term trend reversal points using RSI and multiple filter conditions to control risk. It utilizes the strengths of RSI effectively to lock in medium/long term trends and avoid overtrading. As parameters continue to be optimized, strategy performance can continue improving. Overall it is suitable for medium to long term value investing and is a relatively stable quantitative strategy.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 2 | Base RSI Length |
| v_input_2 | 10 | Overbought Level |
| v_input_3 | 90 | Oversold Level |
| v_input_4 | 70 | Overbought Level Exit |
| v_input_5 | true | Enable Weekly RSI Filter |
| v_input_6 | 30 | Weekly Oversold Level |
| v_input_7 | 70 | Weekly OverOverbought Level |
| v_input_8 | 2 | weeklyRsiLength |
| v_input_9 | false | Enable MA Filter |
| v_input_10 | 100 | WMA Length |
| v_input_11 | 4 | Exit RSI Length |
| v_input_12 | 4 | Daily RSI Length |
| v_input_13 | false | Enable 2nd RSI Filter |
| v_input_14 | 14 | 2nd RSI Filter Length |
| v_input_15 | 20 | 2nd RSI Filter Oversold Level |
| v_input_16 | true | Enable ATR Filter |
| v_input_17 | 14 | Number of Days ATR Average |
| v_input_18 | 2 | ATR Filter Factor |
Source Pine Script
/*backtest
start: 2024-01-06 00:00:00
end: 2024-02-05 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
// Lets connect on LinkedIn (https://www.linkedin.com/in/lets-grow-with-quality/)
// Optimized for S&P500 Daily. Use it as a buy confirmation on certain levels (Springs, Pullbacks, ...) or let it run
// without "Weekly RSI Filter" and pyramiding for 4 x more trades.
// This strategy is optimized for minimum drawdowns and has several filters on board for use on different securities

strategy("S&P500 RSI2 Studio", overlay=true)

baseLength = input(2, title="Base RSI Length")
overSold = input(10, title="Overbought Level")
overBought = input(90, title="Oversold Level")
overBoughtExit = input(70, title="Overbought Level Exit")
enableWeeklyRsiFilter = input(true, title="Enable Weekly RSI Filter")
weeklyOverSold = input(30, title="Weekly Oversold Level")
weeklyOverBought = input(70, title="Weekly OverOverbought Level")
weeklyRsiLength = input(2, title="weeklyRsiLength")

enableWmaFilter = input(false, title="Enable MA Filter")
wmaLength = input(100, title="WMA Length")

exitRsiLength = input(4, title="Exit RSI Length")
dailyRsiLength = input(4, title="Daily RSI Length")

enable2ndRSIFilter = input(false, title="Enable 2nd RSI Filter")
SecRSIFilterLengh = input(14, title="2nd RSI Filter Length")
SecRSIFilterOverSold = input(20, title="2nd RSI Filter Oversold Level")

enableAtrFilter = input(true, title="Enable ATR Filter")
numAtrDays = input(14, title="Number of Days ATR Average")
atrFilterFactor = input(2, title="ATR Filter Factor")

weeklyRsi = request.security(syminfo.tickerid, "W", ta.wma(ta.rsi(close, weeklyRsiLength), 1))
exitRsi = request.security(syminfo.tickerid, "D", ta.wma(ta.rsi(close, exitRsiLength), 2))
dailyRsi = request.security(syminfo.tickerid, "D", ta.wma(ta.rsi(close, dailyRsiLength), 2))
price = close

priceDropCondition = ta.atr(1) >= ta.atr(numAtrDays) * atrFilterFactor
preventEarlyEntry = not priceDropCondition

vrsi = ta.wma(ta.rsi(price, baseLength), 2)
wma = ta.wma(price, wmaLength)


buyCond1 = ta.crossunder(vrsi, overSold)
buyCond2 = enableWeeklyRsiFilter ? weeklyRsi < weeklyOverSold : true
buyCond3 = enable2ndRSIFilter ? ta.wma(ta.rsi(close, SecRSIFilterLengh),2) < SecRSIFilterOverSold : true
buyCond4 = enableWmaFilter ? price > ta.wma(close, wmaLength) : true
buyCond5 = enableAtrFilter ? preventEarlyEntry : true

buy = buyCond1 and buyCond2 and buyCond3 and buyCond4 and buyCond5

if (not na(vrsi))
    if buy
        strategy.entry("RSI2 Studio", strategy.long, comment="Long")

if (exitRsi > overBoughtExit)
strategy.close("RSI2 Studio", comment="Close Long")Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-06. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Advanced-RSI-Indicator-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Dual MA Momentum Breakout StrategyPine Script · Breakout · 1h
- Dynamic Stop Loss Strategy Adaptive to ATR FluctuationsPine Script · Breakout · 1h
- EMA and Bollinger Bands Breakout StrategyPine Script · Breakout · 1h
- MA Trendline Breakthrough StrategyPine Script · Breakout · 1d
- Momentum Breakout Moving Average StrategyPine Script · Breakout · 1d
- Momentum Breakout Trading Strategy 440964Pine Script · Breakout · 5m