Aggressive Bottom Sniping Quantitative Strategy
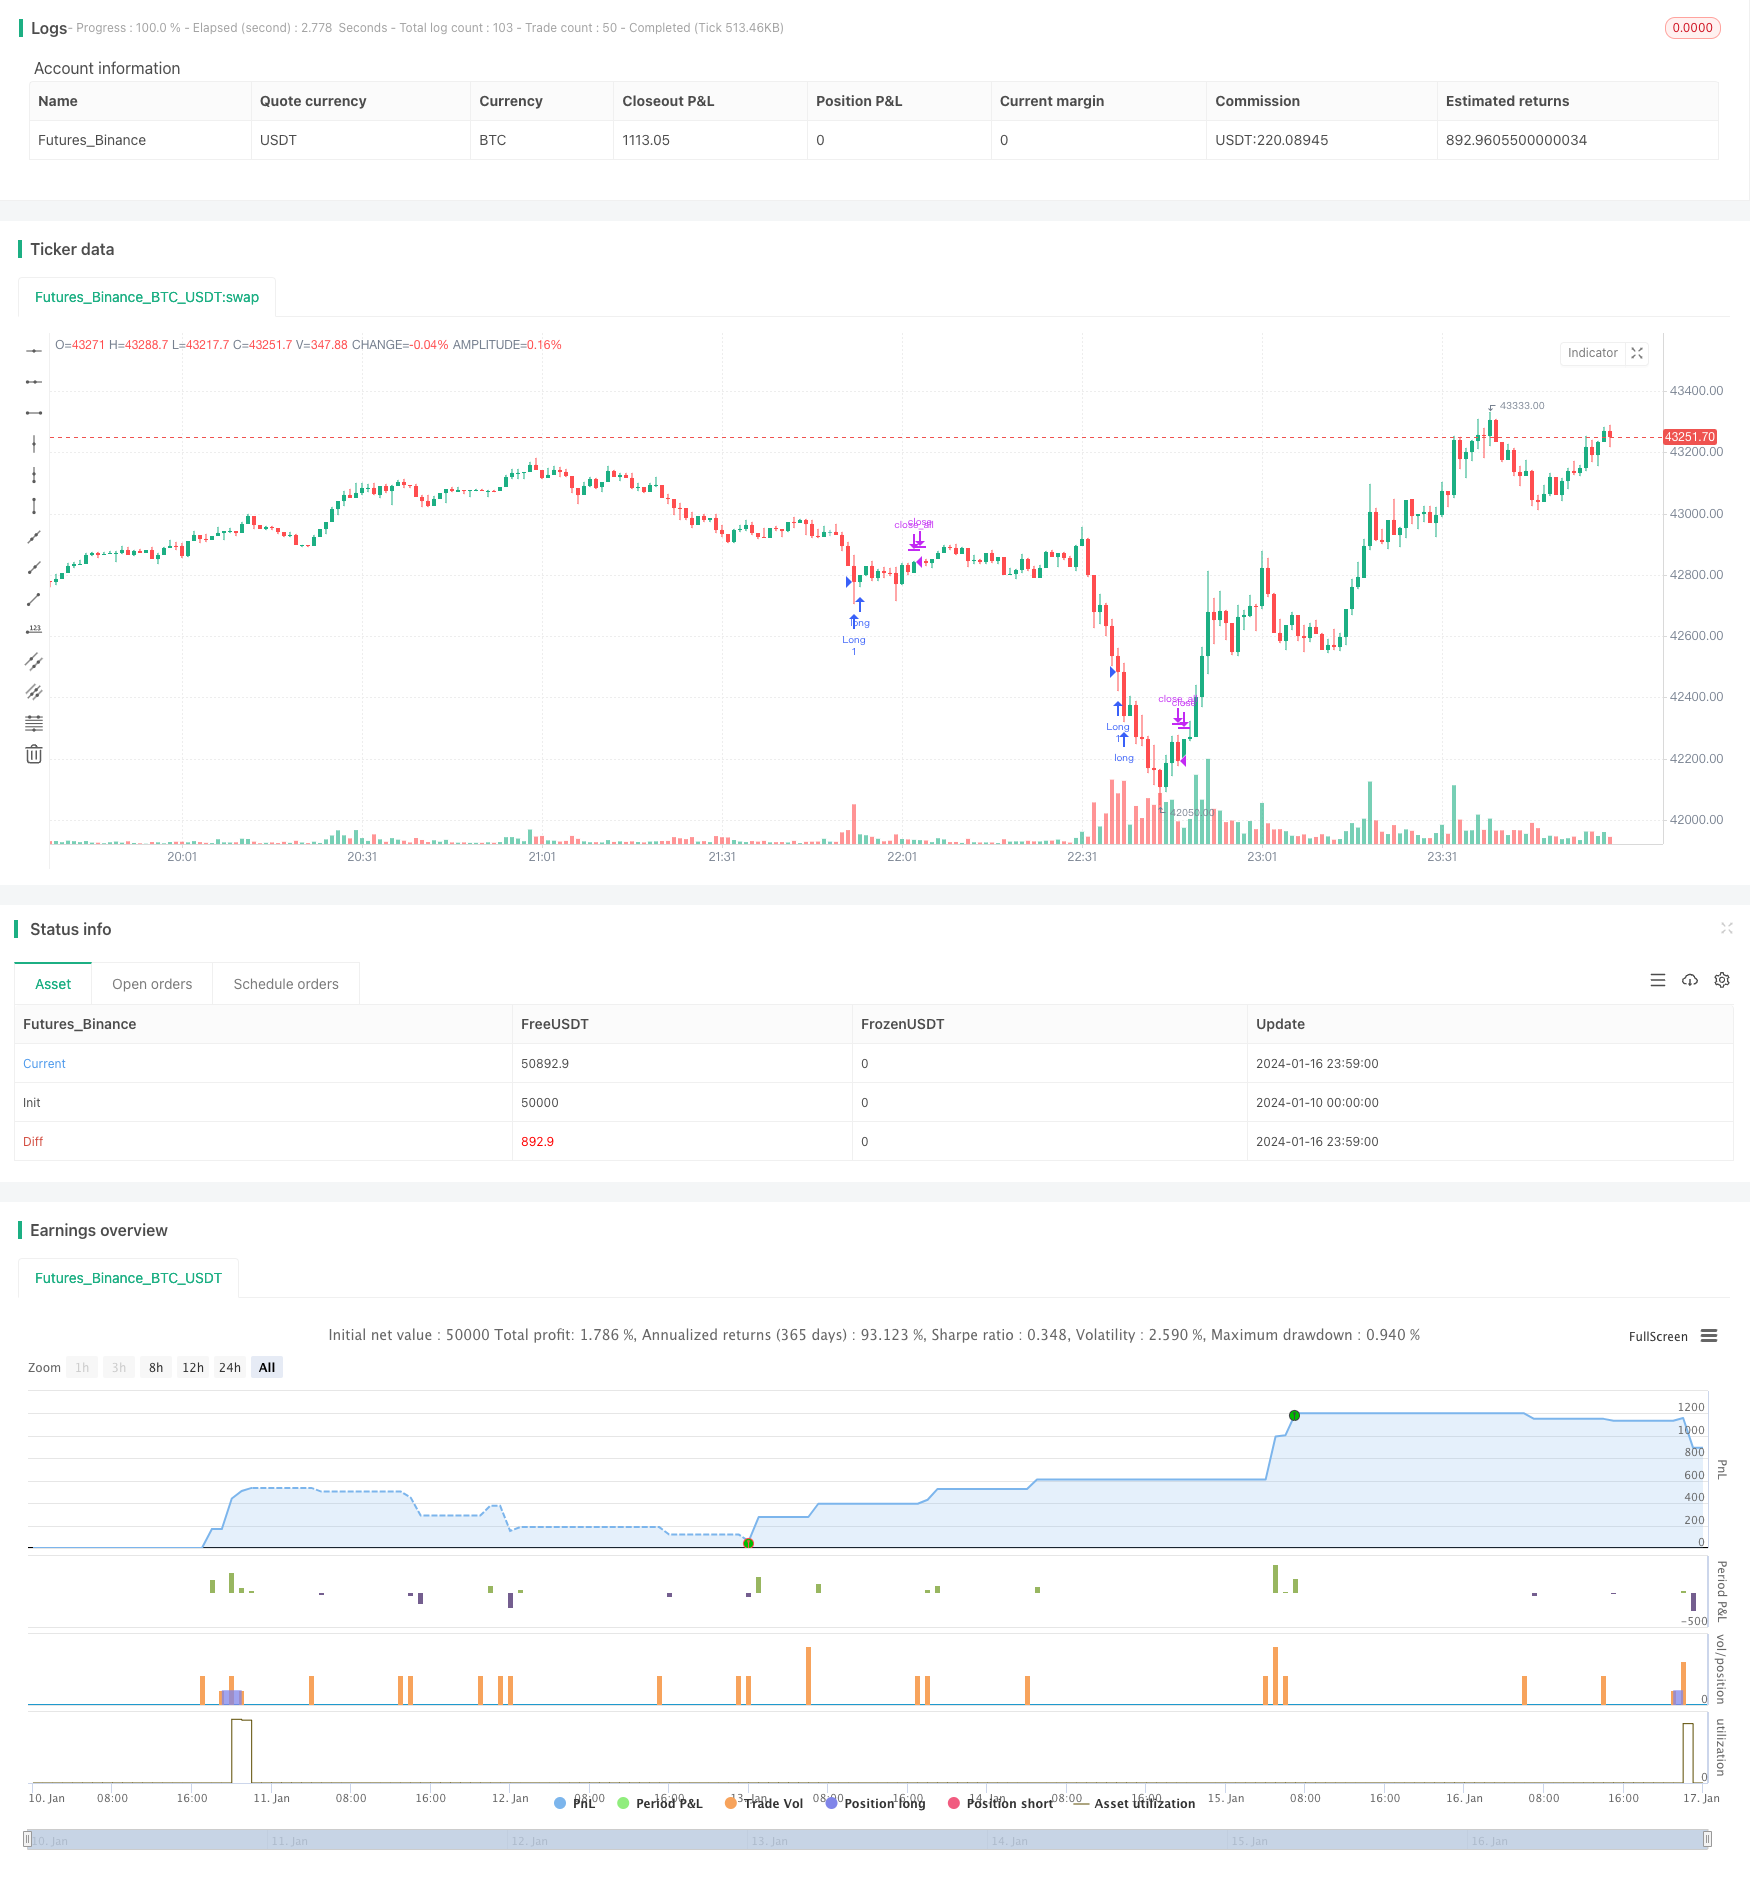
This strategy identifies short-term bottoms by detecting outstanding volume in a downtrend, and takes long positions during oversold conditions. It is an aggressive short-term trading strategy.
Overview
This strategy identifies short-term bottoms by detecting outstanding volume in a downtrend, and takes long positions during oversold conditions. It is an aggressive short-term trading strategy.
Strategy Principles
When the volume exceeds 2 standard deviations above the SMA-based average volume, it is considered outstanding volume. Meanwhile, RSI below 30 indicates oversold status. When both conditions are met, it is judged as a short-term bottom and long position is taken immediately. The position will be closed after a certain period of time (e.g. 10 bars).
So the logic of this strategy is simple:
- Calculate 20-bar SMA of volume as benchmark
- Calculate 2 standard deviation of 20-bar volume as threshold for outstanding volume
- Calculate 20-bar RSI to judge oversold status
- When volume exceeds benchmark + 2 standard deviation and RSI < 30, judge as short-term bottom
- Take long position immediately at bottom
- Close position after 10 bars automatically
Advantage Analysis
The advantages of this strategy include:
- Simple logic, easy to understand and optimize
- Utilize outstanding volume to detect short-term turning points
- RSI ensures only taking longs in oversold zone, avoiding chasing tops
- Automatic stop loss maximizes risk evasion at bottoms
In summary, this strategy takes advantage of volume breakouts to catch trend reversals, while strictly controlling risks. It is a reliable aggressive long strategy.
Risk Analysis
The main risks of this strategy include:
- Volume and RSI may generate false breakout signals, causing wrong longs and losses.
- Fixed stop loss time may fail to stop loss or stop loss too early during significant market reversal.
- Suboptimal parameter tuning may lead to too few or too many signals.
To address these risks, optimization can be done in the following aspects:
- Add other indicators to filter false breakout signals.
- Set dynamic trailing stop loss instead of fixed number of bars.
- Comprehensive parameter testing and tuning to ensure robustness.
Optimization Directions
This strategy can be further optimized in the following aspects:
- Add ML model to judge reliability of volume breakouts to avoid false signals
- Add adaptive stop loss mechanism instead of fixed bars
- Multi-dimensional dataset optimization for outstanding volume parameters
- Increase accuracy of oversold signals using ML screening
- Incorporate sentiment analysis to improve alpha
By introducing more advanced techniques, significant improvement can be achieved on stability, alpha and Sharpe ratio.
Conclusion
In summary, this is a very simple, straightforward and logical short-term breakout strategy. By properly leveraging volume to detect trend reversals, and strictly controlling risks, solid performance can be achieved. But risks of false signals and parameter robustness exist. These can be addressed incrementally by introducing more advanced techniques to further improve the strategy.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 20 | Volume SMA Length |
| v_input_2 | 2 | mult |
| v_input_3 | 20 | RSI Length |
| v_input_4 | 30 | Oversold |
| v_input_5 | 10 | Close After |
Source Pine Script
/*backtest
start: 2024-01-10 00:00:00
end: 2024-01-17 00:00:00
period: 1m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © footlz

//@version=4
strategy("Bottom catch strategy", overlay=true)

v_len = input(20, title="Volume SMA Length")
mult = input(2)
rsi_len = input(20, title="RSI Length")
oversold = input(30, title="Oversold")
close_time = input(10, title="Close After")

v = volume
basis = sma(v, v_len)
dev = mult * stdev(v, v_len)
upper_volume = basis + dev

rsi = rsi(close, rsi_len)

long = v > upper_volume and rsi < oversold

strategy.entry("Long", true, when=long)

passed_time = 0.0
if strategy.position_size != 0
    passed_time := 1
else
    passed_time := 0

if strategy.position_size != 0 and strategy.position_size[1] != 0
    passed_time := passed_time[1] + 1

if passed_time >= close_time
    strategy.close_all()

// If want to enable plot, change overlay=false.
v_color = close >= close[1] ? color.new(#3eb370, 0) : color.new(#e9546b, 0)

// plot(v, title="volume", color=v_color, style=plot.style_columns)
// plot(upper_volume, title="Threshold", color=color.aqua)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-18. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Aggressive-Bottom-Sniping-Quantitative-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bollinger Band Channel Breakout Trading StrategyPine Script · Breakout · 1d
- Bollinger Bands Dynamic Breakout StrategyPine Script · Breakout · 1h
- Bull Market Tracking SystemPine Script · Breakout · 1h
- Cross boundary Dynamic Range Quantitative Trading Strategy Based on Bollinger BandsPine Script · Breakout · 3h
- Dual MA Momentum Breakout StrategyPine Script · Breakout · 1h
- Dynamic Stop Loss Strategy Adaptive to ATR FluctuationsPine Script · Breakout · 1h