Strategy vault / Trend following
baguette by multigrain
Rationale The rationale behind this indicator is that: when the price of an asset reaches an extreme, regardless of the trend, there is a (maybe not equal but) opposite reaction. Settings The default settings will…
Rationale The rationale behind this indicator is that: when the price of an asset reaches an extreme, regardless of the trend, there is a (maybe not equal but) opposite reaction.
Settings The default settings will not be the best for whatever timeframe you choose. I personally believe a longer than 'normal' JMA Length is best.
JMA Source: The source in which the Jurik Moving Average calculations are based off of. JMA Length: Controls the length of the Jurik Moving Average. JMA Phase: A lag controller of sorts. Increasing the phase increases overshoots but reduces lag, decreasing the phase decreases overshoots but increases lag.
ATR Length: The length in which an average true range value will be calculated with. ATR Multiplier: This multiplier controls the 'width' of our envelope or our extreme bands.
Credits @gorx1 for the improved and more accurate (?) Jurik Moving Average calculations. @redktrader for the ATR envelope calculations.
backtest
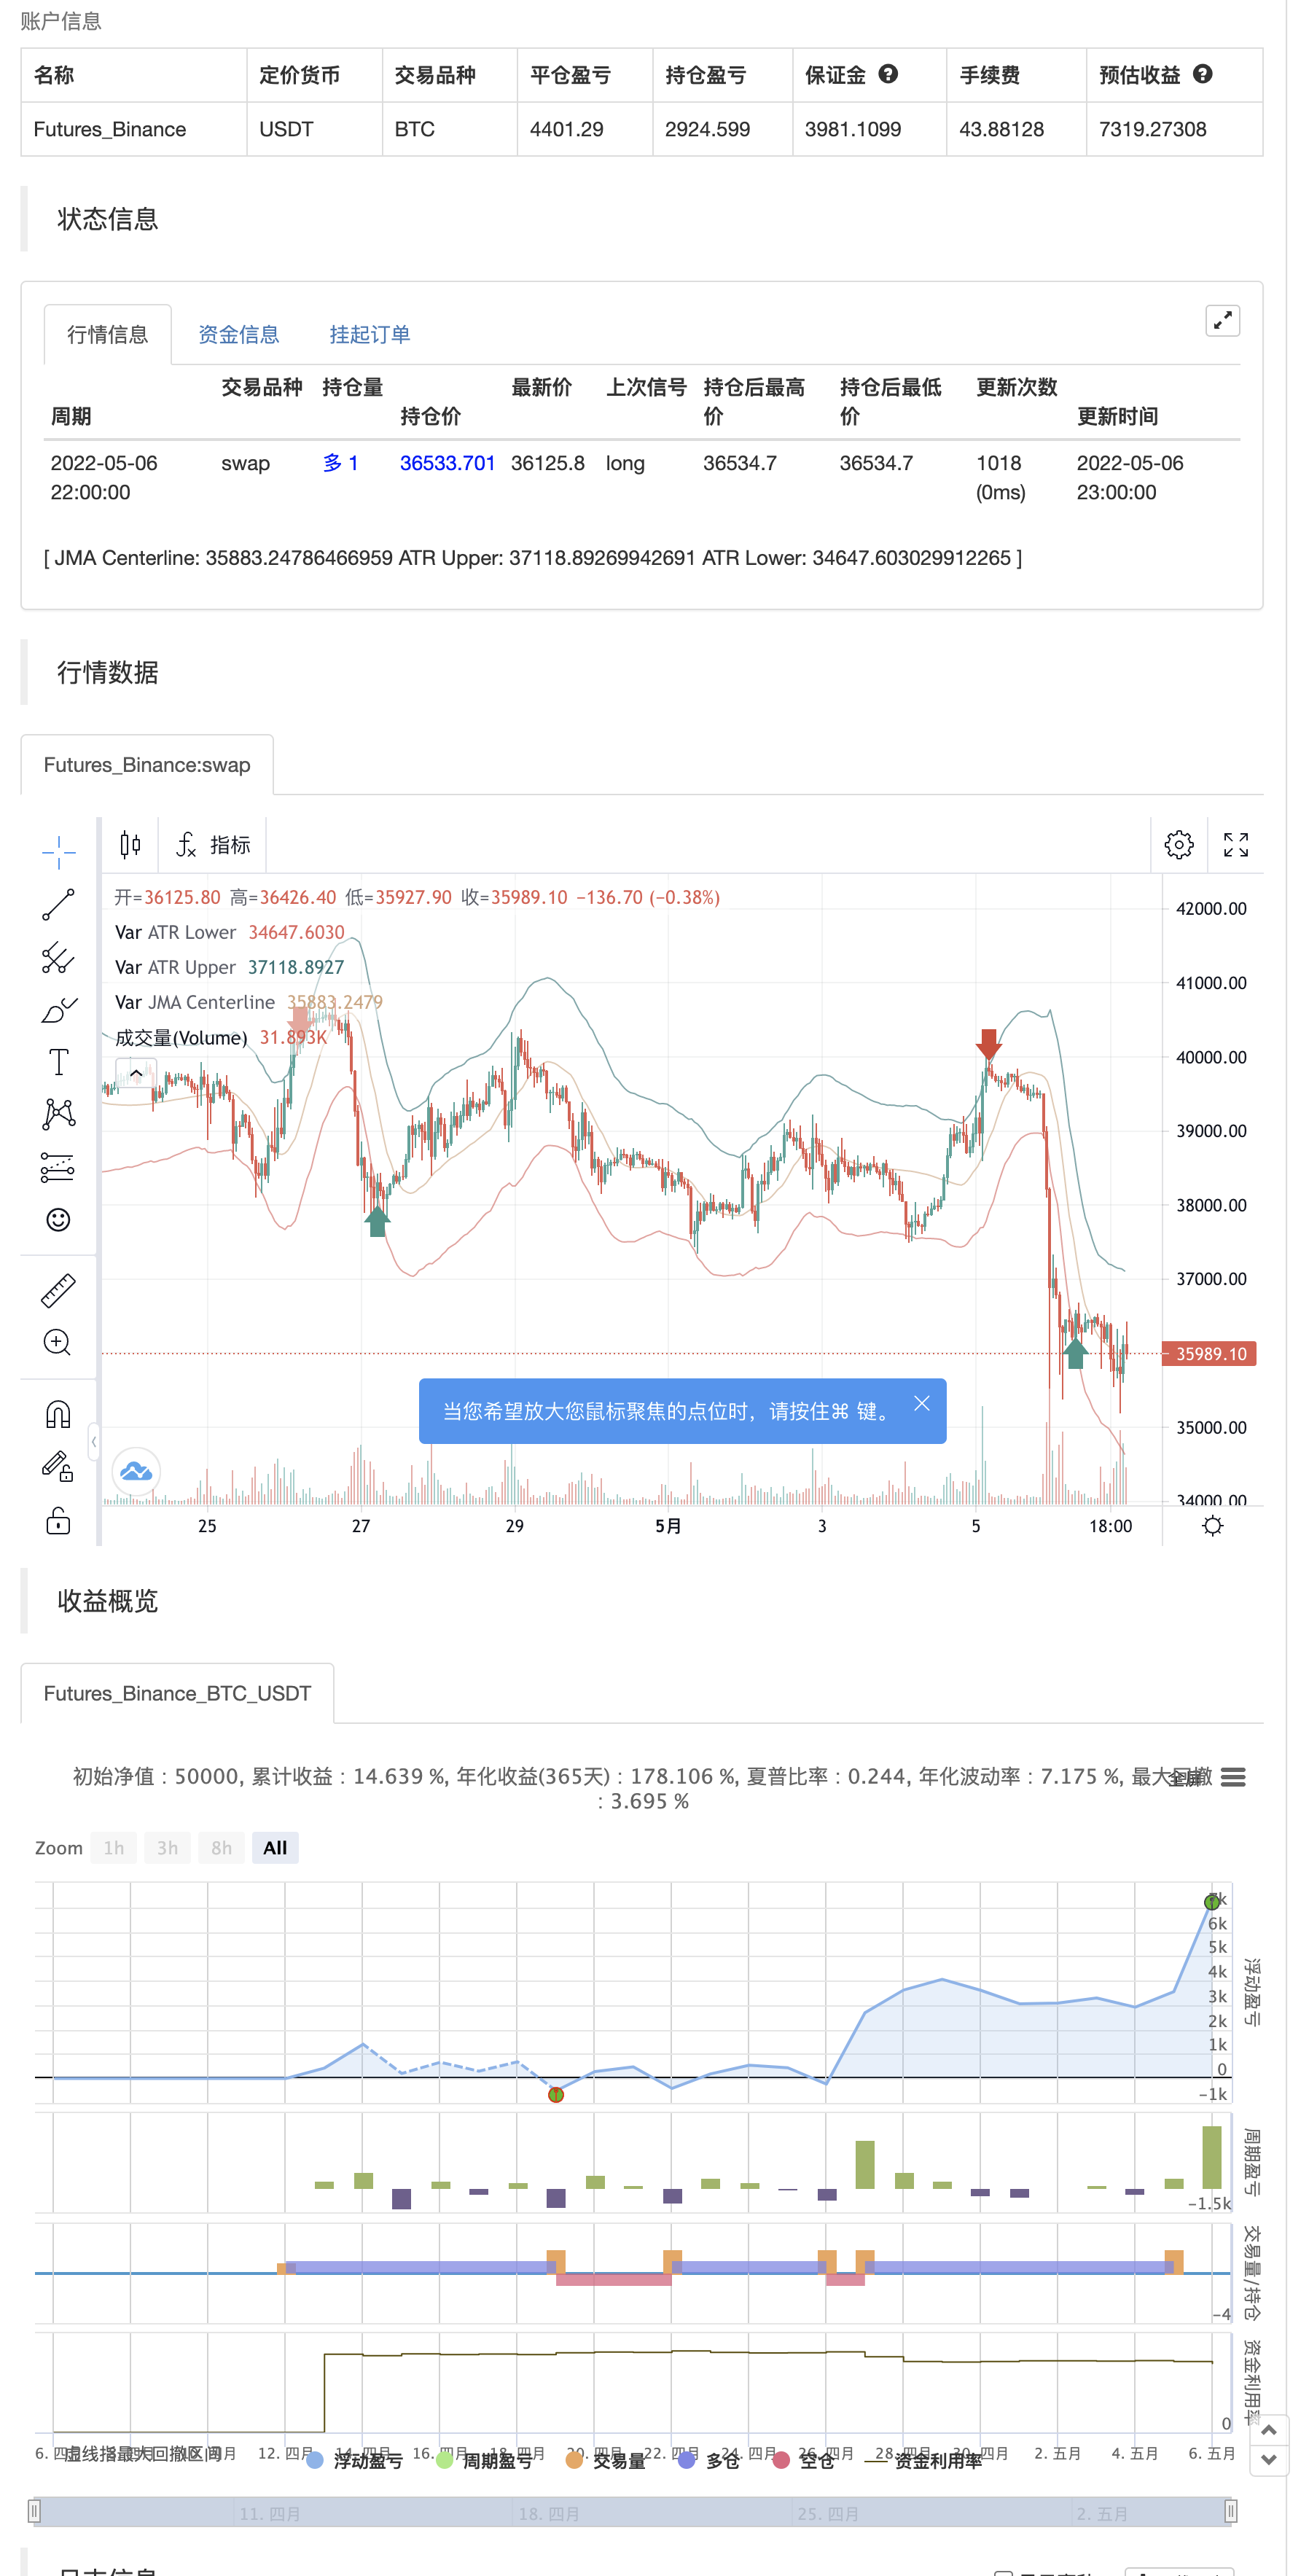
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_source_1_hlc3 | 0 | (?JMA)JMA Source: hlc3 | high | low | open | hl2 | close | hlcc4 | ohlc4 |
| v_input_int_1 | 144 | JMA Length |
| v_input_int_2 | 34 | JMA Phase |
| v_input_int_3 | 34 | (?Envelope)ATR Length |
| v_input_float_1 | 3 | ATR Multiplier |
Source Pine Script
/*backtest
start: 2022-04-07 00:00:00
end: 2022-05-06 23:59:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © multigrain
//@version=5

indicator('baguette by multigrain', 'baguette', overlay = true)
//NAME            TYPE               DEFVAL     TITLE               MIN     MAX         GROUP
jmaSrc          = input.source      (hlc3,      'JMA Source',                           group='JMA')
jmaLen          = input.int         (144,       'JMA Length',                           group='JMA')
jmaPhs          = input.int         (34,        'JMA Phase',        -100,   100,        group='JMA')


atrLen          = input.int         (34,        'ATR Length',                           group='Envelope')
atrMul          = input.float       (3,       'ATR Multiplier',                       group='Envelope')


// Jurik Moving Average
// credit to @gorx1
f_jma(_src, _length, _phase) =>
    lower_band  = _src
    upper_band  = _src
    del2        = math.abs(_src - lower_band[1])
    del1        = math.abs(_src - upper_band[1])

    vola        = del1 == del2 ? 0 : math.max(del1, del2)

    vola_sum    = 0.0
    vola_sum    := nz(vola_sum[1]) + 0.1 * (vola - vola[10])

    avg_len     = 65

    y           = bar_index + 1

    avg_vola    = 0.0
    avg_vola    := if y <= avg_len + 1
        nz(avg_vola[1]) + 2.0 * (vola_sum - nz(avg_vola[1])) / (avg_len + 1)
    else
        ta.sma(vola_sum, avg_len)

    len         = 0.5 * (_length - 1)
    len1        = math.max(math.log(math.sqrt(len)) / math.log(2) + 2, 0)
    pow1        = math.max(len1 - 2, 0.5)

    r_vola      = avg_vola > 0 ? vola / avg_vola : 0
    r_vola      := if r_vola > math.pow(len1, 1 / pow1)
        math.pow(len1, 1 / pow1)
    else if r_vola < 1
        1
    else
        r_vola

    pow2        = math.pow(r_vola, pow1)
    len2        = math.sqrt(len) * len1
    bet         = len2 / (len2 + 1)
    kv          = math.pow(bet, math.sqrt(pow2))

    lower_band  := y == 1 ? _src : del2 < 0 ? _src : _src - kv * del2
    upper_band  := y == 1 ? _src : del1 < 0 ? _src : _src + kv * del1

    beta        = 0.45 * (len - 1) / (0.45 * (len - 1) + 2)
    pr          = _phase < -100 ? 0.5 : _phase > 100 ? 2.5 : _phase / 100 + 1.5
    alpha       = math.pow(beta, pow2)

    ma1         = 0.0
    det0        = 0.0
    jma         = 0.0
    det1        = 0.0

    ma1         := (1 - alpha) * _src + alpha * nz(ma1[1])
    det0        := (_src - ma1) * (1 - beta) + beta * nz(det0[1])
    ma2         = ma1 + pr * det0
    det1        := (ma2 - nz(jma[1])) * math.pow(1 - alpha, 2) + math.pow(alpha, 2) * nz(det1[1])
    jma         := nz(jma[1]) + det1
    jma


// Jurik Moving Average Envelope
// credit to @redktrader
f_atrEnv(_src, _length, _multiplier) =>
    atr         = ta.atr(_length) * _multiplier
    atr_us      = atr
    atr_ls      = atr
    atr_us      := ta.change(_src) != 0 ? atr : atr_us[1]
    atr_ls      := ta.change(_src) != 0 ? atr : atr_ls[1]
    atr_upper   = _src + atr_us
    atr_lower   = _src - atr_ls
    [atr_upper, atr_lower]


// Calculations
j               = f_jma(jmaSrc, jmaLen, jmaPhs)
[j_up, j_low]   = f_atrEnv(j, atrLen, atrMul)
long            = ta.crossover(hlc3, j_low) ? close : na
short           = ta.crossunder(hlc3, j_up) ? close : na

// Colors
green           = #0F7173
red             = #F05D5E
tan             = #D8A47F
white           = #FFFFFF

// Plots
plot            (j,         'JMA Centerline', tan, display=display.none)
plot            (j_up,      'ATR Upper', green)
plot            (j_low,     'ATR Lower', red)
// Alerts
if long
    strategy.entry("Enter Long", strategy.long)
else if short
strategy.entry("Enter Short", strategy.short)Published by ChaoZhang on the FMZ strategy square · last modified 2022-05-09. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/baguette-by-multigrain.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- Adaptive Risk Management Strategy Based on Dynamic ATR and Moving Average CrossoverPine Script · Trend following · 2h
- Adaptive Volatility Based Trend Following Short Strategy with Time Delay and Stop Loss ProtectionPine Script · Trend following · 2m
- BB Percentage Index Trend Fading StrategyPine Script · Trend following · 1h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m