Strategy vault / Trend following
Dual ATR Channel Trend Following Strategy
The Dual ATR Channel trend following strategy is a trend tracking strategy that combines moving averages, ATR channels and multiple technical indicators to follow the trend after it has been established.
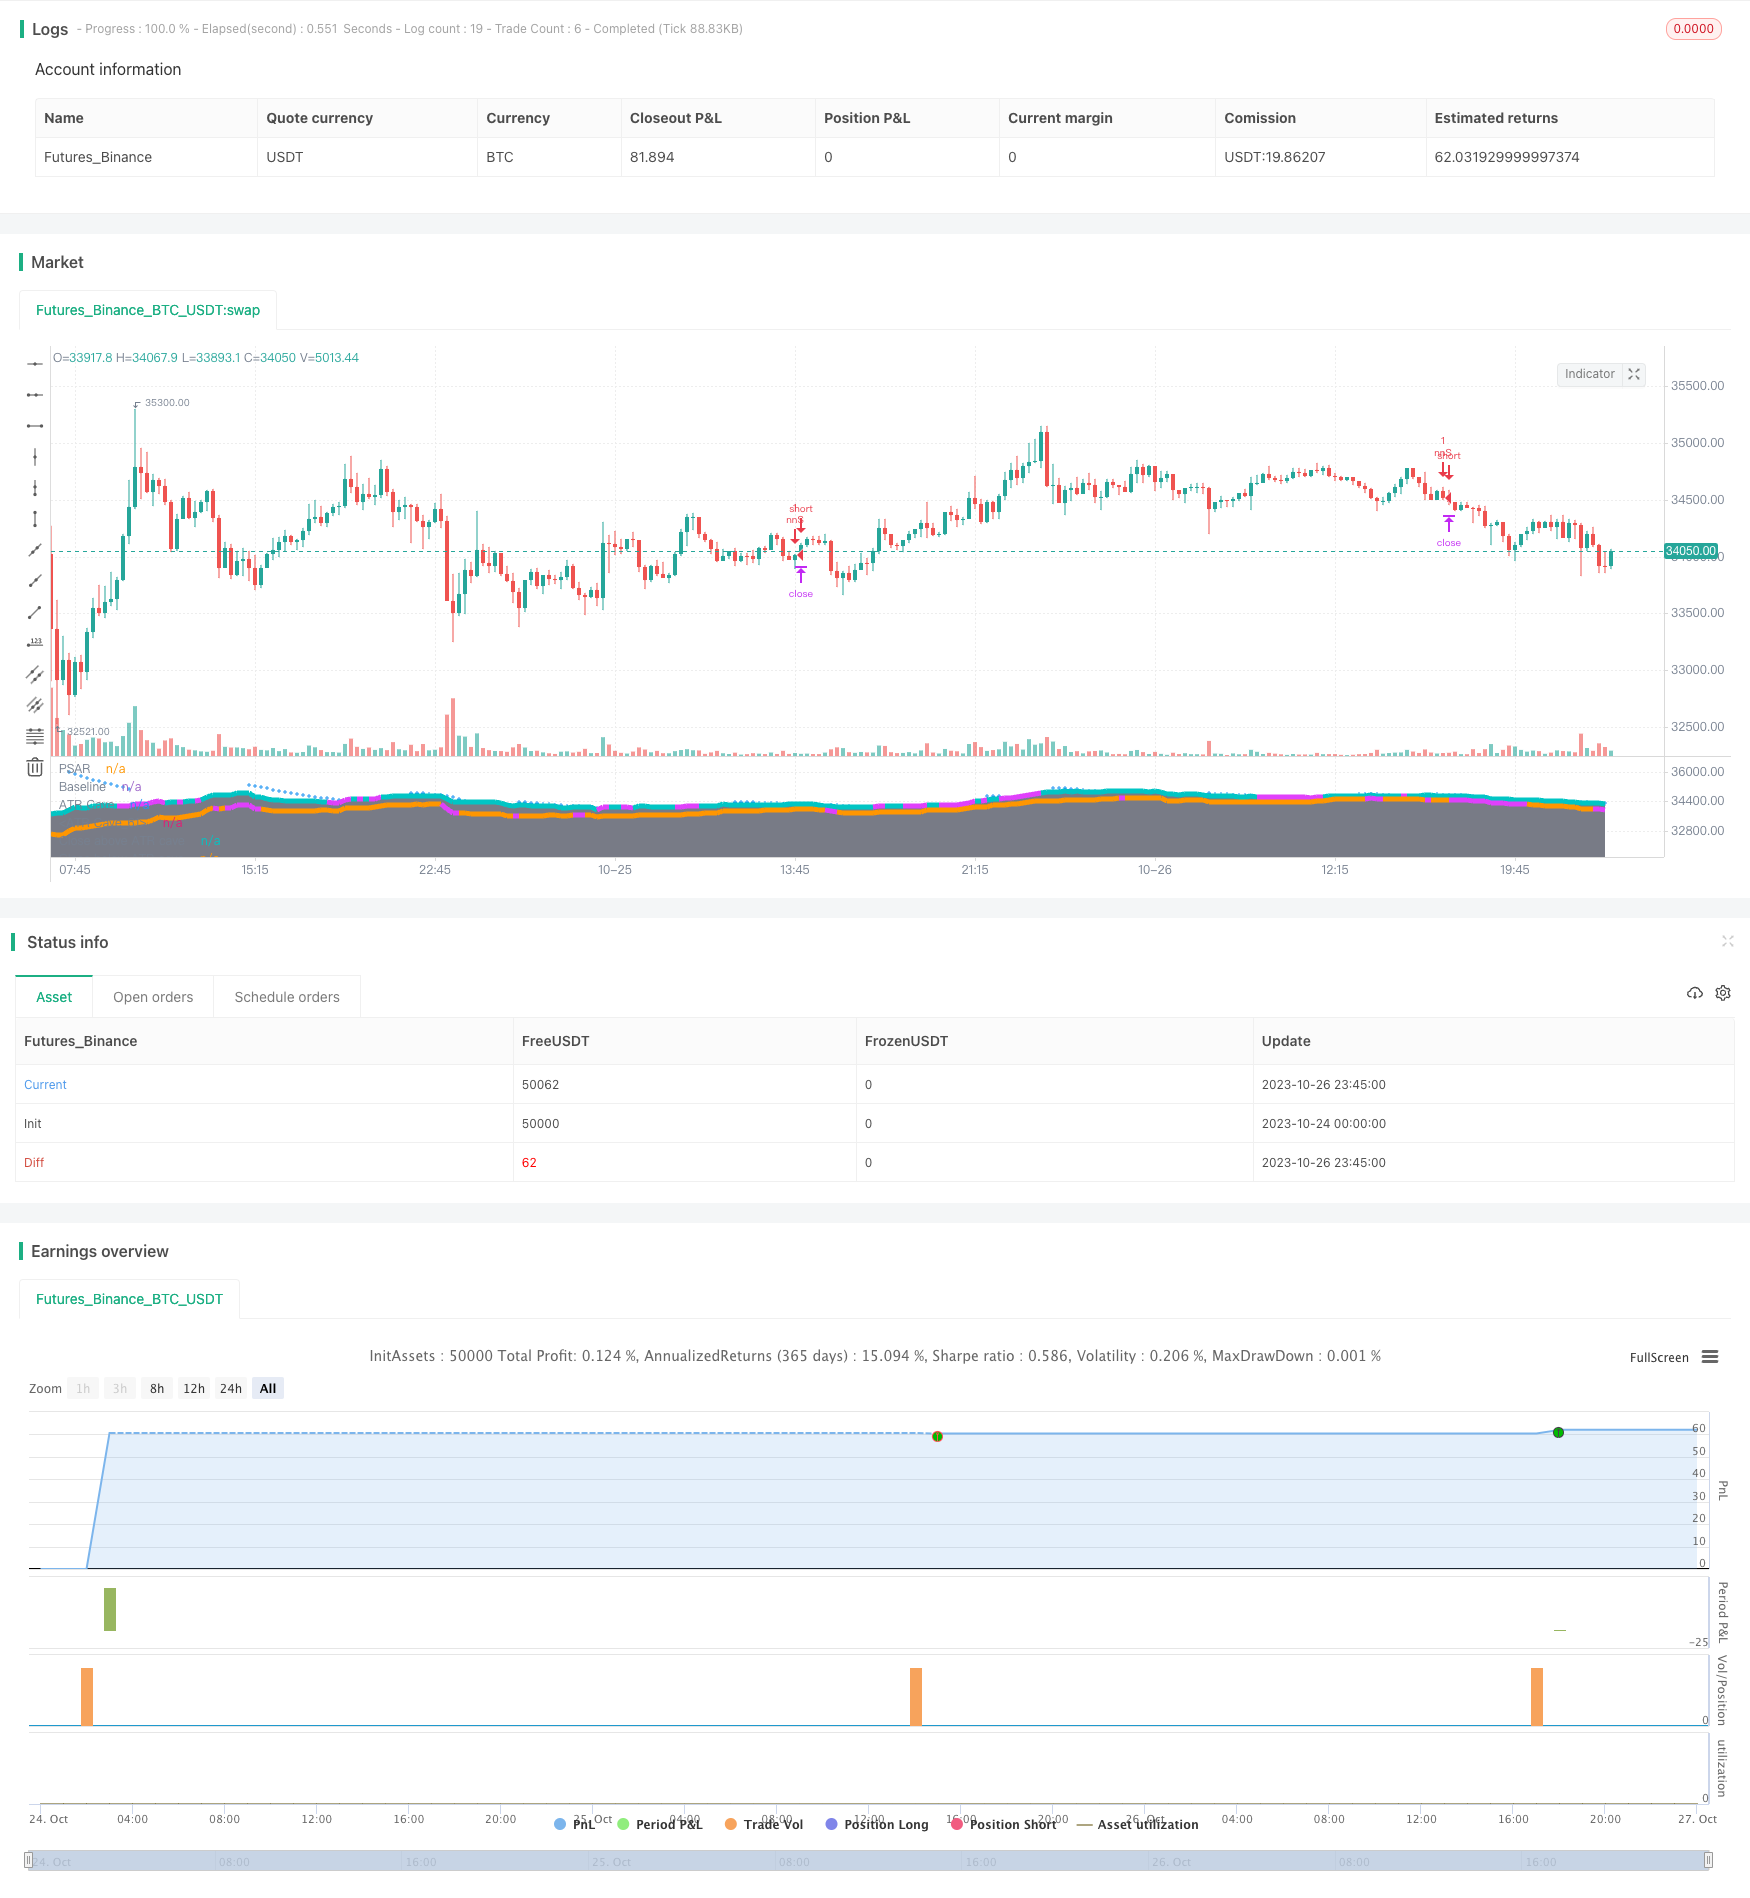
Overview
The Dual ATR Channel trend following strategy is a trend tracking strategy that combines moving averages, ATR channels and multiple technical indicators to follow the trend after it has been established.
How It Works
The strategy uses the Kijun line as the main moving average indicator to determine the trend direction. It also incorporates ATR channels to limit the price activity range - not going long when price is near the upper band and not going short when price is near the lower band to avoid chasing new highs and selling lows.
When the Kijun line has an upward crossover, a buy signal is generated. When a downward crossover happens, a sell signal is triggered. To filter out false signals, the strategy also employs multiple technical indicators for confirmation, including Aroon, RSI, MACD and PSAR. A buy or sell signal is only triggered when all the confirmation conditions are met.
Once in a trade, the strategy uses stop loss and take profit to manage positions. The stop loss is set at 0.5 ATR and take profit at 0.5%. When the price crosses the Kijun line in the opposite direction again, the position will be closed immediately.
Advantages
- Using Kijun line to determine trend avoids being whipsawed by range-bound markets
- ATR channels limit price activity for better risk control
- Multiple confirmations greatly reduce false signals
- Incorporating stop loss and take profit locks in profits while managing risks
Risks
- Delayed signals from multiple confirmations, possibly missing early trend moves
- Small stop loss may get stopped out frequently
- Poor Kijun and ATR parameters may generate many wrong signals
- Reliance on parameter optimization and curve fitting, may not work well in live trading
Improvement Opportunities
- Test more advanced trend indicators like Ichimoku clouds
- Optimize stop loss and take profit points for better risk reward ratio
- Find optimal parameters for different markets
- Add dynamic adjustment of parameters based on live market conditions
- Test different combinations of confirmation indicators
- Continuously optimize to ensure robustness of strategy
Conclusion
The dual ATR channel trend following strategy combines moving averages, ATR channels and multiple technical indicators to trade in the direction of the trend once established. Compared to single indicator strategies, it can greatly improve signal quality and win rate. The stop loss and take profit mechanisms also control risk. Through parameter optimization and combinatorial testing, this strategy has the potential to achieve steady profits. But its reliance on historical data is a concern and live performance requires further verification. Continuous optimization is key to ensuring robustness.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 0 | Baseline Type: Kijun | EMA | DEMA | TEMA | WMA | VWMA | SMA | SMMA | HMA | LSMA | ALMA | McGinley |
| v_input_2 | 20 | Baseline Length |
| v_input_3 | 12 | Baseline Length Fast |
| v_input_4 | false | * Least Squares (LSMA) Only - Offset Value |
| v_input_5 | 0.85 | * Arnaud Legoux (ALMA) Only - Offset Value |
| v_input_6 | 6 | * Arnaud Legoux (ALMA) Only - Sigma Value |
| v_input_7 | 14 | ATR Length |
| v_input_8 | true | donttradeoutside_atrcave |
| v_input_9 | 8 | Length Aroon |
| v_input_10 | false | dont_use_macd |
| v_input_11 | 13 | Fast Length |
| v_input_12 | 26 | Slow Length |
| v_input_13 | 9 | Signal Smoothing |
| v_input_14 | false | dont_use_rsi |
| v_input_15 | 14 | RSI Length |
| v_input_16 | false | dont_use_psar |
| v_input_17 | 0.03 | psar_start |
| v_input_18 | 0.018 | psar_increment |
| v_input_19 | 0.11 | psar_maximum |
| v_input_20 | false | use_exit |
| v_input_21 | 0.5 | SL |
| v_input_22 | 0.005 | TP |
Source Pine Script
/*backtest
start: 2023-10-24 00:00:00
end: 2023-10-27 00:00:00
period: 15m
basePeriod: 5m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
// strategy(title="NoNonsense Forex", overlay=true, default_qty_value=100000, initial_capital=100)

//////////////////////
////// BASELINE //////
//////////////////////
ma_slow_type = input(title="Baseline Type", type=input.string, defval="Kijun", options=["ALMA", "EMA", "DEMA", "TEMA", "WMA", "VWMA", "SMA", "SMMA", "HMA", "LSMA", "Kijun", "McGinley"])
ma_slow_src = close //input(title="MA Source", type=input.source, defval=close)
ma_slow_len = input(title="Baseline Length", type=input.integer, defval=20)
ma_slow_len_fast = input(title="Baseline Length Fast", type=input.integer, defval=12)

lsma_offset  = input(defval=0, title="* Least Squares (LSMA) Only - Offset Value", minval=0)
alma_offset  = input(defval=0.85, title="* Arnaud Legoux (ALMA) Only - Offset Value", minval=0, step=0.01)
alma_sigma   = input(defval=6, title="* Arnaud Legoux (ALMA) Only - Sigma Value", minval=0)

ma(type, src, len) =>
    float result = 0
    if type=="SMA" // Simple
        result := sma(src, len)
    if type=="EMA" // Exponential
        result := ema(src, len)
    if type=="DEMA" // Double Exponential
        e = ema(src, len)
        result := 2 * e - ema(e, len)
    if type=="TEMA" // Triple Exponential
        e = ema(src, len)
        result := 3 * (e - ema(e, len)) + ema(ema(e, len), len)
    if type=="WMA" // Weighted
        result := wma(src, len)
    if type=="VWMA" // Volume Weighted
        result := vwma(src, len)
    if type=="SMMA" // Smoothed
        w = wma(src, len)
        result := na(w[1]) ? sma(src, len) : (w[1] * (len - 1) + src) / len
    if type=="HMA" // Hull
        result := wma(2 * wma(src, len / 2) - wma(src, len), round(sqrt(len)))
    if type=="LSMA" // Least Squares
        result := linreg(src, len, lsma_offset)
    if type=="ALMA" // Arnaud Legoux
        result := alma(src, len, alma_offset, alma_sigma)
    if type=="Kijun" //Kijun-sen
        kijun = avg(lowest(len), highest(len))
        result :=kijun
    if type=="McGinley"
        mg = 0.0
        mg := na(mg[1]) ? ema(src, len) : mg[1] + (src - mg[1]) / (len * pow(src/mg[1], 4))
        result :=mg
    result

baseline = ma(ma_slow_type, ma_slow_src, ma_slow_len)
plot(baseline, title='Baseline', color=rising(baseline,1) ? color.green : falling(baseline,1) ? color.maroon : na, linewidth=3)

//////////////////
////// ATR ///////
//////////////////
atrlength=input(14, title="ATR Length")
one_atr=rma(tr(true), atrlength)
upper_atr_band=baseline+one_atr
lower_atr_band=baseline-one_atr
plot(upper_atr_band, color=color.gray, style=plot.style_areabr, transp=95, histbase=50000, title='ATR Cave')
plot(lower_atr_band, color=color.gray, style=plot.style_areabr, transp=95, histbase=0, title='ATR Cave')
plot(upper_atr_band, color=close>upper_atr_band ? color.fuchsia : na, style=plot.style_line, linewidth=5, transp=50, title='Close above ATR cave')
plot(lower_atr_band, color=close<lower_atr_band ? color.fuchsia : na, style=plot.style_line, linewidth=5, transp=50, title='Close below ATR cave')
donttradeoutside_atrcave=input(true)
too_high = close>upper_atr_band and donttradeoutside_atrcave
too_low = close<lower_atr_band and donttradeoutside_atrcave

////////////////////////////
////// CONFIRMATION 1 ////// the trigger actually
////////////////////////////
lenaroon = input(8, minval=1, title="Length Aroon")
c1upper = 100 * (highestbars(high, lenaroon+1) + lenaroon)/lenaroon
c1lower = 100 * (lowestbars(low, lenaroon+1) + lenaroon)/lenaroon
c1CrossUp=crossover(c1upper,c1lower)
c1CrossDown=crossunder(c1upper,c1lower)


////////////////////////////////
////// CONFIRMATION: MACD //////
////////////////////////////////
dont_use_macd=input(false)
macd_fast_length = input(title="Fast Length", type=input.integer, defval=13)
macd_slow_length = input(title="Slow Length", type=input.integer, defval=26)
macd_signal_length = input(title="Signal Smoothing", type=input.integer, minval = 1, maxval = 50, defval = 9)
macd_fast_ma = ema(close, macd_fast_length)
macd_slow_ma = ema(close, macd_slow_length)
macd = macd_fast_ma - macd_slow_ma
macd_signal = ema(macd, macd_signal_length)
macd_hist = macd - macd_signal

macdLong=macd_hist>0 or dont_use_macd
macdShort=macd_hist<0 or dont_use_macd

/////////////////////////////
///// CONFIRMATION: RSI /////
/////////////////////////////
dont_use_rsi=input(false)
lenrsi = input(14, minval=1, title="RSI Length") //14
up = rma(max(change(close), 0), lenrsi)
down = rma(-min(change(close), 0), lenrsi)
rsi = down == 0 ? 100 : up == 0 ? 0 : 100 - (100 / (1 + up / down))
rsiLong=rsi>50 or dont_use_rsi
rsiShort=rsi<50 or dont_use_rsi

//////////////////////////////
///// CONFIRMATION: PSAR /////
//////////////////////////////
dont_use_psar=input(false)
psar_start = input(0.03, step=0.01)
psar_increment = input(0.018, step=0.001)
psar_maximum = input(0.11, step=0.01) //default 0.08
psar = sar(psar_start, psar_increment, psar_maximum)

plot(psar, style=plot.style_cross, color=color.blue, title='PSAR')
psarLong=close>psar or dont_use_psar
psarShort=close<psar or dont_use_psar

/////////////////////////
///// CONFIRMATIONS /////
/////////////////////////
Long_Confirmations=psarLong and rsiLong and macdLong
Short_Confirmations=psarShort and rsiShort and macdShort

GoLong=c1CrossUp and Long_Confirmations and not too_high
GoShort=c1CrossDown and Short_Confirmations and not too_low

////////////////////
///// STRATEGY /////
////////////////////

use_exit=input(false)
KillLong=c1CrossDown and use_exit
KillShort=c1CrossUp and use_exit

SL=input(0.5, step=0.1)/syminfo.mintick
TP=input(0.005, step=0.001)/syminfo.mintick

strategy.entry("nnL", strategy.long, when = GoLong)
strategy.entry("nnS", strategy.short, when = GoShort)
strategy.exit("XL-nn", from_entry = "nnL", loss = SL, profit=TP)
strategy.exit("XS-nn", from_entry = "nnS", loss = SL, profit=TP)
strategy.close("nnL", when = KillLong)
strategy.close("nnS", when = KillShort)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-01. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-ATR-Channel-Trend-Following-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Indicator Verification Automated Trading StrategyPine Script · Trend following · 10m
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dynamic Dual EMA Crossover Strategy with Adaptive Profit Loss ControlPine Script · Trend following · 1d
- EMA and RSI Trend Trading StrategyPine Script · Trend following · 1d
- Fixed Range Volume Profile And Anchored VWAP Trend Identification Strategy With Dynamic Stop LossPine Script · Trend following · 1h
- Multi Moving Average Trend Capture and Crossover Confirmation Trading SystemPine Script · Trend following · 1m