Strategy vault / Trend following
Bandpass Filtering Trend Extraction Strategy
The Bandpass Filtering Trend Extraction Strategy is a stock trend tracking strategy based on bandpass filters. It uses an exponentially weighted moving average and bandpass filtering to process the price series and…
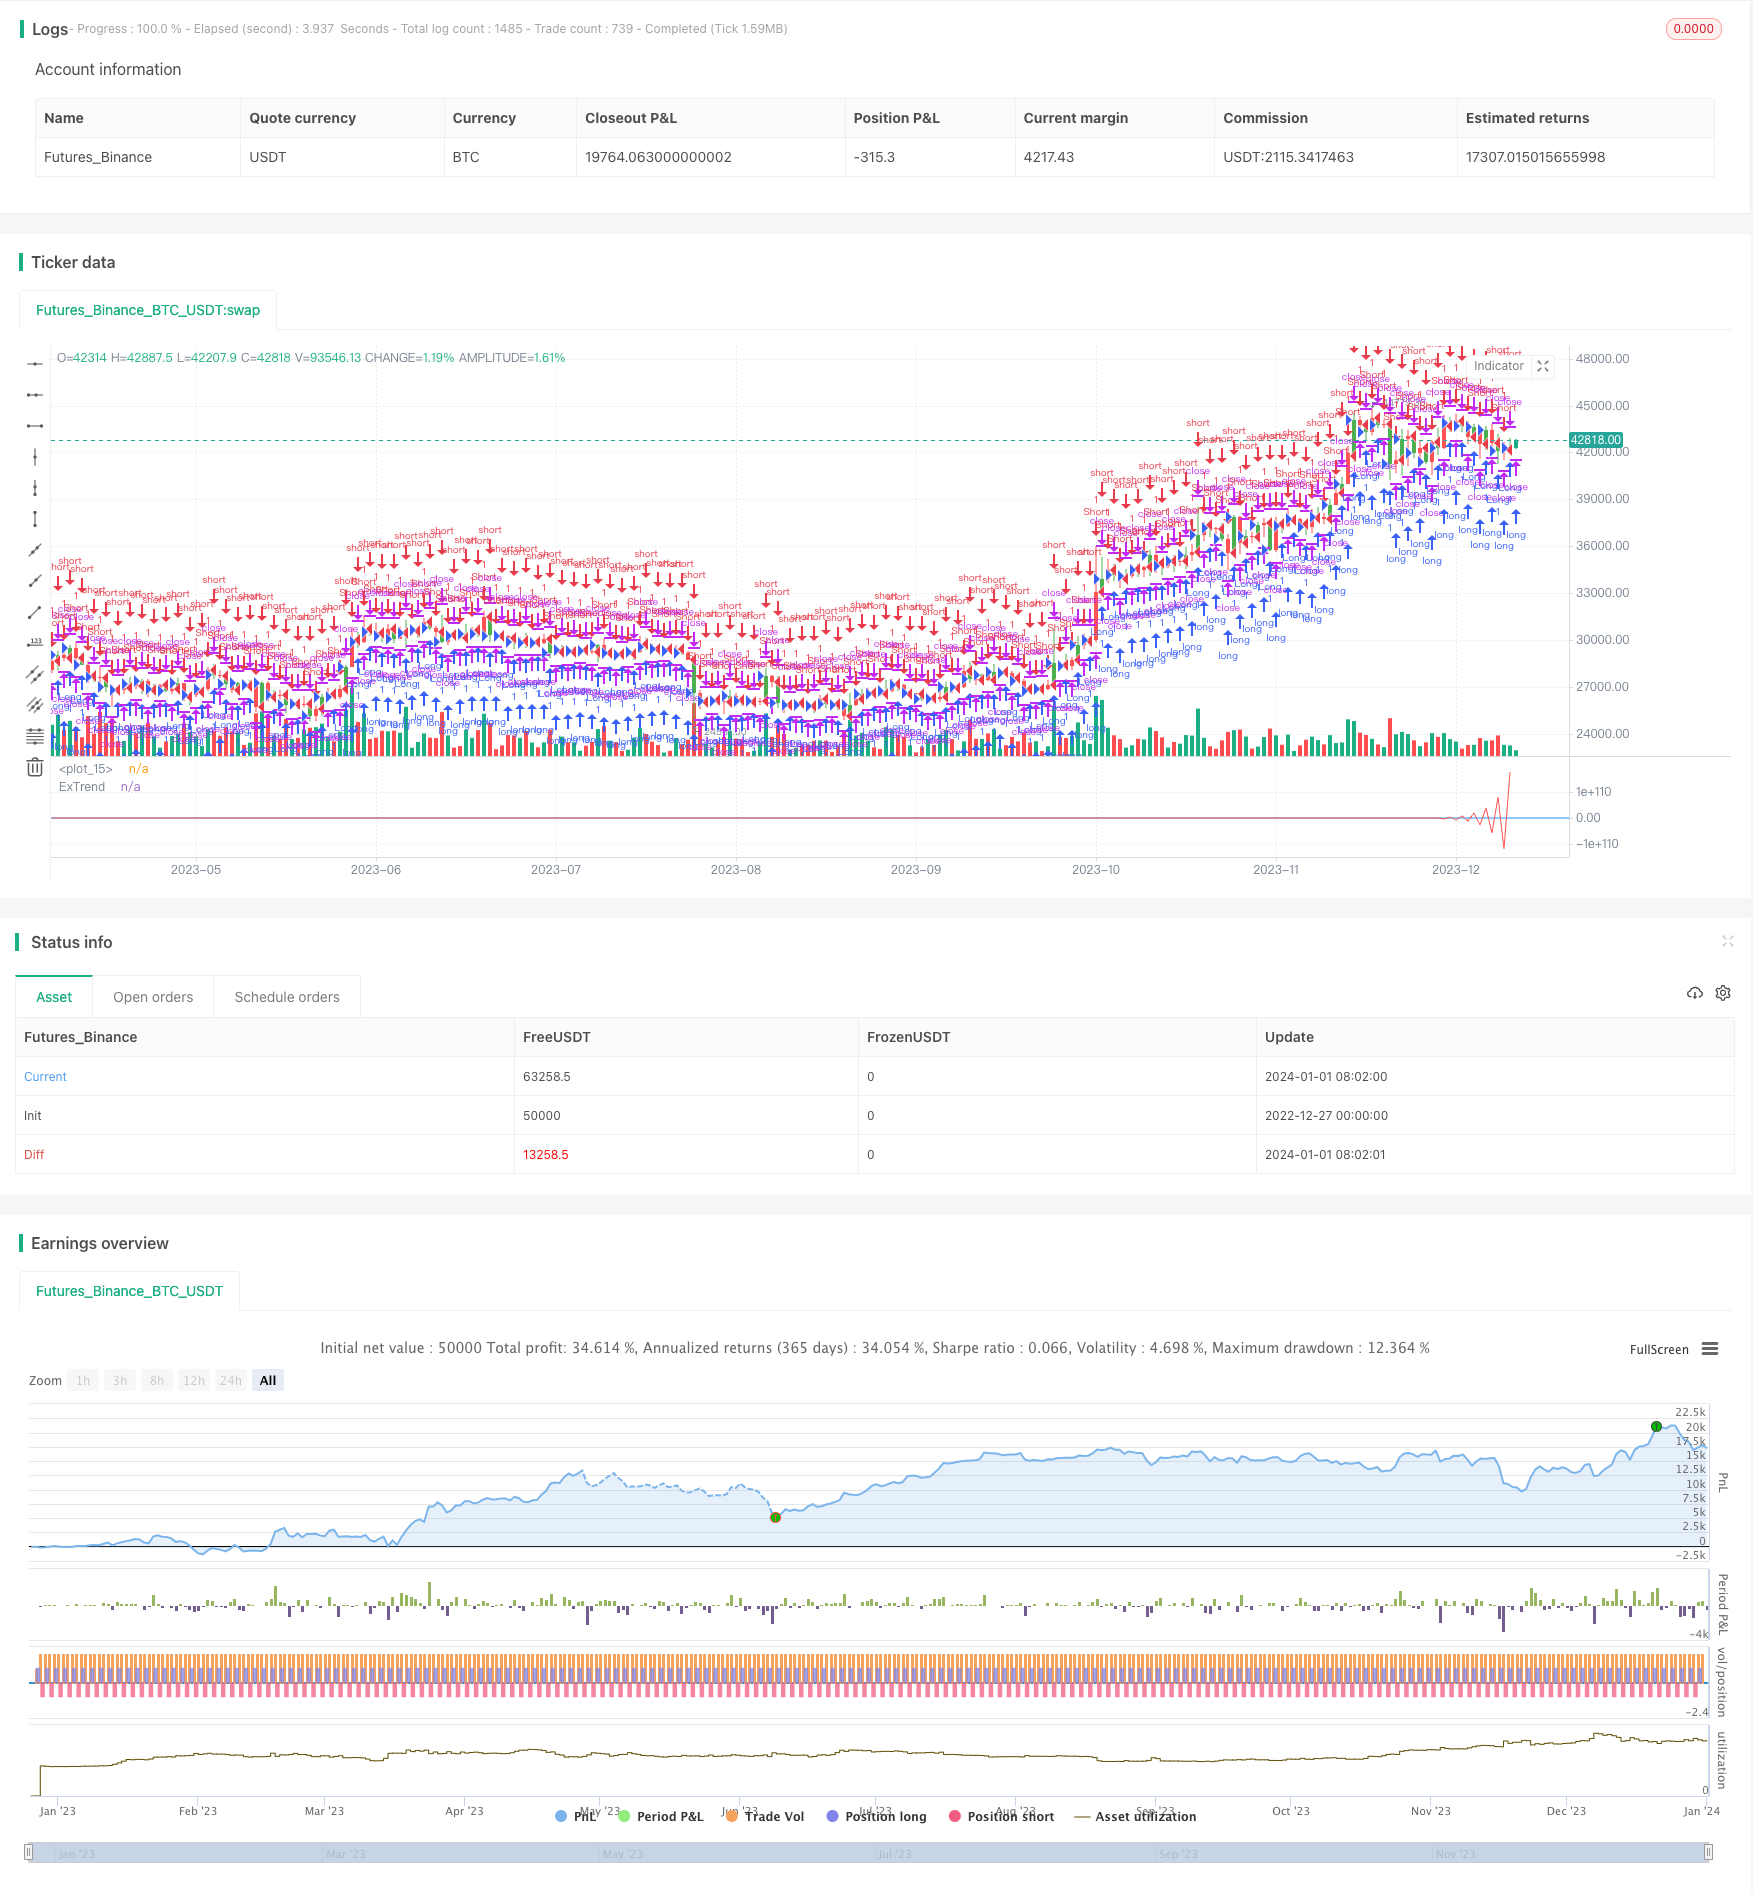
Overview
The Bandpass Filtering Trend Extraction Strategy is a stock trend tracking strategy based on bandpass filters. It uses an exponentially weighted moving average and bandpass filtering to process the price series and extract the trend component in prices as the signal for entries and exits.
Principles
The strategy first constructs a double exponential moving average by tuning the Length and Delta parameters to control the length of the moving average and smoothness. Then it uses a set of mathematical transformations to extract the trend component from the price series and stores it in the xBandpassFilter variable. Finally, it calculates the simple moving average of xBandpassFilter, xMean, as the indicator for entries and exits.
It goes long when xMean crosses above the Trigger level, and goes short when crossing below. The sensitivity of entries and exits can be controlled by tuning the Trigger level.
Advantages
- The double EMA effectively filters out some noise in prices for more stable strategies.
- Bandpass filtering only extracts the trend component in prices, avoiding whipsaws.
- Fewer parameters make optimization and risk control easier.
Risks
- Time lag causes missed opportunities from quick reversals.
- Double EMA and bandpass filtering have low pass effects, reducing sensitivity.
- Overfiltering can cause missing strong trends if parameters poorly tuned.
Shortening Length can improve lag issues. Tuning Trigger controls sensitivity.
Enhancements
- Add stop loss to control single trade loss.
- Dual moving averages system can improve stability.
- Combine with volume or other reversal signals to avoid whipsaws.
- Use machine learning or genetic algorithms to optimize parameters.
Conclusion
The strategy is relatively stable with good performance in strong trending markets. Further optimizations in multiple market environments can make it more reliably profitable. It warrants further research and application.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 20 | Length |
| v_input_2 | 0.5 | Delta |
| v_input_3 | false | Trigger |
| v_input_4 | false | Trade reverse |
Source Pine Script
/*backtest
start: 2022-12-27 00:00:00
end: 2024-01-02 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version = 2
////////////////////////////////////////////////////////////
//  Copyright by HPotter v1.0 14/12/2016
// The related article is copyrighted material from Stocks & Commodities Mar 2010
//
// You can use in the xPrice any series: Open, High, Low, Close, HL2, HLC3, OHLC4 and ect...
// You can change long to short in the Input Settings
// Please, use it only for learning or paper trading. Do not for real trading.
////////////////////////////////////////////////////////////
strategy(title="Extracting The Trend Strategy Backtest")
Length = input(20, minval=1)
Delta = input(0.5)
Trigger = input(0)
reverse = input(false, title="Trade reverse")
hline(Trigger, color=blue, linestyle=line)
xPrice = hl2
beta = cos(3.1415 * (360 / Length) / 180)
gamma = 1 / cos(3.1415 * (720 * Delta / Length) / 180)
alpha = gamma - sqrt(gamma * gamma - 1)
xBandpassFilter = 0.5 * (1 - alpha) * (xPrice - xPrice[2]) + beta * (1 + alpha) * nz(xBandpassFilter[1]) - alpha * nz(xBandpassFilter[2])
xMean = sma(xBandpassFilter, 2 * Length)
pos = iff(xMean > Trigger, 1,
	   iff(xMean < Trigger, -1, nz(pos[1], 0)))
possig = iff(reverse and pos == 1, -1,
          iff(reverse and pos == -1, 1, pos))
if (possig == 1)
    strategy.entry("Long", strategy.long)
if (possig == -1)
    strategy.entry("Short", strategy.short)
barcolor(possig == -1 ? red: possig == 1 ? green : blue )
plot(xMean, color=red, title="ExTrend")
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-03. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Bandpass-Filtering-Trend-Extraction-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- Bollinger Band Moving Average Crossover StrategyPine Script · Trend following · 1h
- Bollinger Bands and EMA Trend Following StrategyPine Script · Trend following · 1h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Candlestick Pattern Trend Filter StrategyPine Script · Trend following · 1d