Bidirectional Trading Strategy Based on Candlestick Absorption Pattern Analysis
This strategy is a bidirectional trading system based on candlestick absorption patterns. It identifies market absorption patterns by analyzing the direction, amplitude, and volume relationships of adjacent…
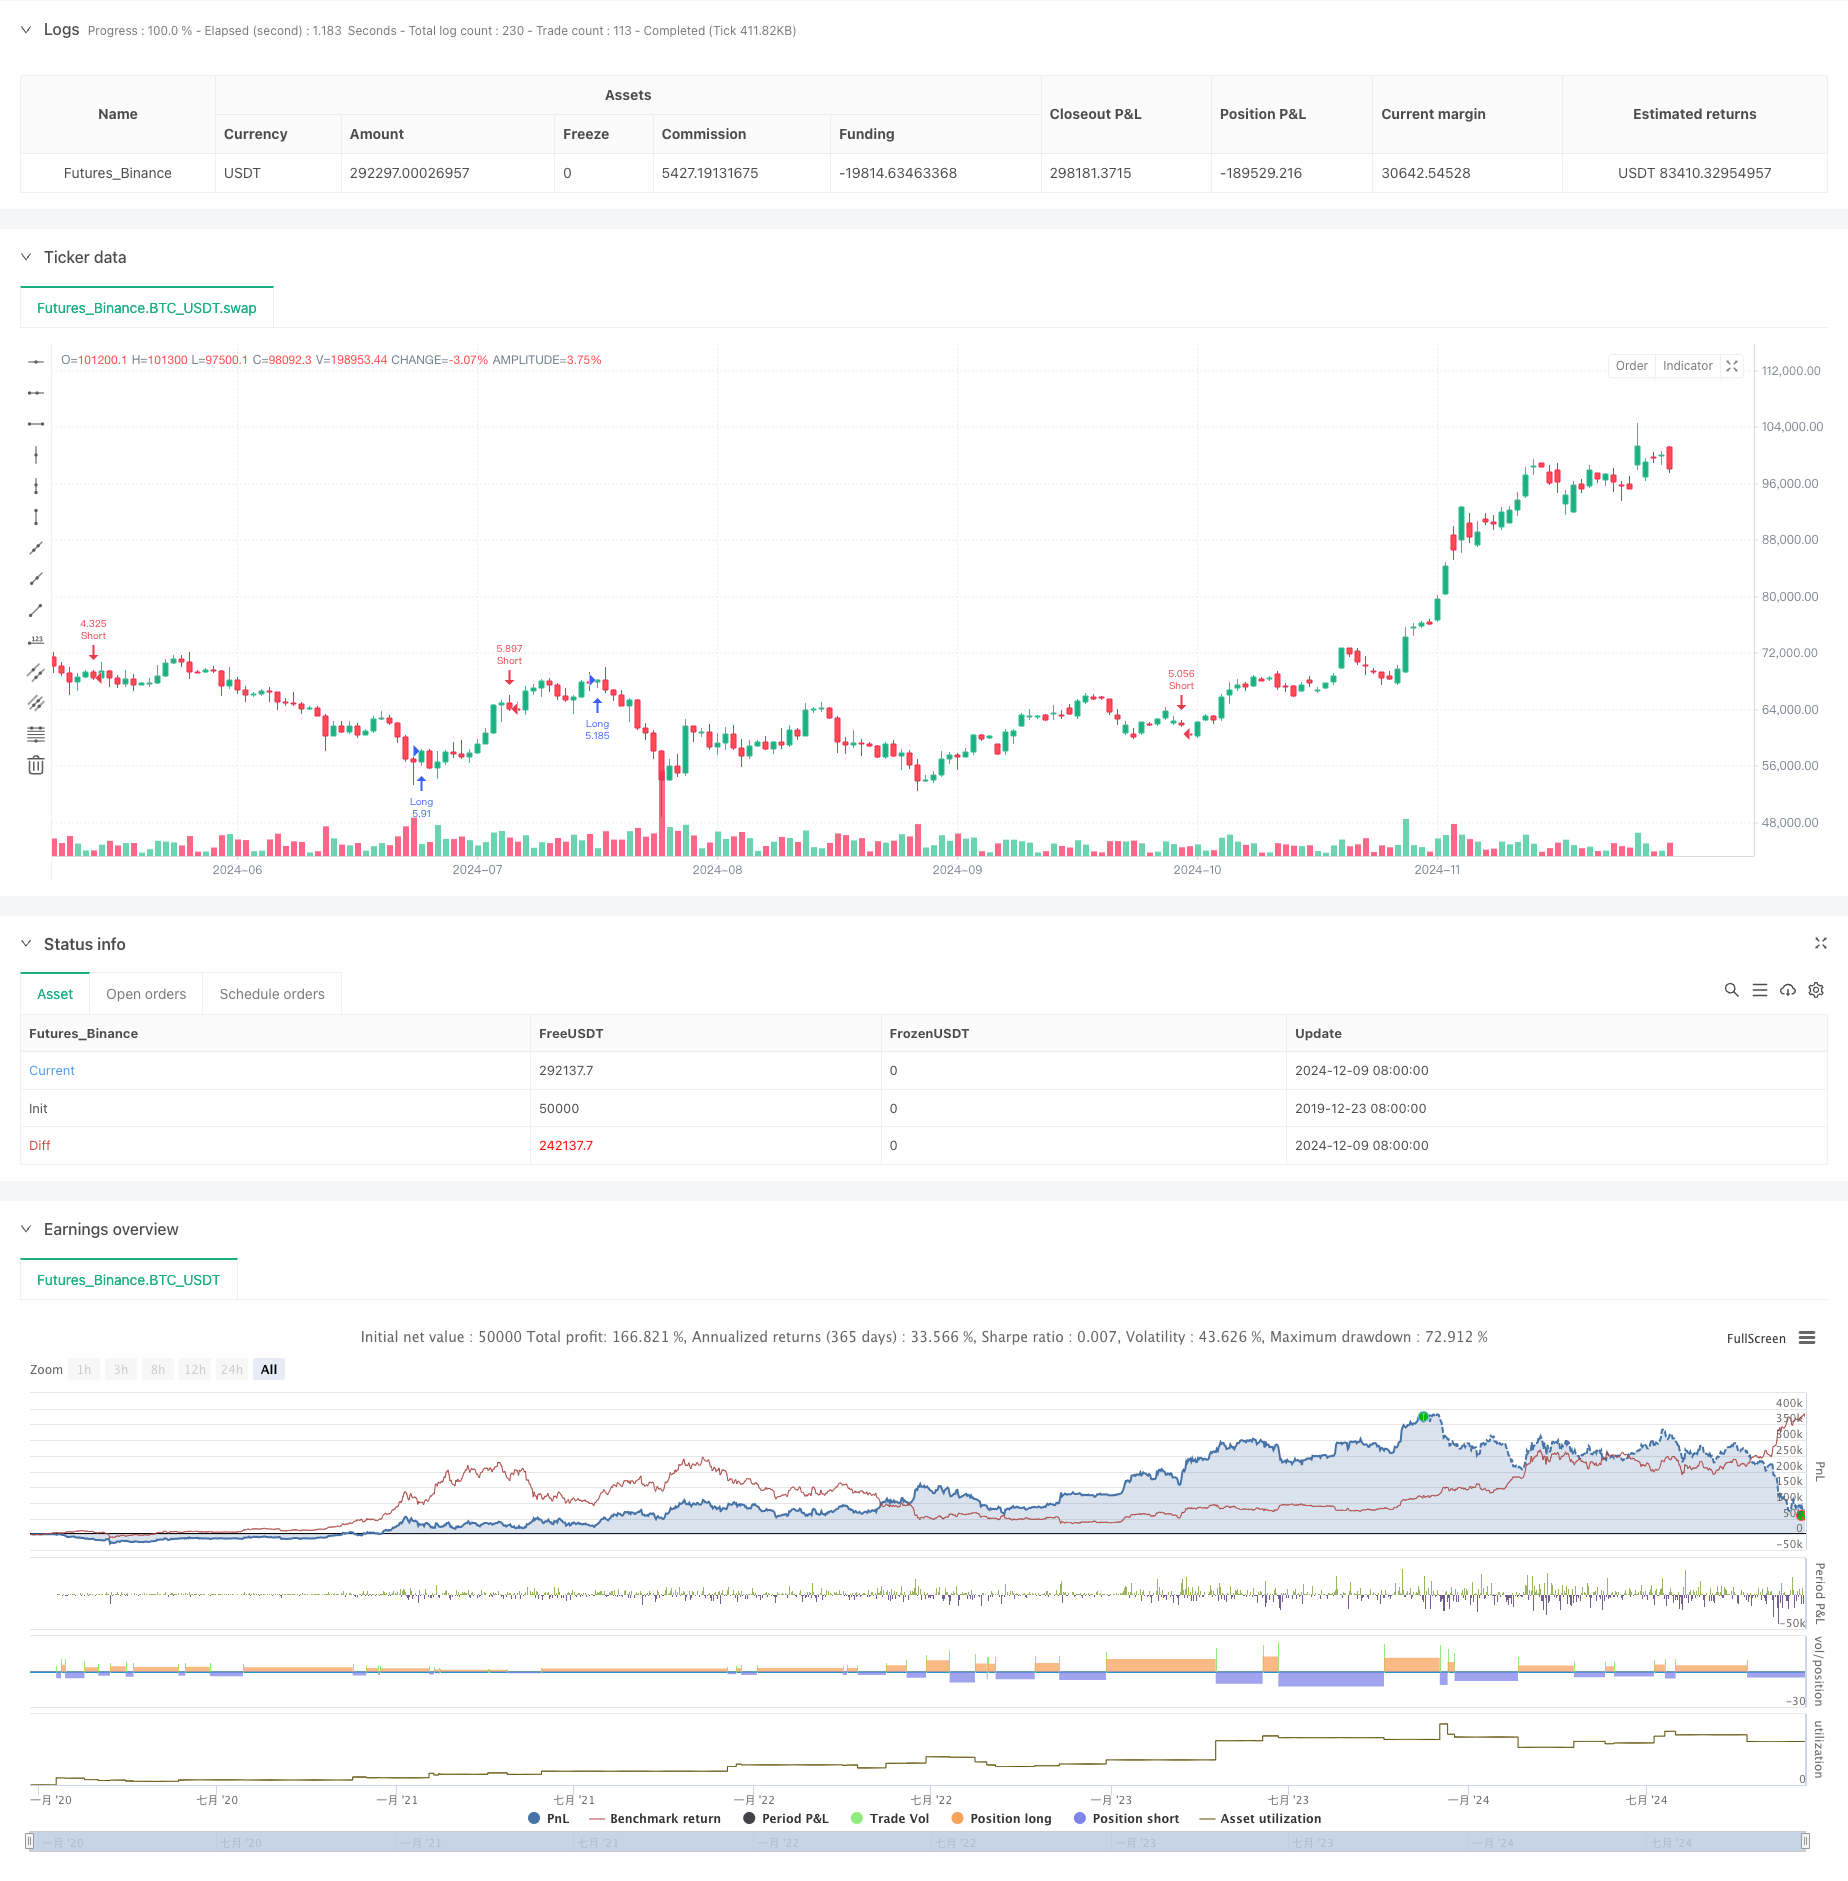
Overview
This strategy is a bidirectional trading system based on candlestick absorption patterns. It identifies market absorption patterns by analyzing the direction, amplitude, and volume relationships of adjacent candlesticks, executing trades when conditions are met. The strategy employs percentage-based money management with complete entry and exit logic.
Strategy Principle
The core logic is based on three key conditions:
- Adjacent candlesticks have opposite directions: Comparing open and close prices to determine candlestick direction, requiring opposite trends in adjacent candlesticks.
- Amplitude relationship analysis: Calculating and comparing the price amplitude of two candlesticks (absolute difference between close and open prices), requiring the latter candlestick's amplitude to be larger.
- Volume characteristics: Requiring the first candlestick's volume to be larger than the second, while the second candlestick's volume should be smaller than the previous volume.
When these three conditions are met simultaneously, the strategy determines the trading direction based on the latest candlestick: long for bullish candles, short for bearish ones. The strategy uses full position trading and tracks positions through state variables.
Strategy Advantages
- Multi-dimensional analysis: Combines price patterns, amplitude, and volume analysis to improve signal reliability.
- Bidirectional trading: Captures market opportunities in both directions, fully utilizing market volatility.
- Comprehensive risk management: Uses percentage-based money management with flexible stop-loss and take-profit settings.
- Visual support: Provides graphical display of trading signals for analysis and optimization.
- Clear state management: Precisely controls positions through state variables, avoiding duplicate entries.
Strategy Risks
- False breakout risk: False absorption patterns may appear in ranging markets, leading to incorrect signals.
- Slippage impact: May face significant slippage during high market volatility, affecting actual trading results.
- Money management risk: Full position trading may create large risk exposure.
- Signal lag: Signals can only be confirmed after candlestick closure, potentially missing optimal entry points.
Strategy Optimization Directions
- Introduce trend filtering: Recommend adding moving averages or trend indicators for direction filtering to improve signal quality.
- Optimize money management: Position size can be dynamically adjusted based on market volatility.
- Enhance stop-loss mechanism: Recommend implementing dynamic stop-loss using ATR indicator to improve risk control.
- Add time filtering: Can add trading time period filters to avoid inefficient periods.
- Improve signal confirmation: Can add volume indicators or other technical indicators for auxiliary confirmation.
Summary
This strategy constructs a complete trading system through multi-dimensional analysis of candlestick patterns, amplitude, and volume. While certain risks exist, the strategy's stability and reliability can be further enhanced through the suggested optimization directions. The core advantages lie in its multi-dimensional analysis method and comprehensive state management mechanism, making it suitable for application in highly volatile market environments.
Source Pine Script
/*backtest
start: 2019-12-23 08:00:00
end: 2024-12-10 08:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Candle Absorption Strategy", overlay=true, default_qty_type=strategy.percent_of_equity, default_qty_value=100)

// Условия индикатора
// 1. Две соседних свечи должны быть разнонаправленными
condition1 = (close[1] > open[1] and close < open) or (close[1] < open[1] and close > open)

// 2. Дельта по цене открытия/закрытия у первой свечи меньше, чем у следующей
delta1 = math.abs(close[1] - open[1])
delta2 = math.abs(close - open)
condition2 = delta1 < delta2

// 3. Объем первой свечи должен быть больше, а последней меньше
condition3 = volume[1] > volume and volume < volume[2]

// Проверяем выполнение всех условий
all_conditions = condition1 and condition2 and condition3

// Определяем направление для входа
is_bullish = close > open  // Зеленая свеча больше (бычье поглощение)
is_bearish = close < open  // Красная свеча больше (медвежье поглощение)

// Переменные для отслеживания состояния позиции
var float entryPrice = na
var bool isLong = false
var bool isShort = false

// Логика генерации сигналов
buySignal = all_conditions and is_bullish and not isLong
sellSignal = all_conditions and is_bearish and not isShort

// Обработка лонгового входа
if (buySignal)
    isLong := true
    isShort := false
    entryPrice := close
    strategy.entry("Long", strategy.long)

// Обработка шортового входа
if (sellSignal)
    isLong := false
    isShort := true
    entryPrice := close
    strategy.entry("Short", strategy.short)

// Визуализация точек поглощения
// if all_conditions
//     label.new(bar_index, high, "✔", color=is_bullish ? color.green : color.red, textcolor=color.white, style=label.style_circle, size=size.small)

// Логика сброса состояния при закрытии позиции
if (strategy.position_size == 0)
    isLong := false
    isShort := false
    entryPrice := na

// Дополнительно: можно добавить стоп-лосс и тейк-профит (пример ниже)
// strategy.exit("Exit Long", from_entry="Long", stop=low - atr(14), limit=high + atr(14))
// strategy.exit("Exit Short", from_entry="Short", stop=high + atr(14), limit=low - atr(14))
Published by ChaoZhang on the FMZ strategy square · last modified 2024-12-12. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Bidirectional-Trading-Strategy-Based-on-Candlestick-Absorption-Pattern-Analysis.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ATR Trailing Stops StrategyPine Script · Breakout · 1h
- ATR Trend Breakout StrategyPine Script · Breakout · 1d
- Advanced Multi Pattern Breakout Trading StrategyPine Script · Breakout · 1d
- BB Breakout StrategyPine Script · Breakout · 1d
- Bollinger Band Breakout Trend Following StrategyPine Script · Breakout · 1d
- Breakout Strategy Based on Turtle TradingPine Script · Breakout · 1d