Strategy vault / Trend following
Bitcoin MA Crossover Strategy
This strategy is a trend following trading strategy designed based on the crossover principle of Bitcoin's moving average lines. The strategy uses the crossover of the fast moving average line and the slow moving…
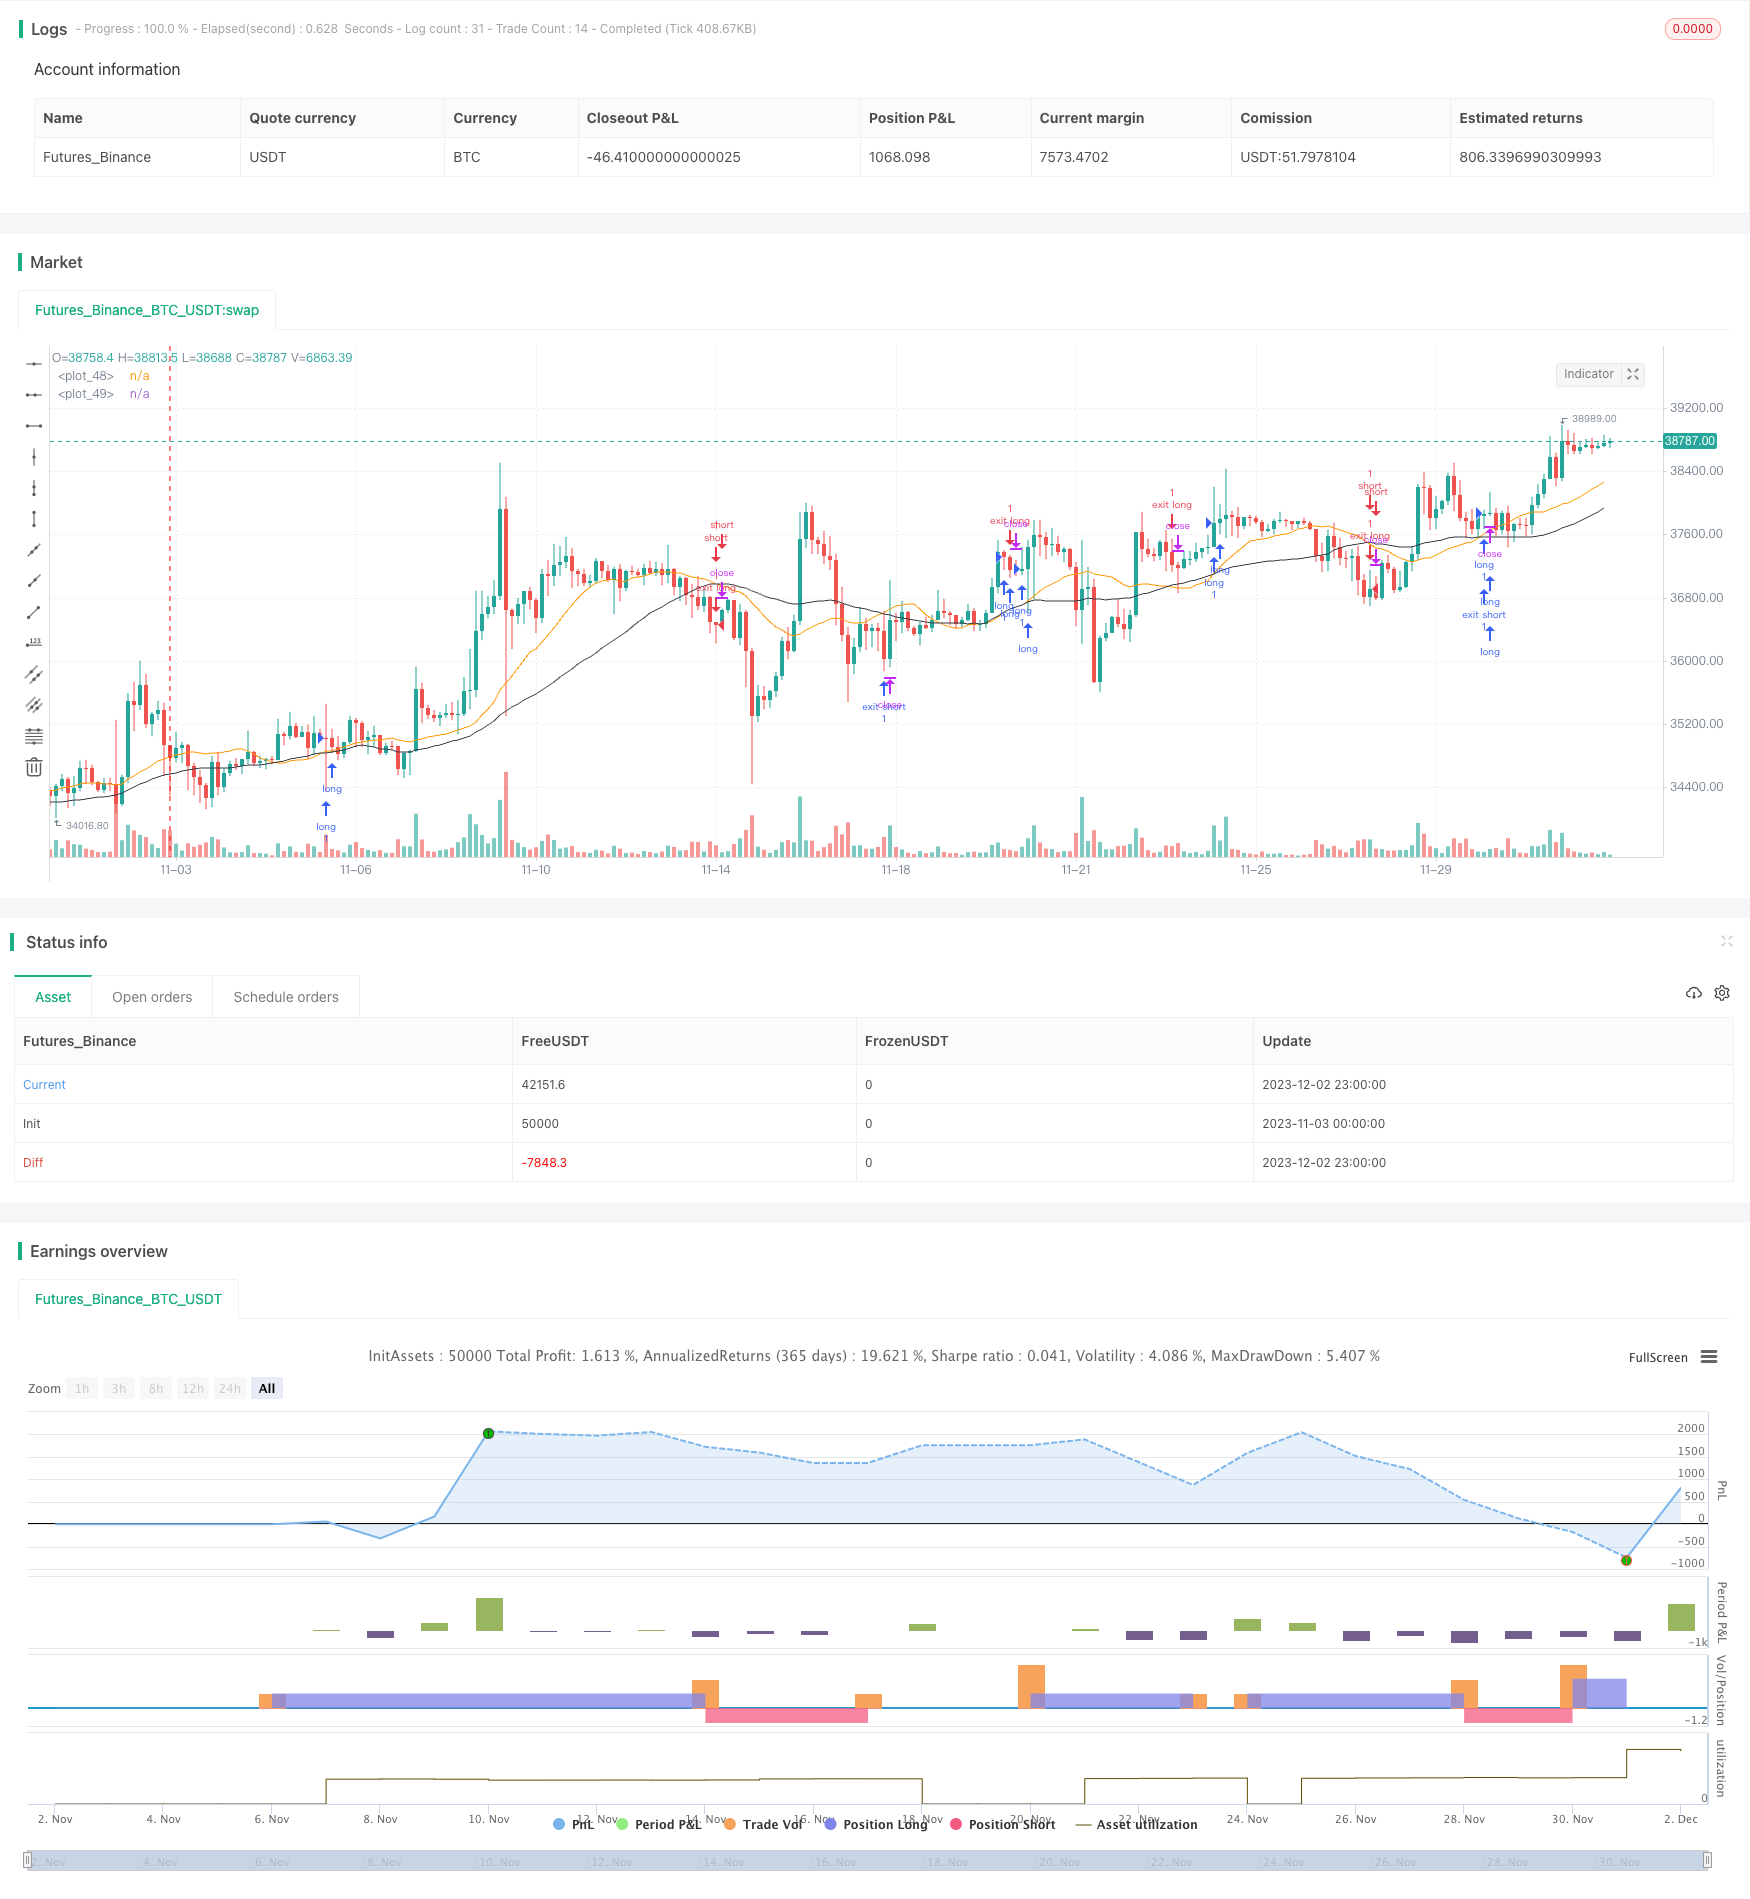
Overview
This strategy is a trend following trading strategy designed based on the crossover principle of Bitcoin's moving average lines. The strategy uses the crossover of the fast moving average line and the slow moving average line as the buy and sell signals. When the fast moving average line crosses above the slow moving average line, it is considered a golden cross and goes long; when the fast moving average line crosses below the slow moving average line, it is considered a death cross and goes short. At the same time, the strategy also incorporates the RSI indicator to avoid reckless entry.
Strategy Principle
The strategy is mainly based on two indicators:
Moving Average (MA): Calculates the average closing price over a certain period to determine price trends and reversal signals.
Relative Strength Index (RSI): Calculates the speed of price rises and falls over a certain period to judge overbought and oversold areas.
Specifically, the strategy uses a shorter MA as the fast line and a longer MA as the slow line. When the fast line crosses above the slow line, it indicates that the short-term price rise is accelerating and a buy signal is generated; when the fast line crosses below the slow line, it indicates that the short-term price decline is accelerating and a sell signal is generated.
At the same time, the strategy also sets a threshold for RSI, generating buy signals only when the RSI is above 50 and sell signals only when the RSI is below 50, avoiding reckless entry when prices fluctuate violently.
Advantage Analysis
The strategy has the following advantages:
- The principle is simple and easy to understand and implement.
- Reliable trading signals avoid irrational entry.
- Fewer parameters and easy to optimize.
- Mature moving average technique with wide application.
- RSI indicator can effectively identify overbought and oversold phenomena.
Risk Analysis
The strategy also has some risks:
- Trend following strategies are prone to large losses when prices reverse.
- Moving averages lag and fail to promptly capture price reversals.
- Incorrect parameter selection can lead to deteriorated trading signal quality.
- The strategy only considers technical indicators without fundamental factors.
To mitigate risks, it is recommended to optimize the moving average period parameters, adjust stop loss positions, and appropriately scale down position sizes. The strategy should be suspended when major fundamental changes occur.
Optimization Directions
The main optimization directions for this strategy include:
Optimize the moving average period parameters to find the optimal parameter combination, through incremental search, genetic algorithms, etc.
Increase other technical indicators for filtration, such as KDJ, MACD, etc. to improve trading signal quality.
Monitor price fluctuations and adjust positions and stop losses accordingly.
Incorporate trading volume to avoid false breakouts, only issuing signals when trading volume expands.
Develop parameter self-adaptive mechanisms, allowing strategies to automatically adjust parameter values based on different market environments.
Conclusion
In summary, this is a typical trend-following strategy. Based on the principle of moving average crossover, the trading logic is simple and clear, easy to understand and implement. Incorporating the RSI indicator can avoid irrational trading. The strategy carries both risks and rewards, suitable for investors with some quant trading experience, but the potential loss risks need to be guarded against. If developers can add more filters, optimize parameter adaptivity, it can further improve the steady profitability of the strategy.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 10 | Equity Risk (%) |
| v_input_2 | 20 | Fast MA (Period) |
| v_input_3 | 40 | Slow MA (Period) |
| v_input_4 | 14 | RSI (Period) |
Source Pine Script
/*backtest
start: 2023-11-03 00:00:00
end: 2023-12-03 00:00:00
period: 3h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
//Trading Strategy Warning - Past performance may not equal future performance
//Account Size Warning - Performance based upon default 10% risk per trade, of account size $100,000. Adjust before you trade to see your own drawdown.
//Time Frame - D1 and H4, warning H4 has a lower profit factor (fake-outs, and account drawdown), D1 recommended
//Trend Following System - Profitability of this system is dependent on a STRONG trend in Bitcoin, into the future
strategy("Bitcoin - MA Crossover Strategy", overlay=true)

// User Input
usr_risk = input(title="Equity Risk (%)",type=input.integer,minval=1,maxval=100,step=1,defval=10,confirm=false)
sma_fast = input(title="Fast MA (Period)",type=input.integer,minval=1,maxval=500,step=1,defval=20,confirm=false)
sma_slow = input(title="Slow MA (Period)",type=input.integer,minval=1,maxval=500,step=1,defval=40,confirm=false)
rsi_valu = input(title="RSI (Period)",type=input.integer,minval=1,maxval=500,step=1,defval=14,confirm=false)

// Create Indicator's
shortSMA = sma(close, sma_fast)
longSMA = sma(close, sma_slow)
rsi = rsi(close, rsi_valu)
strategy.initial_capital = 50000
// Units to buy
amount = usr_risk / 100 * (strategy.initial_capital + strategy.netprofit)
units = floor(amount / close)

// Specify entry conditions
longEntry = crossover(shortSMA, longSMA)
shortEntry = crossunder(shortSMA, longSMA)

// Specify exit conditions
longExit = crossunder(shortSMA, longSMA)
shortExit = crossover(shortSMA, longSMA)

// Execute long trade
if (longEntry)
    strategy.entry("long", strategy.long, units, when = rsi > 50)

// Exit long trade
if(longExit and strategy.position_size > 0)
    strategy.order("exit long", strategy.short, abs(strategy.position_size))

// Execute short trade
if (shortEntry)
    strategy.entry("short", strategy.short, units, when = rsi < 50)

// Exit short trade
if(shortExit and strategy.position_size < 0)
    strategy.order("exit short", strategy.long, abs(strategy.position_size))

// Plot Moving Average's to chart
plot(shortSMA)
plot(longSMA, color=color.black)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-04. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Bitcoin-MA-Crossover-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive Trading Strategy Based on Stochastic RSI Dual Line CrossoverPine Script · Trend following · 4h
- BB Percentage Index Trend Fading StrategyPine Script · Trend following · 1h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Crypto RSI Mini Sniper Quick Response Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dual Mode Adaptive Trend Trading Strategy EMA Crossover with ATR Volatility Based Risk Management SystemPine Script · Trend following · 1d