Bollinger Bands Breakout Quantitative Trading Strategy 458192
This article introduces a quantitative trading strategy based on Bollinger Bands breakout. The strategy utilizes the Bollinger Bands indicator to identify overbought and oversold market conditions, generating trading…
Overview
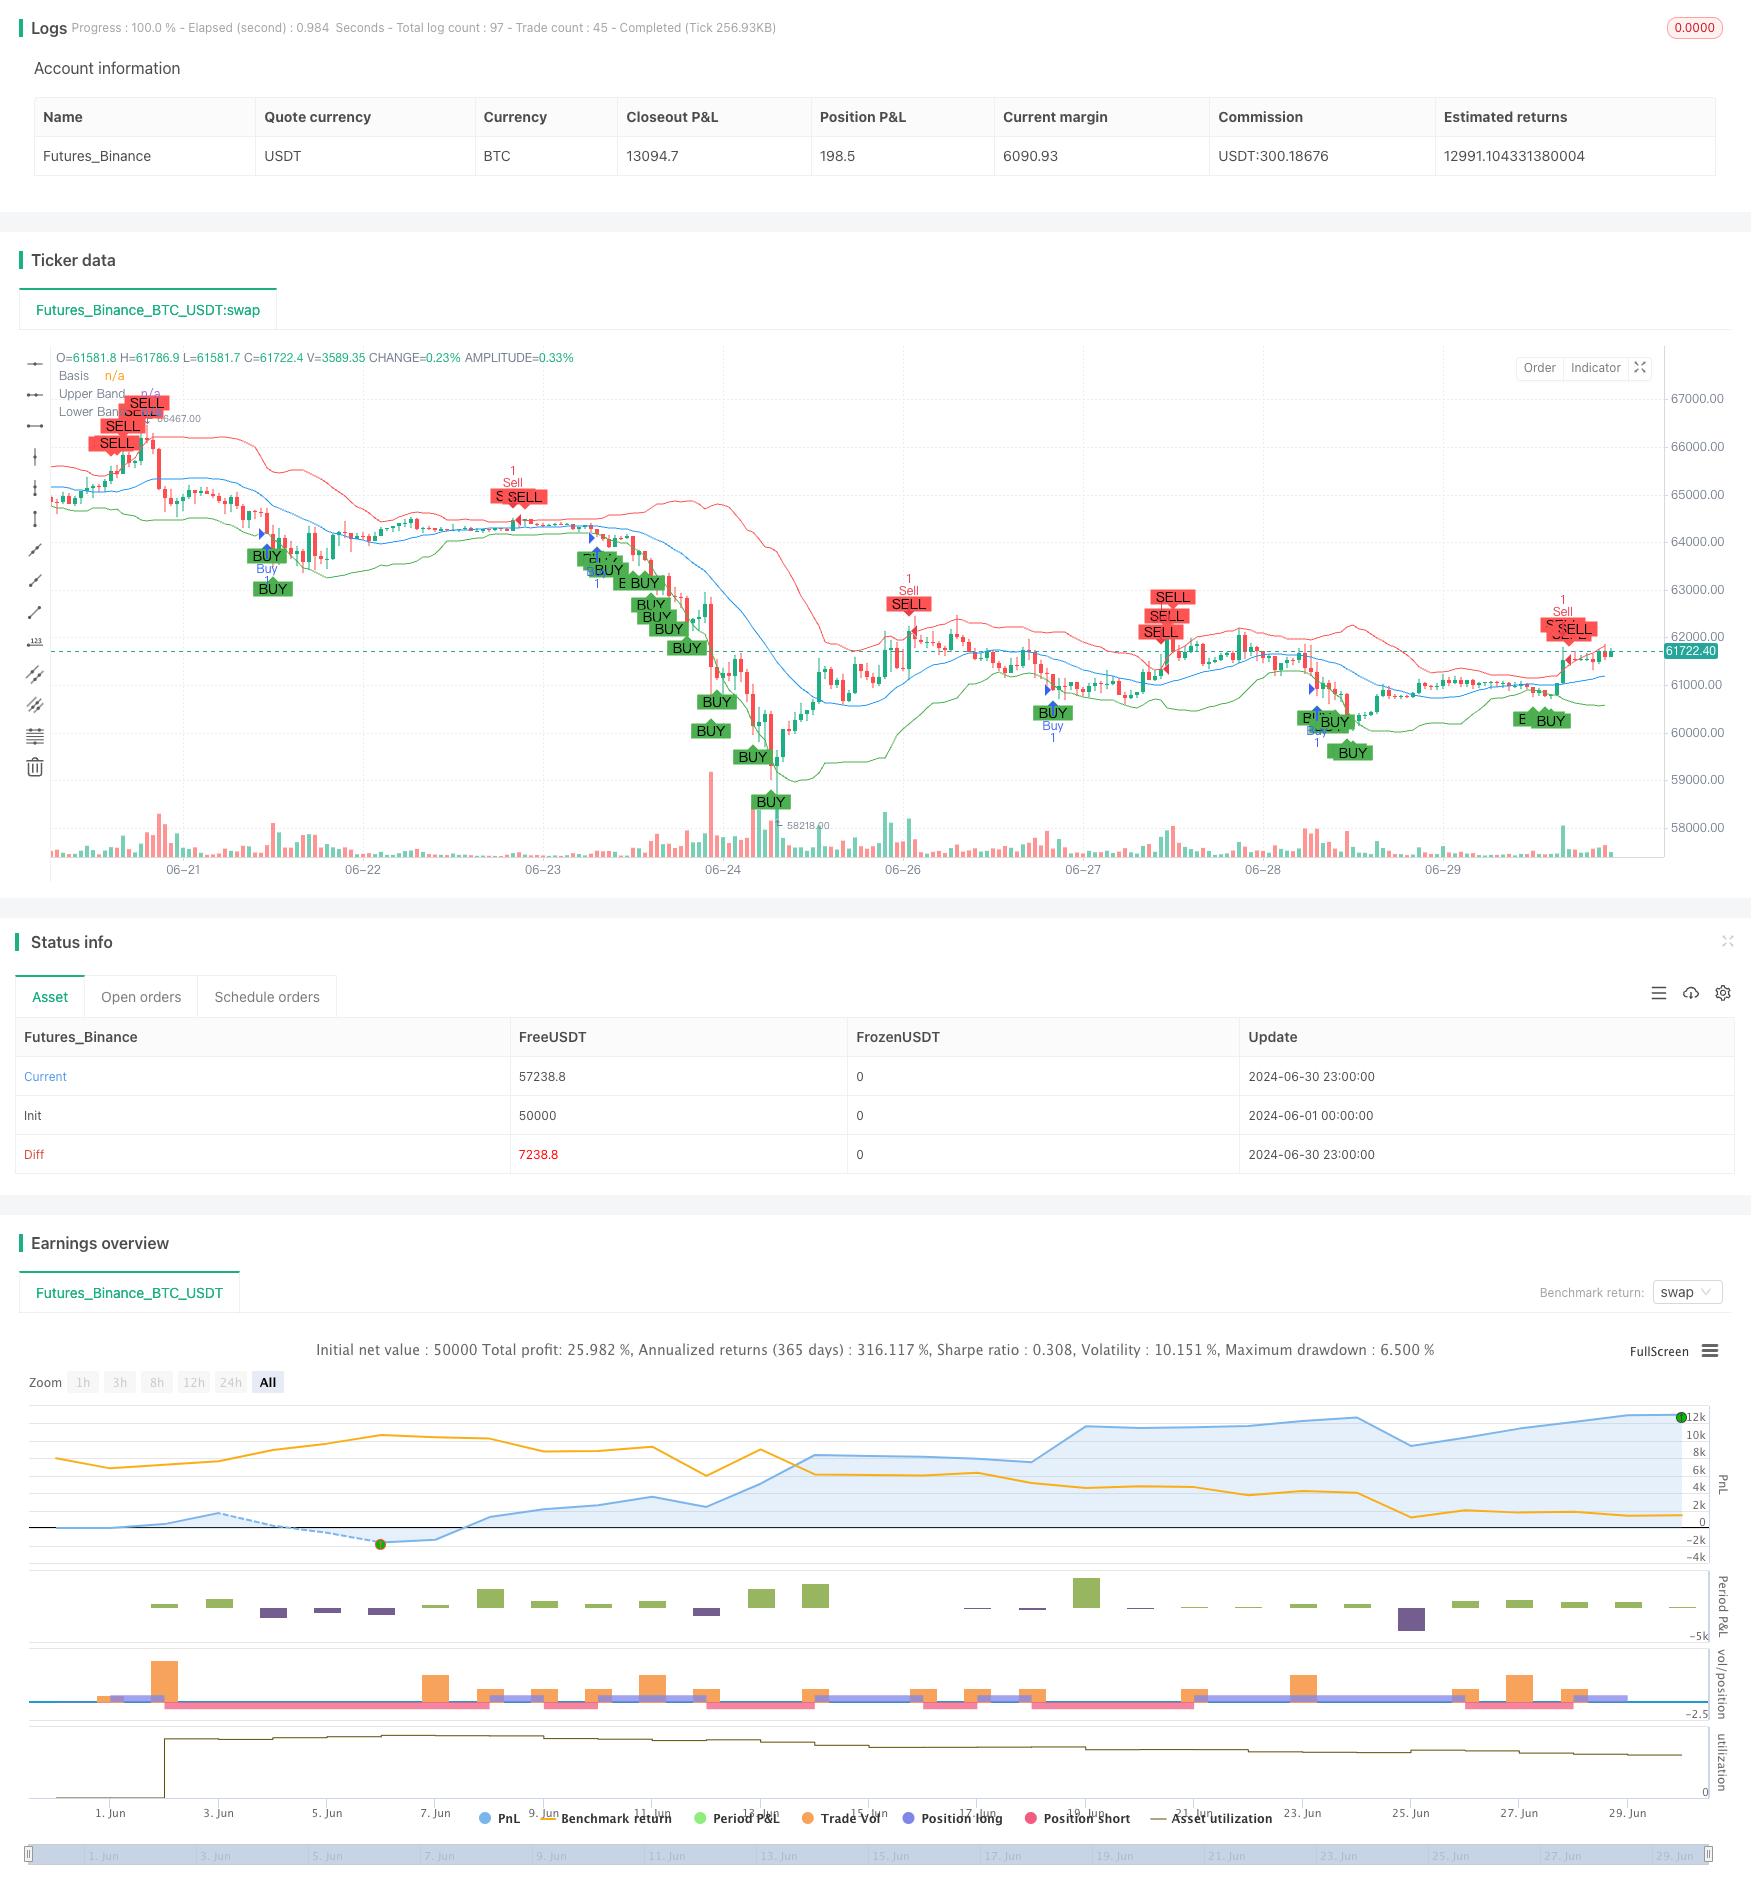
This article introduces a quantitative trading strategy based on Bollinger Bands breakout. The strategy utilizes the Bollinger Bands indicator to identify overbought and oversold market conditions, generating trading signals when prices break above or below the bands. This approach aims to capture significant market movements while providing a certain level of risk management.
Strategy Principles
The core principle of the Bollinger Bands breakout strategy is to use the concept of standard deviation from statistics to measure market volatility. The main steps of the strategy are as follows:
Calculate Bollinger Bands: Use a 20-day Simple Moving Average (SMA) as the middle band, with upper and lower bands set at 2 standard deviations above and below the middle band.
Generate trading signals:
- A long signal is generated when the closing price is below the lower band.
- A short signal is generated when the closing price is above the upper band.
Execute trades: Perform corresponding long or short operations based on the generated signals.
Visualization: Plot the Bollinger Bands and trading signals on the chart for intuitive analysis.
This method assumes that prices will fluctuate within the Bollinger Bands most of the time, and a breakout above or below the bands indicates a potential trend reversal or continuation opportunity.
Strategy Advantages
High adaptability: Bollinger Bands automatically adjust their width based on market volatility, allowing the strategy to adapt to different market environments.
Combines trend-following and reversal: Can capture both trend continuations and potential reversal opportunities.
Integrated risk management: Bollinger Bands themselves provide overbought and oversold indications, helping to control risk.
Good visualization: Trading signals and market conditions can be intuitively observed through the chart.
Flexible parameters: Bollinger Bands length and multiplier can be adjusted according to different market characteristics.
Fully automated: The strategy can be executed completely automatically, reducing human intervention.
Strategy Risks
False breakout risk: The market may experience brief breakouts followed by quick reversals, leading to false signals.
Underperformance in trending markets: In strong trend markets, prices may run outside the Bollinger Bands for extended periods, causing frequent trading.
Lag: Due to the use of moving averages, the strategy may react slowly in rapidly changing markets.
Overtrading: In highly volatile markets, too many trading signals may be generated, increasing transaction costs.
Lack of stop-loss mechanism: The code does not include an explicit stop-loss strategy, which may lead to significant losses.
Dependence on a single indicator: Relying solely on Bollinger Bands may ignore other important market information.
Strategy Optimization Directions
Introduce auxiliary indicators: Combine with other technical indicators (such as RSI or MACD) to filter trading signals and improve accuracy.
Add stop-loss and take-profit: Implement automatic stop-loss and take-profit functions to better control risk and lock in profits.
Dynamic parameter adjustment: Automatically adjust Bollinger Bands length and multiplier based on market volatility to improve strategy adaptability.
Add trading filters: Set minimum breakout amplitude or duration requirements to reduce false breakouts.
Optimize position management: Implement dynamic position allocation, adjusting trade size based on signal strength and market volatility.
Incorporate market trend judgment: Adjust the strategy in strong trend markets to avoid frequent counter-trend trading.
Backtesting and optimization: Conduct comprehensive backtests on different markets and timeframes to find the optimal parameter combinations.
Conclusion
The Bollinger Bands breakout quantitative trading strategy is a simple yet effective trading method that leverages statistical principles to capture market volatility opportunities. Its main advantages lie in its strong adaptability, integrated risk management, and fully automated execution. However, the strategy also has potential issues such as false breakout risks and underperformance in trending markets.
By introducing auxiliary indicators, improving risk management, and dynamically adjusting parameters, the stability and profitability of the strategy can be significantly enhanced. Future research directions could focus on multi-timeframe analysis and integration of machine learning algorithms to further improve the strategy's intelligence and adaptability.
Overall, the Bollinger Bands breakout strategy provides a solid foundation for quantitative trading. Through continuous optimization and improvement, it has the potential to become a reliable trading tool.
Source Pine Script
//@version=5
strategy("Bollinger Bands Breakout Strategy", overlay=true)

// Parameters
bbLength = input.int(20, title="Bollinger Bands Length")
bbMultiplier = input.float(2.0, title="Bollinger Bands Multiplier")

// Calculate Bollinger Bands
basis = ta.sma(close, bbLength)
dev = bbMultiplier * ta.stdev(close, bbLength)
upperBand = basis + dev
lowerBand = basis - dev

// Plot Bollinger Bands
plot(basis, color=color.blue, title="Basis")
plot(upperBand, color=color.red, title="Upper Band")
plot(lowerBand, color=color.green, title="Lower Band")

// Entry conditions
longCondition = close < lowerBand
shortCondition = close > upperBand

// Execute trades
if (longCondition)
    strategy.entry("Buy", strategy.long)

if (shortCondition)
    strategy.entry("Sell", strategy.short)

// Plot buy/sell signals
plotshape(series=longCondition, title="Buy Signal", location=location.belowbar, color=color.green, style=shape.labelup, text="BUY")
plotshape(series=shortCondition, title="Sell Signal", location=location.abovebar, color=color.red, style=shape.labeldown, text="SELL")
Published by ChaoZhang on the FMZ strategy square · last modified 2024-07-30. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Bollinger-Bands-Breakout-Quantitative-Trading-Strategy-458192.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive Bollinger Breakout with Moving Average Quantitative Strategy SystemPine Script · Breakout · 1h
- BB Breakout StrategyPine Script · Breakout · 1d
- Bollinger Band Breakout Trend Following StrategyPine Script · Breakout · 1d
- Bollinger Band Channel Breakout Trading StrategyPine Script · Breakout · 1d
- Bollinger Band T3 Moving Average StrategyPine Script · Breakout · 10m
- Bollinger Bands Breakout Trading StrategyPine Script · Breakout · 1h