Bollinger Bands Breakout Strategy 442259
The Bollinger Bands breakout strategy is a simple quantitative trading strategy based on the Bollinger Bands indicator. The strategy utilizes the dynamic support and resistance levels provided by the upper and lower…
Overview
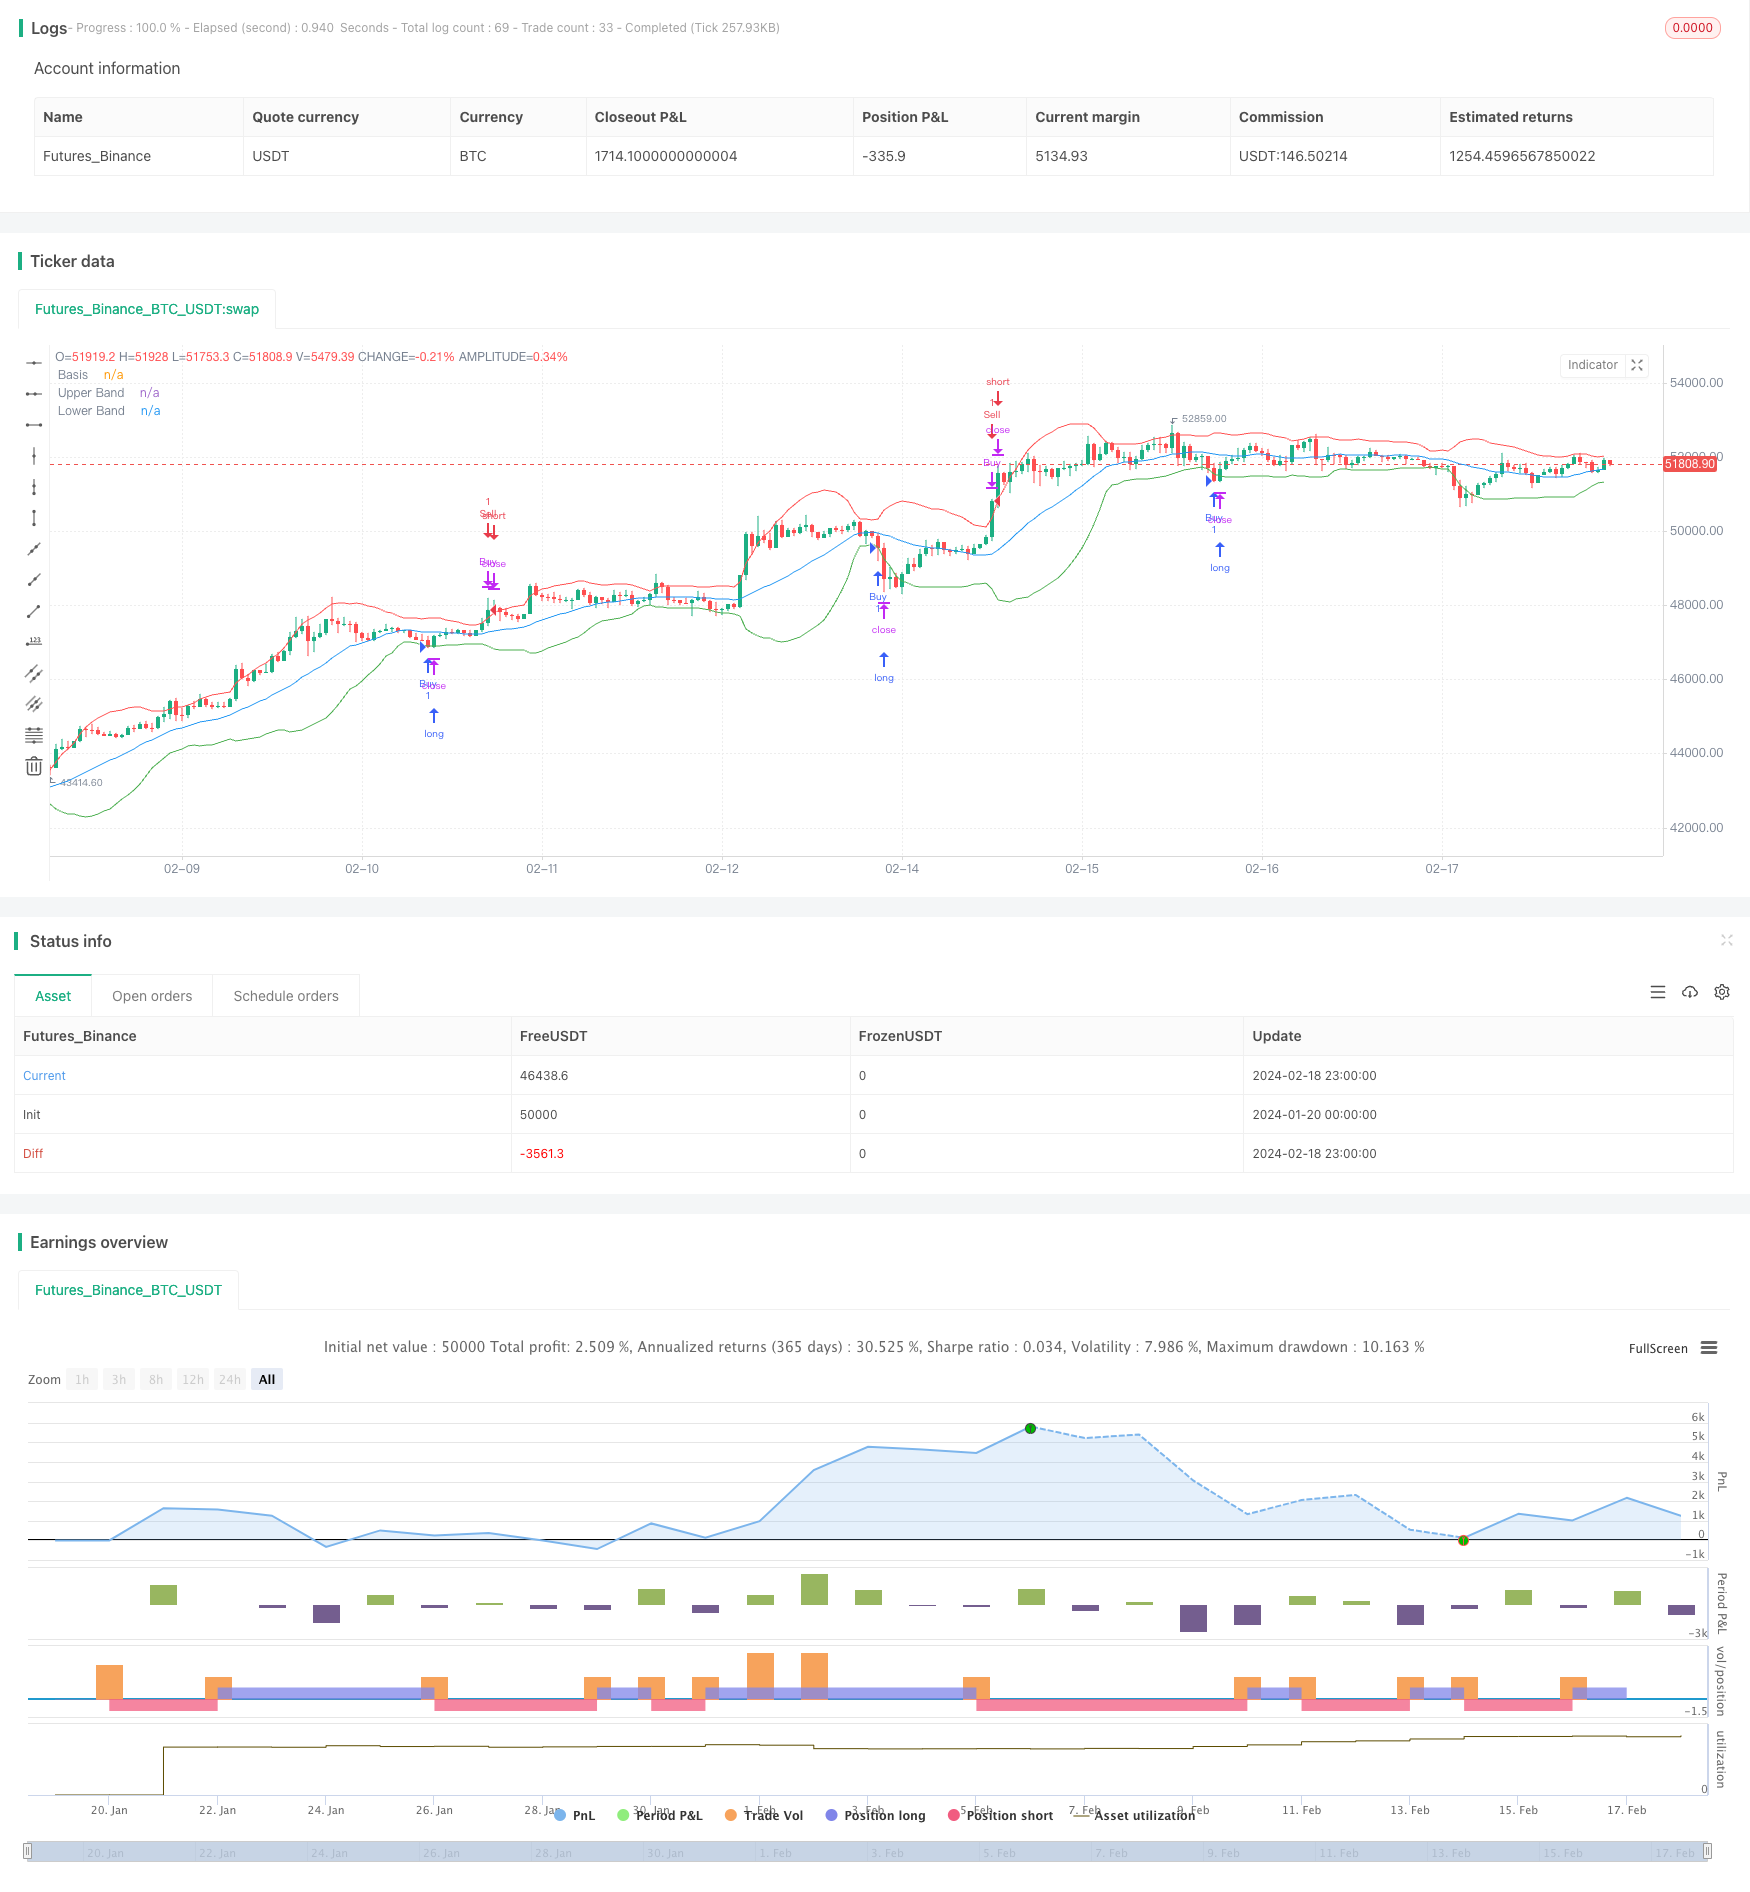
The Bollinger Bands breakout strategy is a simple quantitative trading strategy based on the Bollinger Bands indicator. The strategy utilizes the dynamic support and resistance levels provided by the upper and lower bands of Bollinger Bands to set entry rules for long positions when prices break out of the bands and exit rules when prices break back through the bands, aiming to capture trend-following opportunities in the price movements.
Strategy Logic
The Bollinger Bands indicator was developed by John Bollinger in the 1980s. It consists of an n-period moving average and m times standard deviation above and below it. The moving average acts as the midpoint, while the standard deviation accounts for the volatility. High standard deviation values indicate increased volatility, while low values indicate decreased volatility.
The entry condition for this strategy is: a long position will be taken when the closing price breaks below the lower Bollinger band; a short position will be taken when the closing price breaks above the upper Bollinger band. The exit rules are: for existing long positions, liquidate when closing price breaks back above the upper band; for existing short positions, cover when closing price breaks back below the lower band.
This is a trend-following strategy. By capturing trend continuation signaled by the breaking of Bollinger Bands, it aims to profit from sustained directional price movements.
Advantages
Using Bollinger Bands as dynamic support/resistance levels instead of fixed prices makes the strategy adaptive to evolving market conditions.
Decisions are based on both price levels and volatility conditions, avoiding some false signals.
The breakout framework is simple and intuitive.
Flexible tuning of parameters makes the strategy adaptable across products and markets.
Risks
Poor parameter tuning of indicators may cause too frequent trading and unnecessary costs.
Breakout signals may just be short-term price fluctuations instead of sustainable trends.
The lack of stop loss exposes the strategy to uncontrolled loss risks.
The purely technical system misses fundamental trend reversals.
Performance may vary across different products without adjustments.
Enhancement Opportunities
Optimize parameters to enhance robustness.
Incorporate stop loss orders to limit losses.
Build multi-timeframe system to improve decisions.
Add volume filters to avoid false signals.
Complement fundamentals to better time entries and size positions.
Evaluate strategy on more products to test adaptiveness.
Summary
The Bollinger Bands breakout strategy provides a simple trend-following approach by riding momentum signaled by indicator-based breakouts. Its strength lies in the dynamic identification of trend continuations. Proper risk controls and robustness enhancements can turn improve it into a viable systematic strategy.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_int_1 | 20 | Bollinger Bands Length |
| v_input_string_1 | 0 | Basis MA Type: SMA | EMA | SMMA (RMA) | WMA | VWMA |
| v_input_1_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_float_1 | 2 | StdDev Multiplier |
| v_input_int_2 | false | Offset |
Source Pine Script
/*backtest
start: 2024-01-20 00:00:00
end: 2024-02-19 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Bollinger Bands Strategy", overlay=true)

length = input.int(20, title="Bollinger Bands Length", minval=1)
maType = input.string("SMA", title="Basis MA Type", options=["SMA", "EMA", "SMMA (RMA)", "WMA", "VWMA"])
src = input(close, title="Source")
mult = input.float(2.0, title="StdDev Multiplier", minval=0.001, maxval=50)
offset = input.int(0, title="Offset", minval=-500, maxval=500)

ma(source, length, _type) =>
    switch _type
        "SMA" => ta.sma(source, length)
        "EMA" => ta.ema(source, length)
        "SMMA (RMA)" => ta.rma(source, length)
        "WMA" => ta.wma(source, length)
        "VWMA" => ta.vwma(source, length)

basis = ma(src, length, maType)
dev = mult * ta.stdev(src, length)
upper = basis + dev + offset
lower = basis - dev - offset

// Define strategy entry and exit conditions
strategy.entry("Buy", strategy.long, when=close < lower)
strategy.close("Buy", when=close > upper)

strategy.entry("Sell", strategy.short, when=close > upper)
strategy.close("Sell", when=close < lower)

// Plotting the Bollinger Bands
plot(basis, color=color.blue, title="Basis")
plot(upper, color=color.red, title="Upper Band")
plot(lower, color=color.green, title="Lower Band")
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-20. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Bollinger-Bands-Breakout-Strategy-442259.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Dynamic Bollinger Bands Breakout Quantitative Trading StrategyPine Script · Breakout · 2d
- Momentum Breakout Moving Average StrategyPine Script · Breakout · 1d
- Momentum Breakout Trading Strategy 435896Pine Script · Breakout · 1d
- Moving Average Crossover and Upper Rail Breakthrough Impulse StrategyPine Script · Breakout · 1m
- Multi factor Intelligent Trading StrategyPine Script · Breakout · 1d
- Enhanced Bollinger Breakout Quantitative Strategy with Momentum Filter Integration SystemPine Script · Breakout · 2d