Bollinger Bands Breakout Trading Strategy
This strategy is designed based on the Bollinger Bands indicator. It goes long when the price breaks through the upper band and goes short when the price breaks through the lower band. It belongs to the trend…
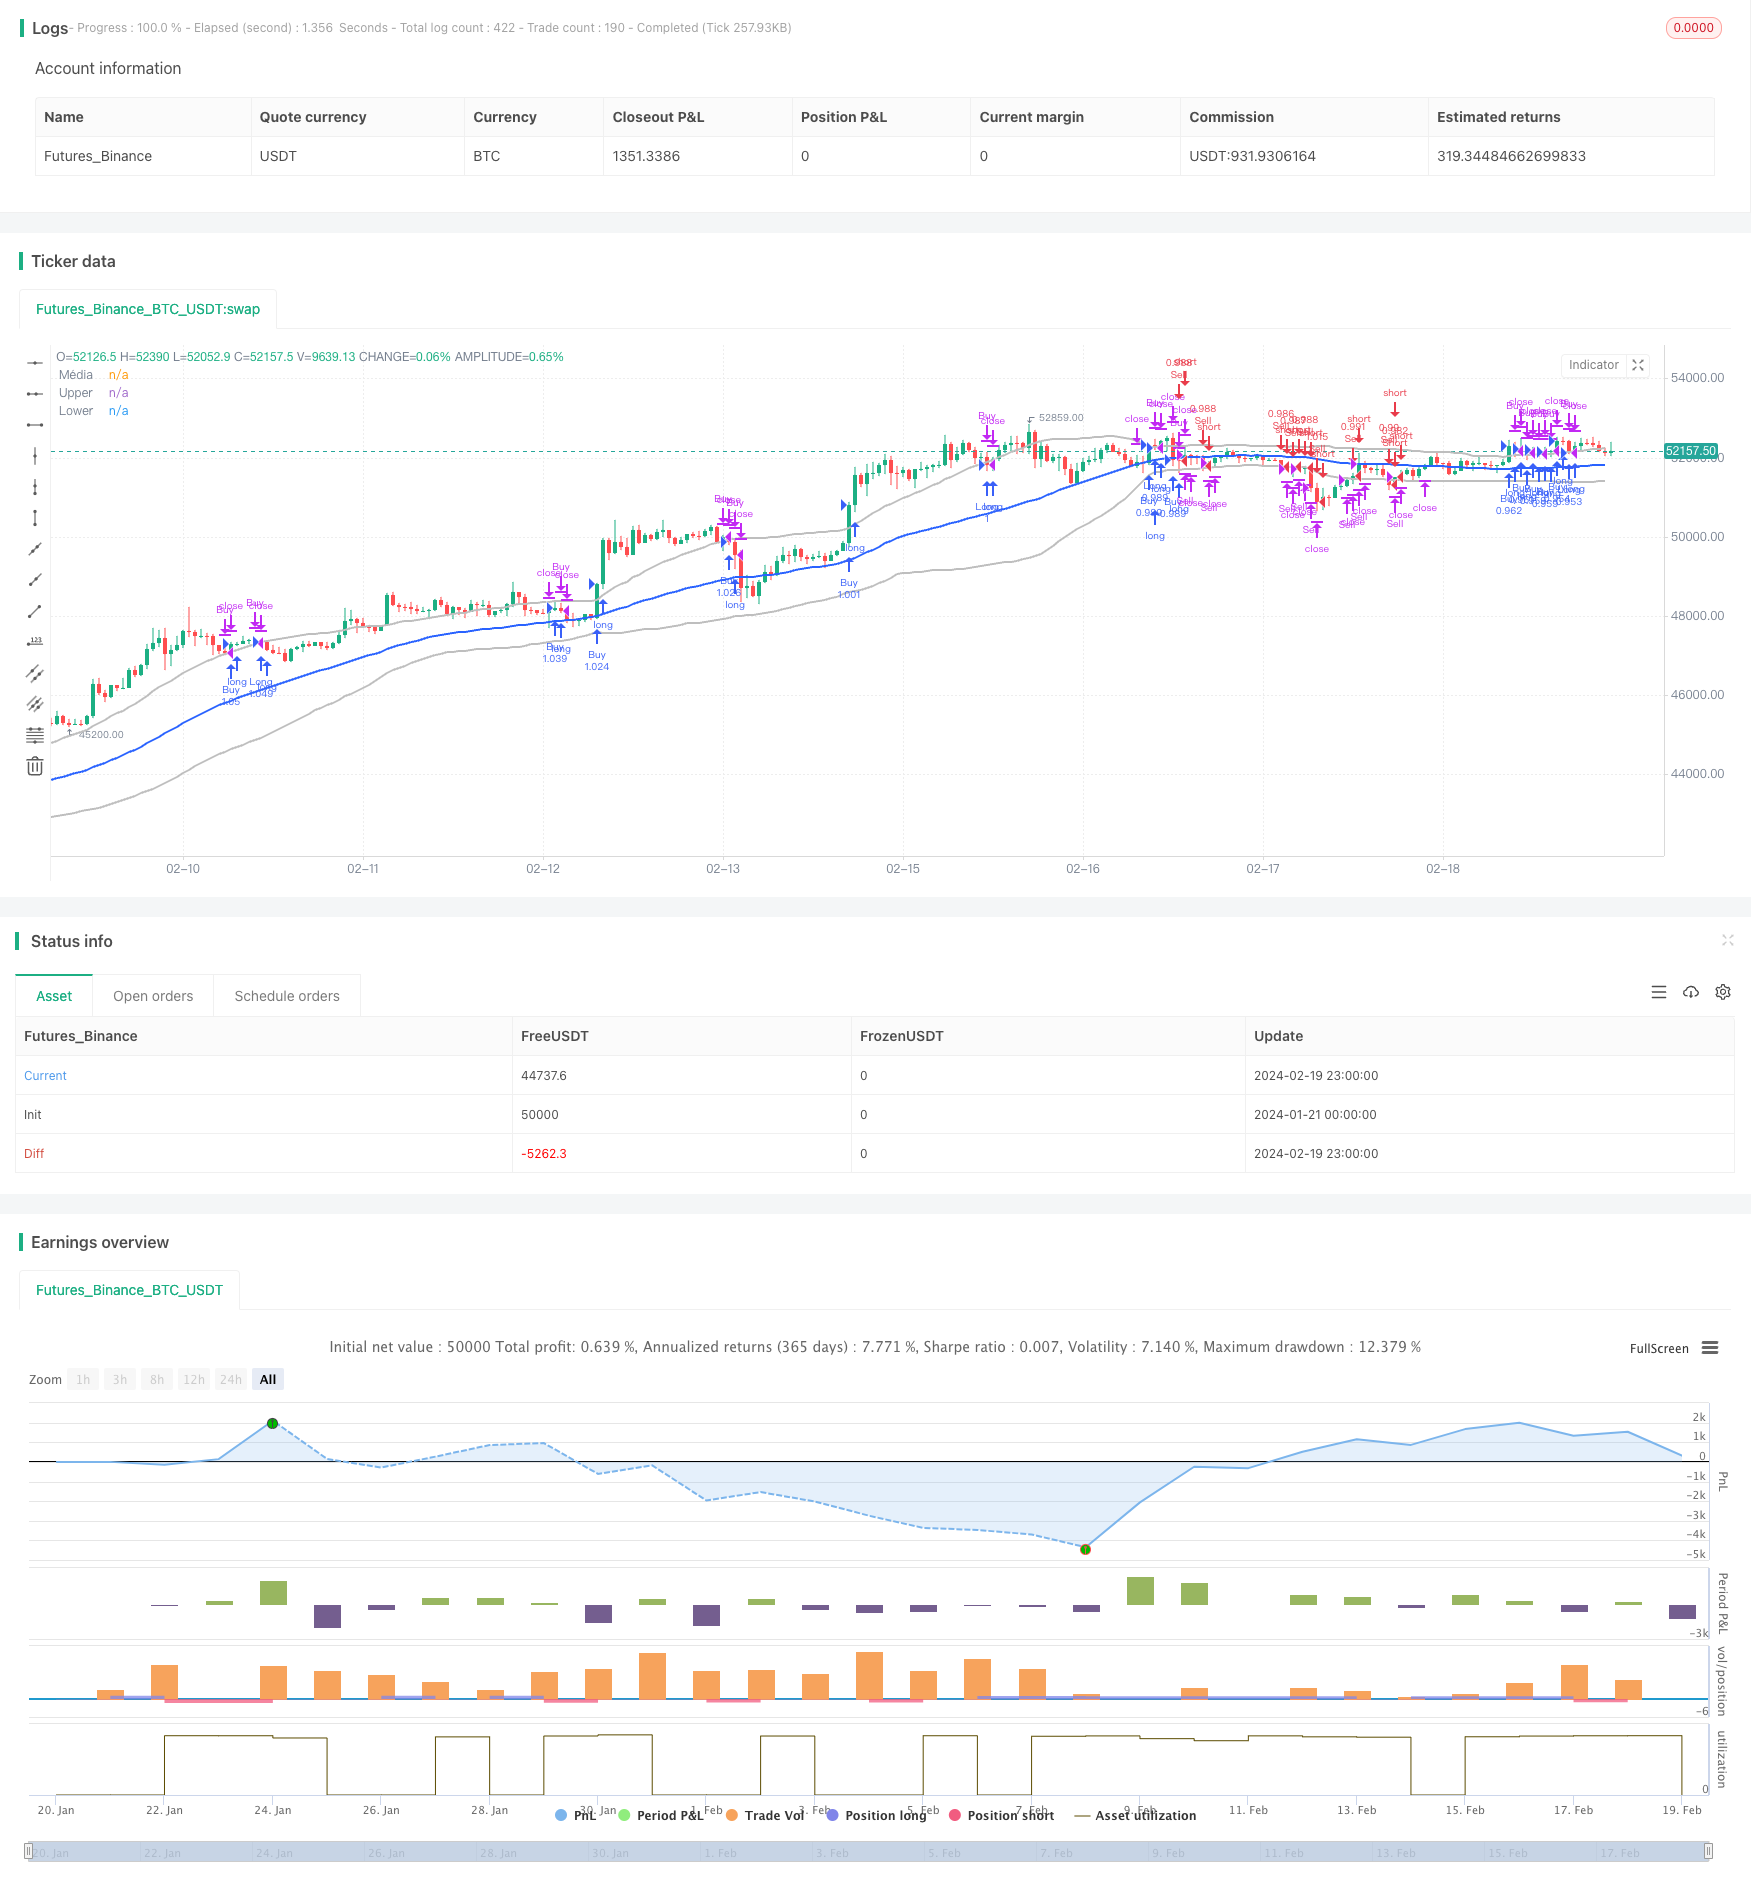
Overview
This strategy is designed based on the Bollinger Bands indicator. It goes long when the price breaks through the upper band and goes short when the price breaks through the lower band. It belongs to the trend following strategy.
Strategy Logic
- Calculate the middle band, upper band and lower band of Bollinger Bands
- When the closing price breaks through the upper band, go long
- When the closing price breaks through the lower band, go short
- Exit rule: close long position when price breaks through middle band, close short position when price breaks through middle band
This strategy uses Bollinger Bands to determine the fluctuation range and trend direction of the market. When the price breaks through the upper or lower bands of Bollinger Bands, it is considered as a trend reversal signal for entry. The area around the middle band is used as the stop loss position. Exit positions when the price breaks through the middle band.
Advantage Analysis
- Use Bollinger Bands indicator to determine market trend and support/resistance levels
- High probability when breakout of Bollinger Bands
- Clear entry and exit rules
Risk Analysis
- Risk of false breakout signals from Bollinger Bands, which could be short-term price fluctuations
- Larger stop loss when huge price swings
Solutions:
- Combine with other indicators to confirm the trend
- Adjust parameters to expand Bollinger Bands range
Optimization Directions
- Combine with trend indicators to avoid unnecessary reverse trading
- Dynamically adjust Bollinger Bands parameters to optimize parameter size
Summary
This strategy uses the Bollinger Bands indicator to determine price trend and support/resistance levels. It enters at Bollinger Bands breakout points and sets stop loss at the middle band. The strategy logic is simple and clear, easy to implement. It can be optimized by adjusting parameters or combining with other indicators, works well in trending markets.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_int_1 | true | From Month |
| v_input_int_2 | true | From Day |
| v_input_int_3 | 1972 | From Year |
| v_input_int_4 | true | To Month |
| v_input_int_5 | true | To Day |
| v_input_int_6 | 9999 | To Year |
| v_input_int_7 | 51 | Comprimento |
| v_input_float_1 | 1.1 | Multiplicador |
Source Pine Script
/*backtest
start: 2024-01-21 00:00:00
end: 2024-02-20 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("FFFDBTC", overlay=true,initial_capital = 100,commission_type =strategy.commission.percent,commission_value= 0.15,default_qty_value = 100,default_qty_type = strategy.percent_of_equity)
// === INPUT BACKTEST RANGE ===
FromMonth = input.int(defval=1, title="From Month", minval=1, maxval=12)
FromDay = input.int(defval=1, title="From Day", minval=1, maxval=31)
FromYear = input.int(defval=1972, title="From Year", minval=1972)
ToMonth = input.int(defval=1, title="To Month", minval=1, maxval=12)
ToDay = input.int(defval=1, title="To Day", minval=1, maxval=31)
ToYear = input.int(defval=9999, title="To Year", minval=2010)

// === FUNCTION EXAMPLE ===
start = timestamp(FromYear, FromMonth, FromDay, 00, 00)  // backtest start window
finish = timestamp(ToYear, ToMonth, ToDay, 23, 59)  // backtest finish window
window() => true
// Definindo tamanho da posição
position_size = strategy.equity
// Definir parâmetros das Bandas de Bollinger
length = input.int(51, "Comprimento")
mult = input.float(1.1, "Multiplicador")

// Calcular as Bandas de Bollinger
basis = ta.sma(close, length)
dev = mult * ta.stdev(close, length)
upper = basis + dev
lower = basis - dev
// Definir condições de entrada e saída
entrada_na_venda = low < lower
saida_da_venda = high > lower and strategy.position_size < 0
entrada_na_compra = high > upper
saida_da_compra = low < upper and strategy.position_size > 0
shortCondition = close[1] < lower[1] and close > lower and close < basis
longCondition = close[1] > upper[1] and close < upper and close > basis

// Entrar na posição longa se a condição longCondition for verdadeira
if ((entrada_na_compra) and window() )
    strategy.entry("Buy", strategy.long)
//saida da compra
if (saida_da_compra)
    strategy.close("Buy")
//entrada na venda
if ((entrada_na_venda) and window() )
    strategy.entry("Sell", strategy.short)
//saida da venda
if (saida_da_venda)
    strategy.close("Sell")
if ((longCondition) and window())
    strategy.entry("Long", strategy.long)

// Entrar na posição curta se a condição shortCondition for verdadeira
if ((shortCondition) and window())
    strategy.entry("Short", strategy.short)

// Definir a saída da posição

strategy.exit("Exit_Long", "Long", stop=ta.sma(close, length), when = close >= basis)
strategy.exit("Exit_Short", "Short", stop=ta.sma(close, length), when = close <= basis)

// Desenhar as Bandas de Bollinger no gráfico
plot(basis, "Média", color=#2962FF, linewidth=2)
plot(upper, "Upper", color=#BEBEBE, linewidth=2)
plot(lower, "Lower", color=#BEBEBE, linewidth=2)Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-21. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Bollinger-Bands-Breakout-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bollinger Bands Dynamic Breakout StrategyPine Script · Breakout · 1h
- Momentum Breakout Moving Average StrategyPine Script · Breakout · 1d
- Moving Average Crossover and Upper Rail Breakthrough Impulse StrategyPine Script · Breakout · 1m
- Moving Average Support and Resistance Breakout StrategyPine Script · Breakout · 1d
- Multi factor Intelligent Trading StrategyPine Script · Breakout · 1d
- Pivot Point Detection with Bollinger Band Oscillation StrategyPine Script · Breakout · 1h