Breakout Pullback Strategy
The breakout pullback strategy is a trend following strategy. Its basic principle is to go long or short when the price breaks through the high or low of the previous candlestick and let the profit continue to run…
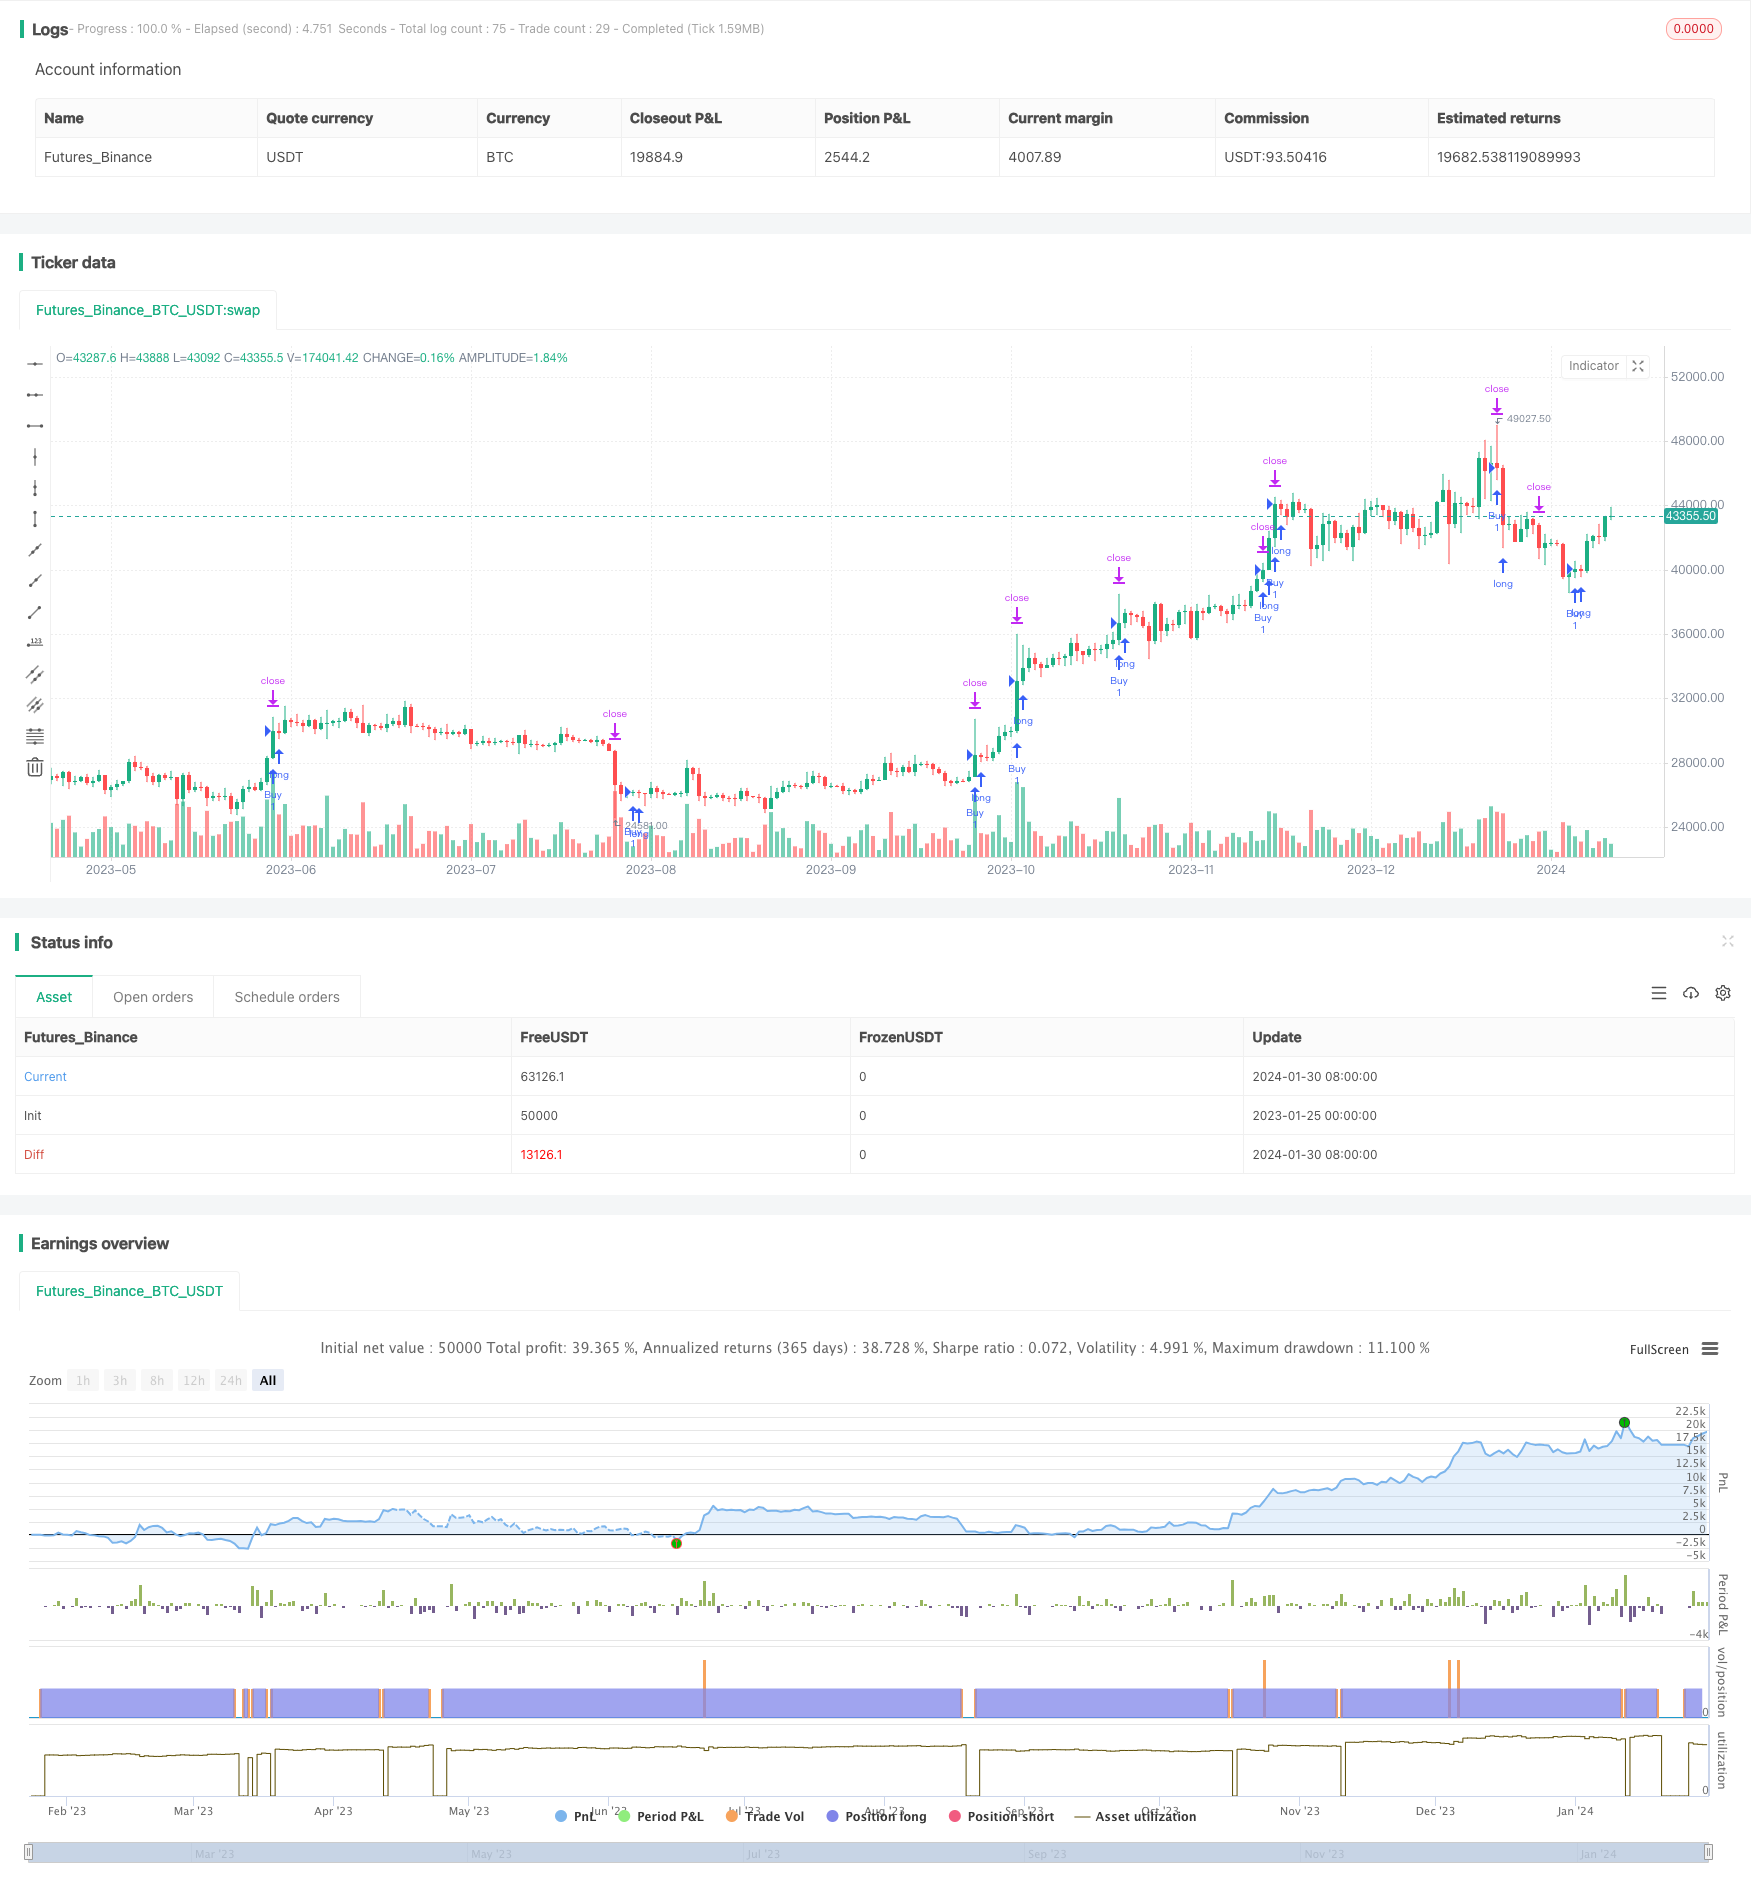
Overview
The breakout pullback strategy is a trend following strategy. Its basic principle is to go long or short when the price breaks through the high or low of the previous candlestick and let the profit continue to run after setting the take profit and stop loss.
Strategy Logic
The core logic of this strategy is to determine the entry timing by judging whether the price breaks through the high or low of the previous candlestick. The specific logic is:
If the high of the current candlestick is higher than the high of the previous candlestick, a long signal is triggered.
If the low of the current candlestick is lower than the low of the previous candlestick, a short signal is triggered.
Once receiving the long or short signal, enter the position immediately. After entering the position, set the take profit to 50 pips and stop loss to 100 pips.
When the loss is greater than or equal to the stop loss pips or profit is greater than or equal to the take profit pips, exit the position actively.
Advantage Analysis
This breakout pullback strategy has the following advantages:
- The logic is simple and easy to implement.
- It can effectively capture the beginning of trends and enter positions in a timely manner.
- Setting take profit and stop loss allows profits to continue to run, avoiding premature exits.
- Good ability of controlling drawdowns and risks.
Risk Analysis
This strategy also has some risks:
- Breakout signals may be false breakouts, causing wrong entries.
- It is easy to be trapped in range-bound consolidate markets.
- Reasonable take profit and stop loss pips should be set to control risks.
Optimization Directions
The strategy can be further optimized in the following aspects:
Add validity check for price breakouts to avoid false breakouts, such as using indicators filters and volume confirmation.
Add trend determination mechanism to avoid trapping risks in range-bound markets. Moving average and other trend indicators can be used.
Optimize take profit and stop loss strategy, such as trailing stop loss, moving stop loss after profit, etc, to maximize profits.
Parameter optimization to find the optimal take profit and stop loss pips.
Conclusion
In general, this breakout pullback strategy has the advantage of simple logic, easy implementation, and effectively capturing trend starts. It also has good ability of controlling risks and drawdowns. With further optimizations, it can become a very practical quant strategy.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 50 | Take Profit (in pips) |
| v_input_2 | 100 | Stop Loss (in pips) |
Source Pine Script
/*backtest
start: 2023-01-25 00:00:00
end: 2024-01-31 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Breakout Strategy", shorttitle="BS", overlay=true)

// Input for take profit and stop loss in pips
tp_pips = input(50, title="Take Profit (in pips)")
sl_pips = input(100, title="Stop Loss (in pips)")

// Calculate take profit and stop loss levels in points
tp_level = tp_pips * syminfo.mintick
sl_level = sl_pips * syminfo.mintick

// Function to check if a breakout has occurred
breakout(high_or_low) =>
    high_or_low > request.security(syminfo.tickerid, "D", high[1]) ? true : false

// Buy condition
buy_condition = breakout(high)
strategy.entry("Buy", strategy.long, when=buy_condition)

// Sell condition
sell_condition = breakout(low)
strategy.entry("Sell", strategy.short, when=sell_condition)

// Take profit and stop loss conditions for Buy
tp_buy_condition = strategy.position_avg_price + tp_level
sl_buy_condition = strategy.position_avg_price - sl_level
strategy.exit("Take Profit/Close Buy", from_entry="Buy", profit=tp_buy_condition, loss=sl_buy_condition)

// Take profit and stop loss conditions for Sell
tp_sell_condition = strategy.position_avg_price - tp_level
sl_sell_condition = strategy.position_avg_price + sl_level
strategy.exit("Take Profit/Close Sell", from_entry="Sell", profit=tp_sell_condition, loss=sl_sell_condition)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-01. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Breakout-Pullback-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive Multi Period Trading Strategy Based on Wave Trend Momentum BreakoutPine Script · Breakout · 2h
- Advanced Multi Pattern Breakout Trading StrategyPine Script · Breakout · 1d
- Dual Thrust StrategyPine Script · Breakout · 10m
- Dynamic Bollinger Bands Breakout Quantitative Trading StrategyPine Script · Breakout · 2d
- Dynamic Dual Moving Average Breakthrough Trading System Dynamic Dual Moving Average Breakthrough Trading SystemPine Script · Breakout · 1d
- Flexible Long Short Trading Strategy Based on Keltner ChannelsPine Script · Breakout · 1d