Strategy vault / Mean reversion
Combined Momentum and Mean Reversion High Frequency Quantitative Strategy
This strategy is a high-frequency quantitative trading system that combines momentum trading and mean reversion approaches. Operating on a 5-minute timeframe, it captures trending opportunities using Exponential…
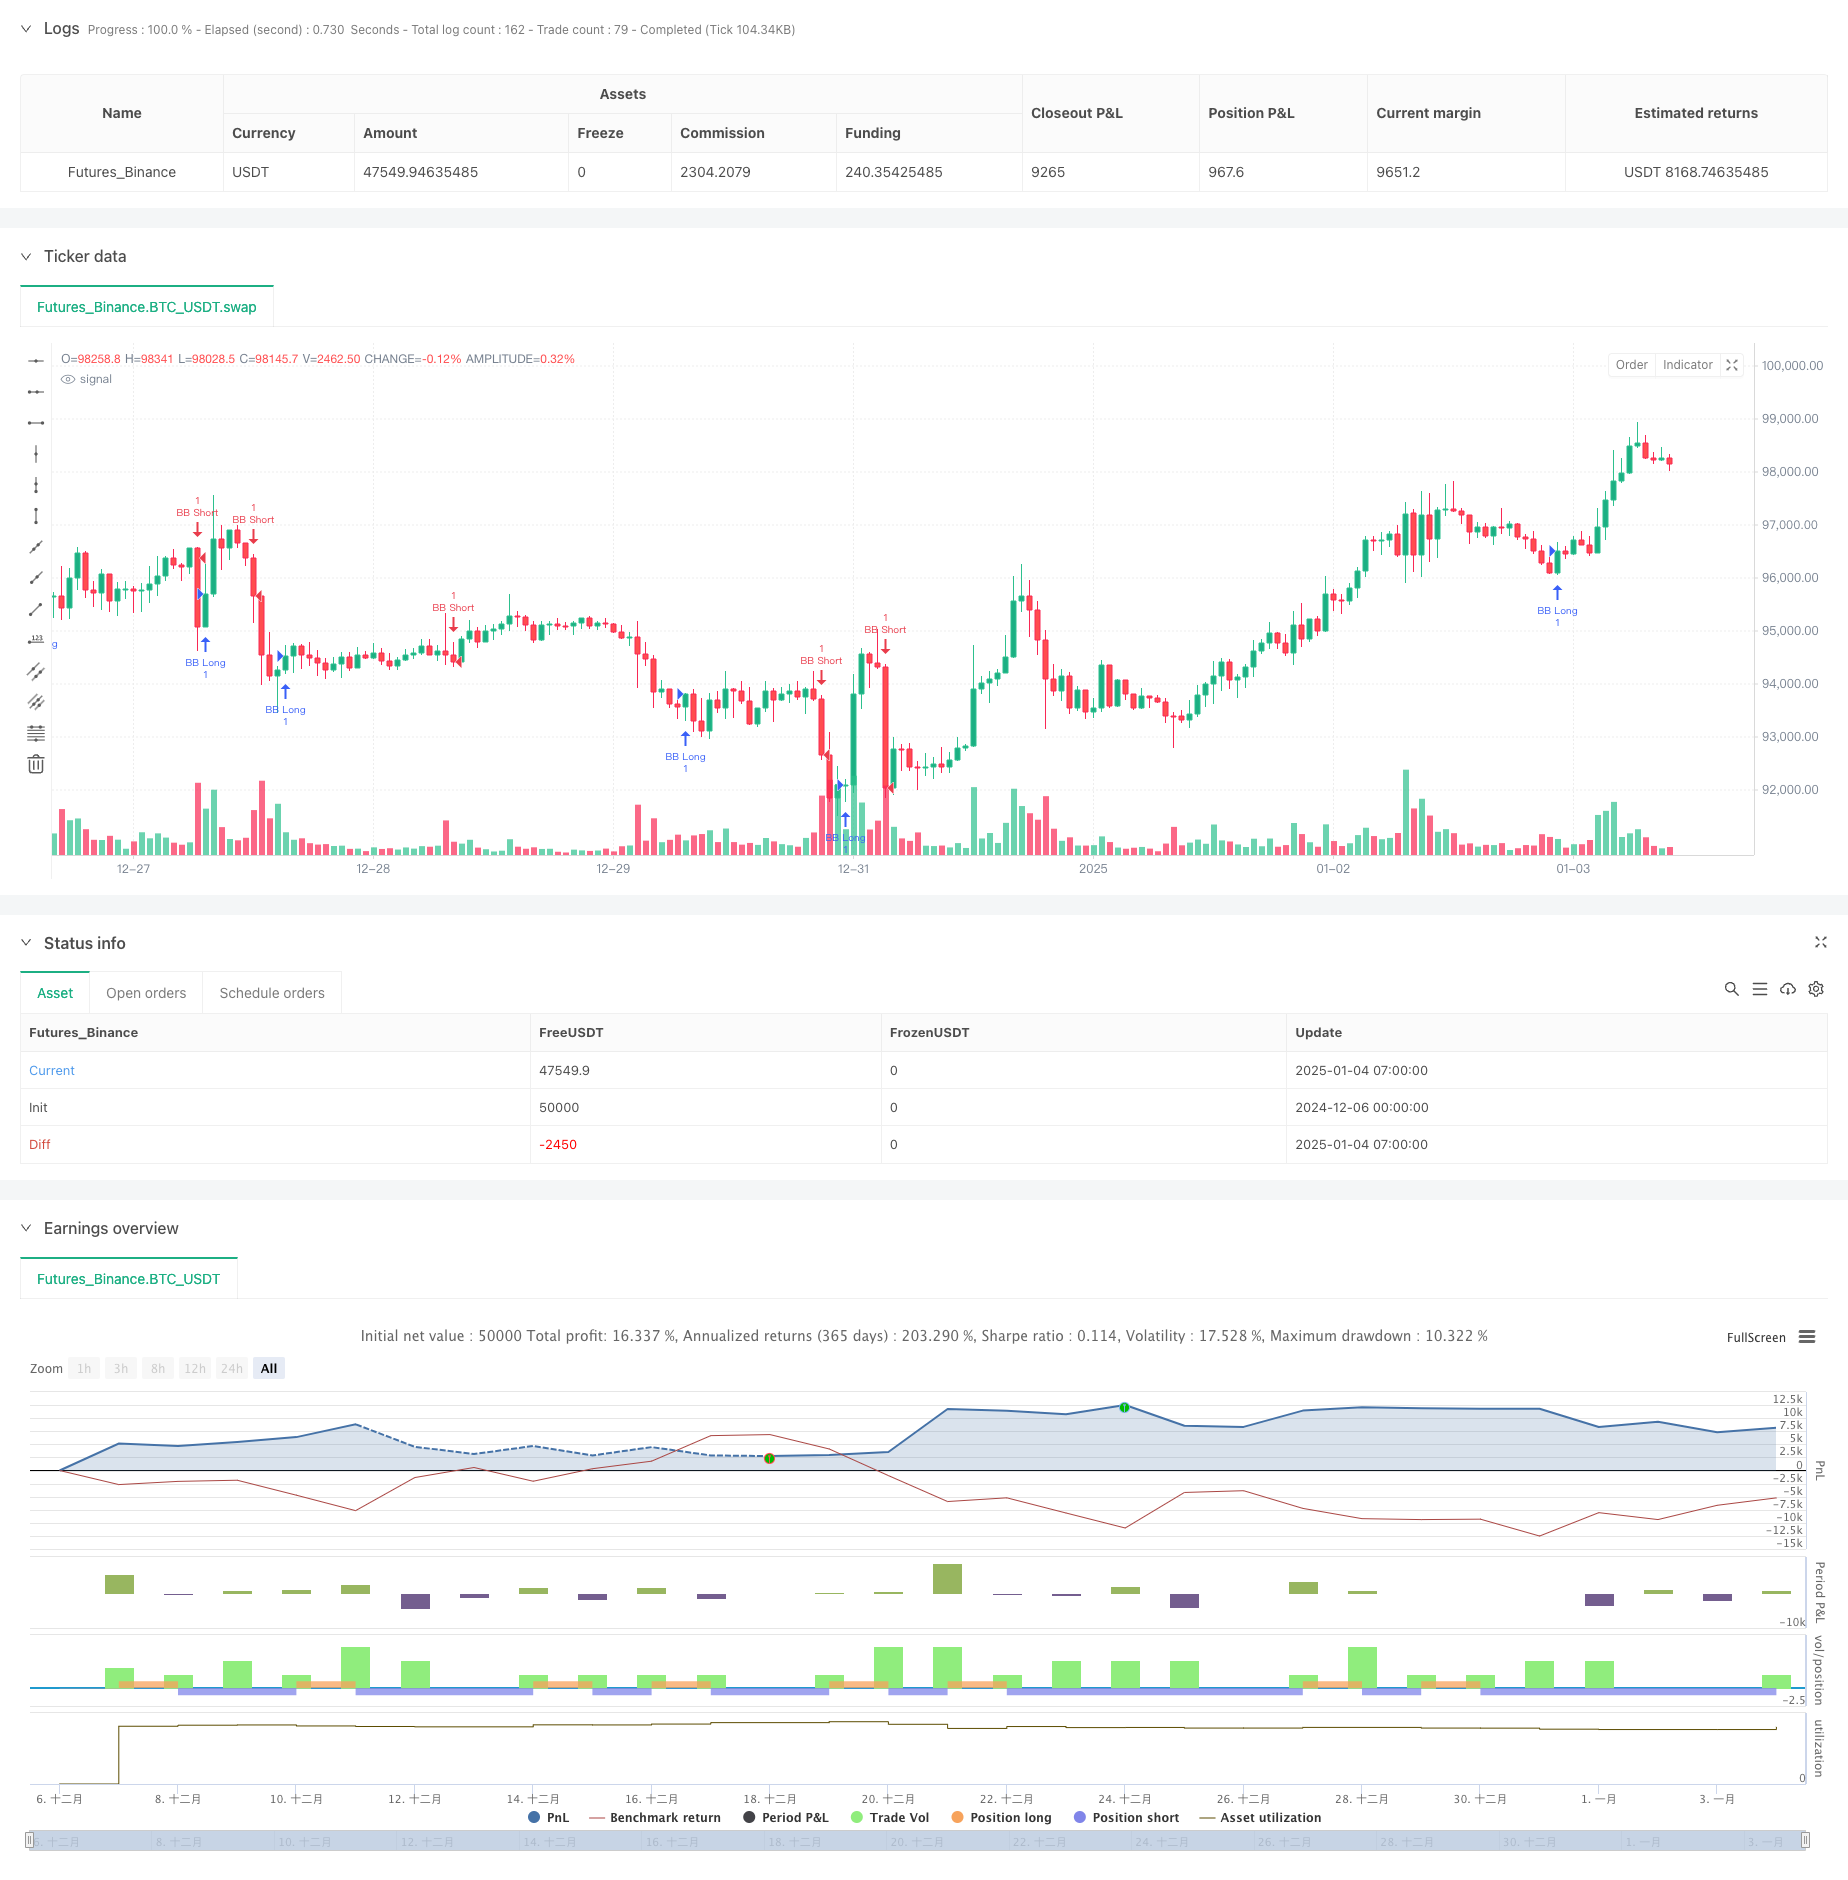
Overview
This strategy is a high-frequency quantitative trading system that combines momentum trading and mean reversion approaches. Operating on a 5-minute timeframe, it captures trending opportunities using Exponential Moving Averages (EMA) while identifying overbought and oversold conditions through Bollinger Bands. The strategy features flexible parameter configuration, allowing for single or combined trading modes based on market conditions.
Strategy Principle
The strategy employs a dual-layer trading logic:
- The momentum component uses crossovers between short-term (50-period) and long-term (400-period) EMAs to determine trends. Buy signals are generated when the short EMA crosses above the long EMA, and sell signals when it crosses below.
- The mean reversion component uses Bollinger Bands (20-period, 2 standard deviations) to capture price deviations. Buy signals occur when price breaks below the lower band, and sell signals when it breaks above the upper band.
- Both trading modules can be enabled or disabled independently, allowing for flexible strategy switching.
Strategy Advantages
- Complementary dual logic: Momentum strategy excels in trending markets, while mean reversion performs well in ranging markets, combining to adapt to various market conditions.
- Strong parameter adaptability: EMA periods and Bollinger Band parameters can be optimized based on market characteristics.
- Reasonable risk control: Using technical indicator crossovers and breakouts as trading signals helps avoid false signals from single indicators.
- High execution efficiency: Strategy logic is clear and concise, suitable for high-frequency trading environments.
Strategy Risks
- Signal lag: Both EMA and Bollinger Bands are lagging indicators, potentially missing optimal entry points in rapidly moving markets.
- False breakout risk: Volatile periods may generate false Bollinger Band breakout signals.
- Parameter sensitivity: Strategy performance is highly dependent on parameter selection, requiring continuous optimization.
Optimization Directions
- Implement volatility filters: Calculate historical volatility to adjust Bollinger Band parameters or pause trading during high volatility periods.
- Add volume confirmation: Incorporate volume data to verify breakout validity and improve signal quality.
- Develop adaptive parameters: Dynamically adjust EMA periods and Bollinger Band parameters based on market conditions.
- Build stop-loss mechanisms: Design more comprehensive stop-loss strategies to control drawdown risk.
Summary
The strategy combines momentum and mean reversion methods to create a highly adaptable, risk-controlled high-frequency quantitative trading system. Its modular design and parameter flexibility provide practical value, and with continuous optimization and risk management improvements, it shows promise for generating stable returns in live trading.
Source Pine Script
/*backtest
start: 2024-12-06 00:00:00
end: 2025-01-04 08:00:00
period: 1h
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Momentum and Mean Reversion Strategy", shorttitle = "MMV_V1", overlay=true)

// --- Inputit ja parametrit ---
use_momentum = input.bool(true, title="Käytä Momentum-strategiaa")
use_mean_reversion = input.bool(true, title="Käytä Keskiarvoon Palautumista (BB)")

// Momentum-parametrit
short_ema_period = input.int(50, title="Lyhyt EMA")
long_ema_period = input.int(400, title="Pitkä EMA")

// Bollinger Band -parametrit
bb_length = input.int(20, title="BB Pituus")
bb_std = input.float(2.0, title="BB Standardipoikkeama")

// --- Momentum-strategia: EMA-risteämä ---
short_ema = ta.ema(close, short_ema_period)
long_ema = ta.ema(close, long_ema_period)

momentum_long_signal = ta.crossover(short_ema, long_ema)
momentum_short_signal = ta.crossunder(short_ema, long_ema)

// --- Keskiarvoon palautuminen: Bollinger Bands ---
[bb_upper, bb_middle, bb_lower] = ta.bb(close, bb_length, bb_std)

bb_long_signal = ta.crossover(close, bb_lower)  // Osto, kun hinta nousee alemman BB:n yli
bb_short_signal = ta.crossunder(close, bb_upper)  // Myynti, kun hinta laskee ylemmän BB:n ali

// --- Kaupankäyntilogiikka ---
if (use_momentum and momentum_long_signal)
    strategy.entry("Momentum Long", strategy.long)

if (use_momentum and momentum_short_signal)
    strategy.entry("Momentum Short", strategy.short)

if (use_mean_reversion and bb_long_signal)
    strategy.entry("BB Long", strategy.long)

if (use_mean_reversion and bb_short_signal)
    strategy.entry("BB Short", strategy.short)
Published by ChaoZhang on the FMZ strategy square · last modified 2025-01-06. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Combined-Momentum-and-Mean-Reversion-High-Frequency-Quantitative-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- Advanced Momentum EMA Trend Following with RSI Overbought Oversold Trading StrategyPine Script · Mean reversion · 1d
- Advanced Quantitative Trading Strategy Combining RSI Divergence and Moving AveragesPine Script · Mean reversion · 1h
- Dual Moving Average Line Capture StrategyPine Script · Mean reversion · 15m
- Dynamic Adaptive Multi Timeframe Trend Following and Range Reversal Hybrid StrategyPine Script · Mean reversion · 2d
- Enhanced Bollinger Mean Reversion Quantitative StrategyPine Script · Mean reversion · 1d