Strategy vault / Mean reversion
Enhanced Bollinger Mean Reversion Quantitative Strategy
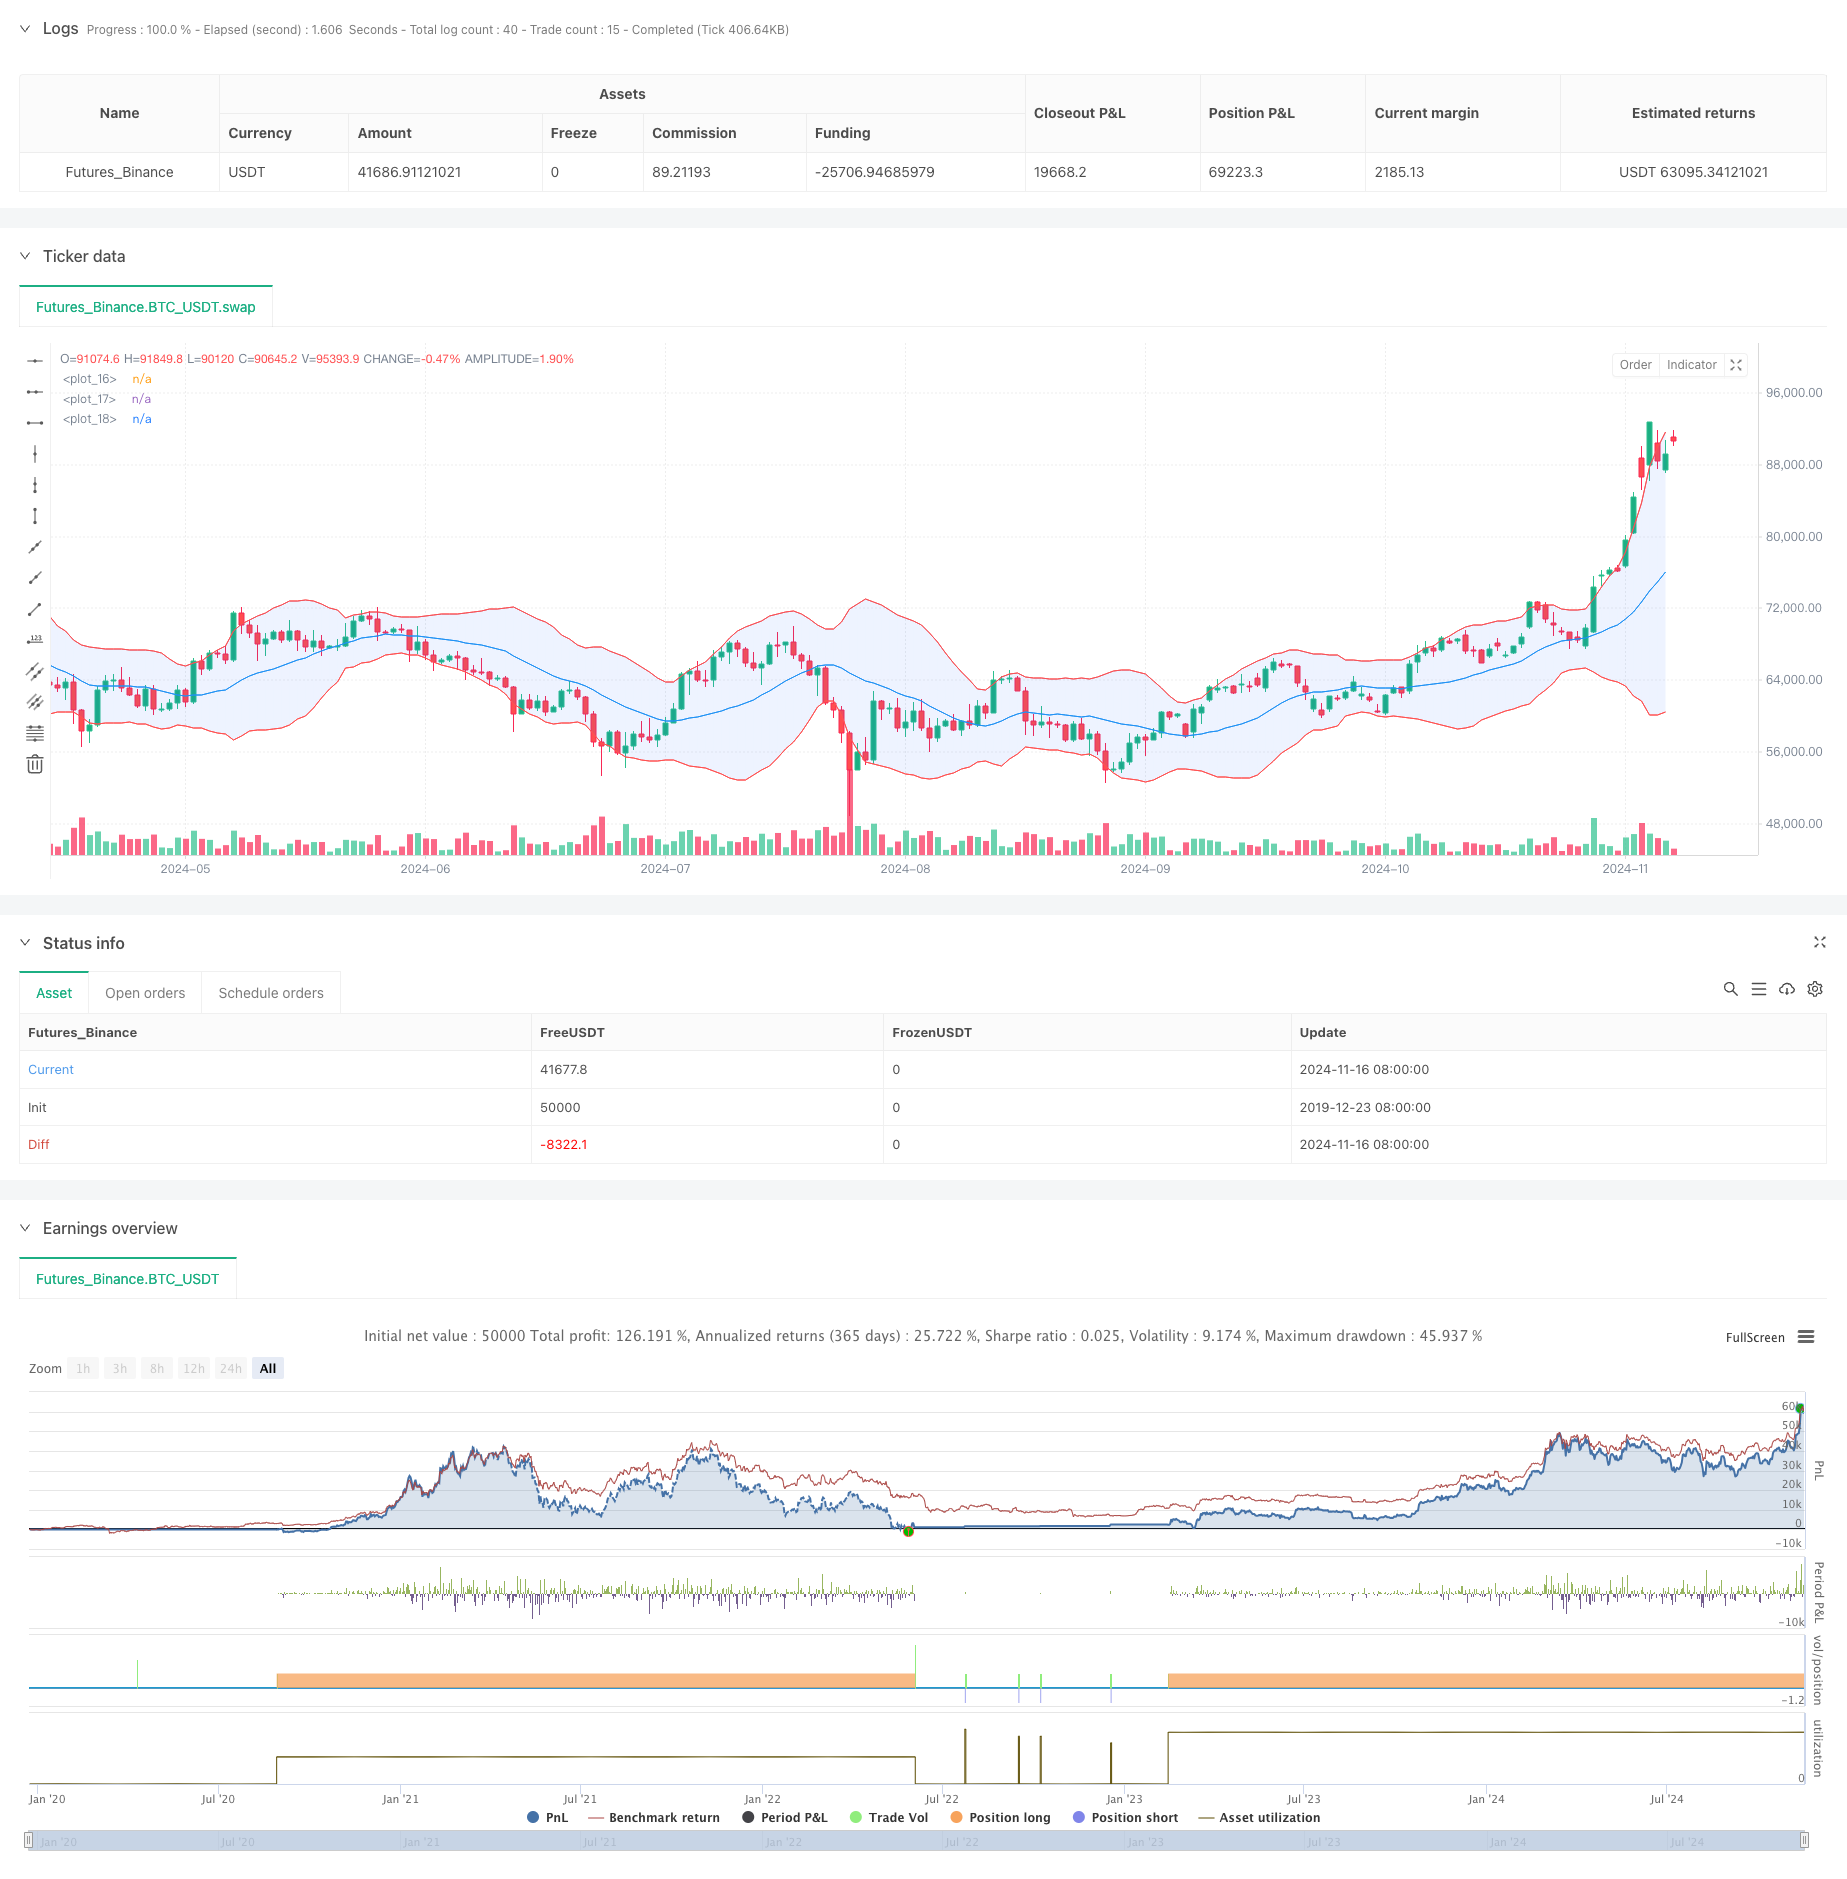
This strategy is a mean reversion trading system based on Bollinger Bands, optimized with trend filters and dynamic stop-loss mechanisms. It applies statistical principles to trade price deviations from the mean…
Overview
This strategy is a mean reversion trading system based on Bollinger Bands, optimized with trend filters and dynamic stop-loss mechanisms. It applies statistical principles to trade price deviations from the mean while using technical indicators to improve win rates and manage risks.
Strategy Principles
The strategy is built on several key components:
- Uses 20-period Bollinger Bands as the primary signal source with 2 standard deviation bandwidth
- Incorporates 50-period EMA as a trend filter to ensure trade direction aligns with medium-term trends
- Employs 14-period ATR for dynamic stop-loss and profit targets to improve risk-reward ratios
- Enters long when price touches lower band and is above EMA, shorts when price touches upper band and is below EMA
- Sets profit target at 2x ATR and stop-loss at 1x ATR
Strategy Advantages
- Combines benefits of mean reversion and trend following for improved reliability
- Dynamic stop-loss and profit targets adapt to market volatility
- Clear entry and exit rules minimize subjective judgment
- Fixed 2:1 risk-reward ratio promotes long-term profitability
- Technical indicator combination reduces false signals
Strategy Risks
- May miss major trends in strongly trending markets
- Frequent trading possible in narrow consolidation ranges
- Slippage risk during market gaps
- Requires ongoing parameter monitoring and adjustment
- Trading costs may impact strategy returns
Optimization Directions
- Add volume indicators for confirmation
- Implement volatility filters to avoid high volatility periods
- Optimize parameter adaptation mechanisms
- Include additional technical indicators for cross-validation
- Enhance money management system
Summary
This strategy combines classical technical analysis with modern quantitative methods. Through multiple indicator confirmations and strict risk control, the strategy demonstrates good practicality. Thorough backtesting and demo trading are recommended before live implementation.
Source Pine Script
/*backtest
start: 2019-12-23 08:00:00
end: 2024-11-17 00:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=5
strategy("Optimized Bollinger Mean Reversion", overlay=true)

// Bollinger Band Settings
length = input.int(20, title="BB Length")
src = input(close, title="Source")
mult = input.float(2.0, title="BB Multiplier")

// Bollinger Bands Calculation
basis = ta.sma(src, length)
dev = mult * ta.stdev(src, length)
upper = basis + dev
lower = basis - dev

// Plot the Bollinger Bands
plot(basis, color=color.blue)
p1 = plot(upper, color=color.red)
p2 = plot(lower, color=color.red)
fill(p1, p2, color=color.rgb(41, 98, 255, 90))

// Trend Filter - 50 EMA
ema_filter = ta.ema(close, 50)

// ATR for Dynamic Stop Loss/Take Profit
atr_value = ta.atr(14)

// Buy condition - price touches lower band and above 50 EMA
buy_condition = ta.crossover(close, lower) and close > ema_filter

// Sell condition - price touches upper band and below 50 EMA
sell_condition = ta.crossunder(close, upper) and close < ema_filter

// Strategy Execution
if (buy_condition)
    strategy.entry("Buy", strategy.long)

if (sell_condition)
    strategy.entry("Sell", strategy.short)

// Exit with dynamic ATR-based stop loss and take profit
strategy.exit("Take Profit/Stop Loss", from_entry="Buy", limit=2*atr_value, stop=1*atr_value)
strategy.exit("Take Profit/Stop Loss", from_entry="Sell", limit=2*atr_value, stop=1*atr_value)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-11-18. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Enhanced-Bollinger-Mean-Reversion-Quantitative-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Reversal Trading Strategy with Bollinger Bands RSI ADX and ATRPine Script · Mean reversion · 1h
- CCTBBO Reversal Tracking StrategyPine Script · Mean reversion · 45m
- EMA Oscillation Reversal System StrategyPine Script · Mean reversion · 1d
- Bollinger Bands Trend Reversal StrategyPine Script · Mean reversion · 10m
- Dual Channel Tracking Reversal StrategyPine Script · Mean reversion · 1h
- MACD RSI and EMA StrategyPine Script · Mean reversion · 1d