Strategy vault / Mean reversion
Combo Strategy of Double Factors Reversal and Improved Price Volume Trend
This strategy combines double factors reversal and improved price volume trend sub-strategies to generate cumulative trading signals. The double factors reversal strategy is based on Ulf Jensen's idea on Page 183 of…
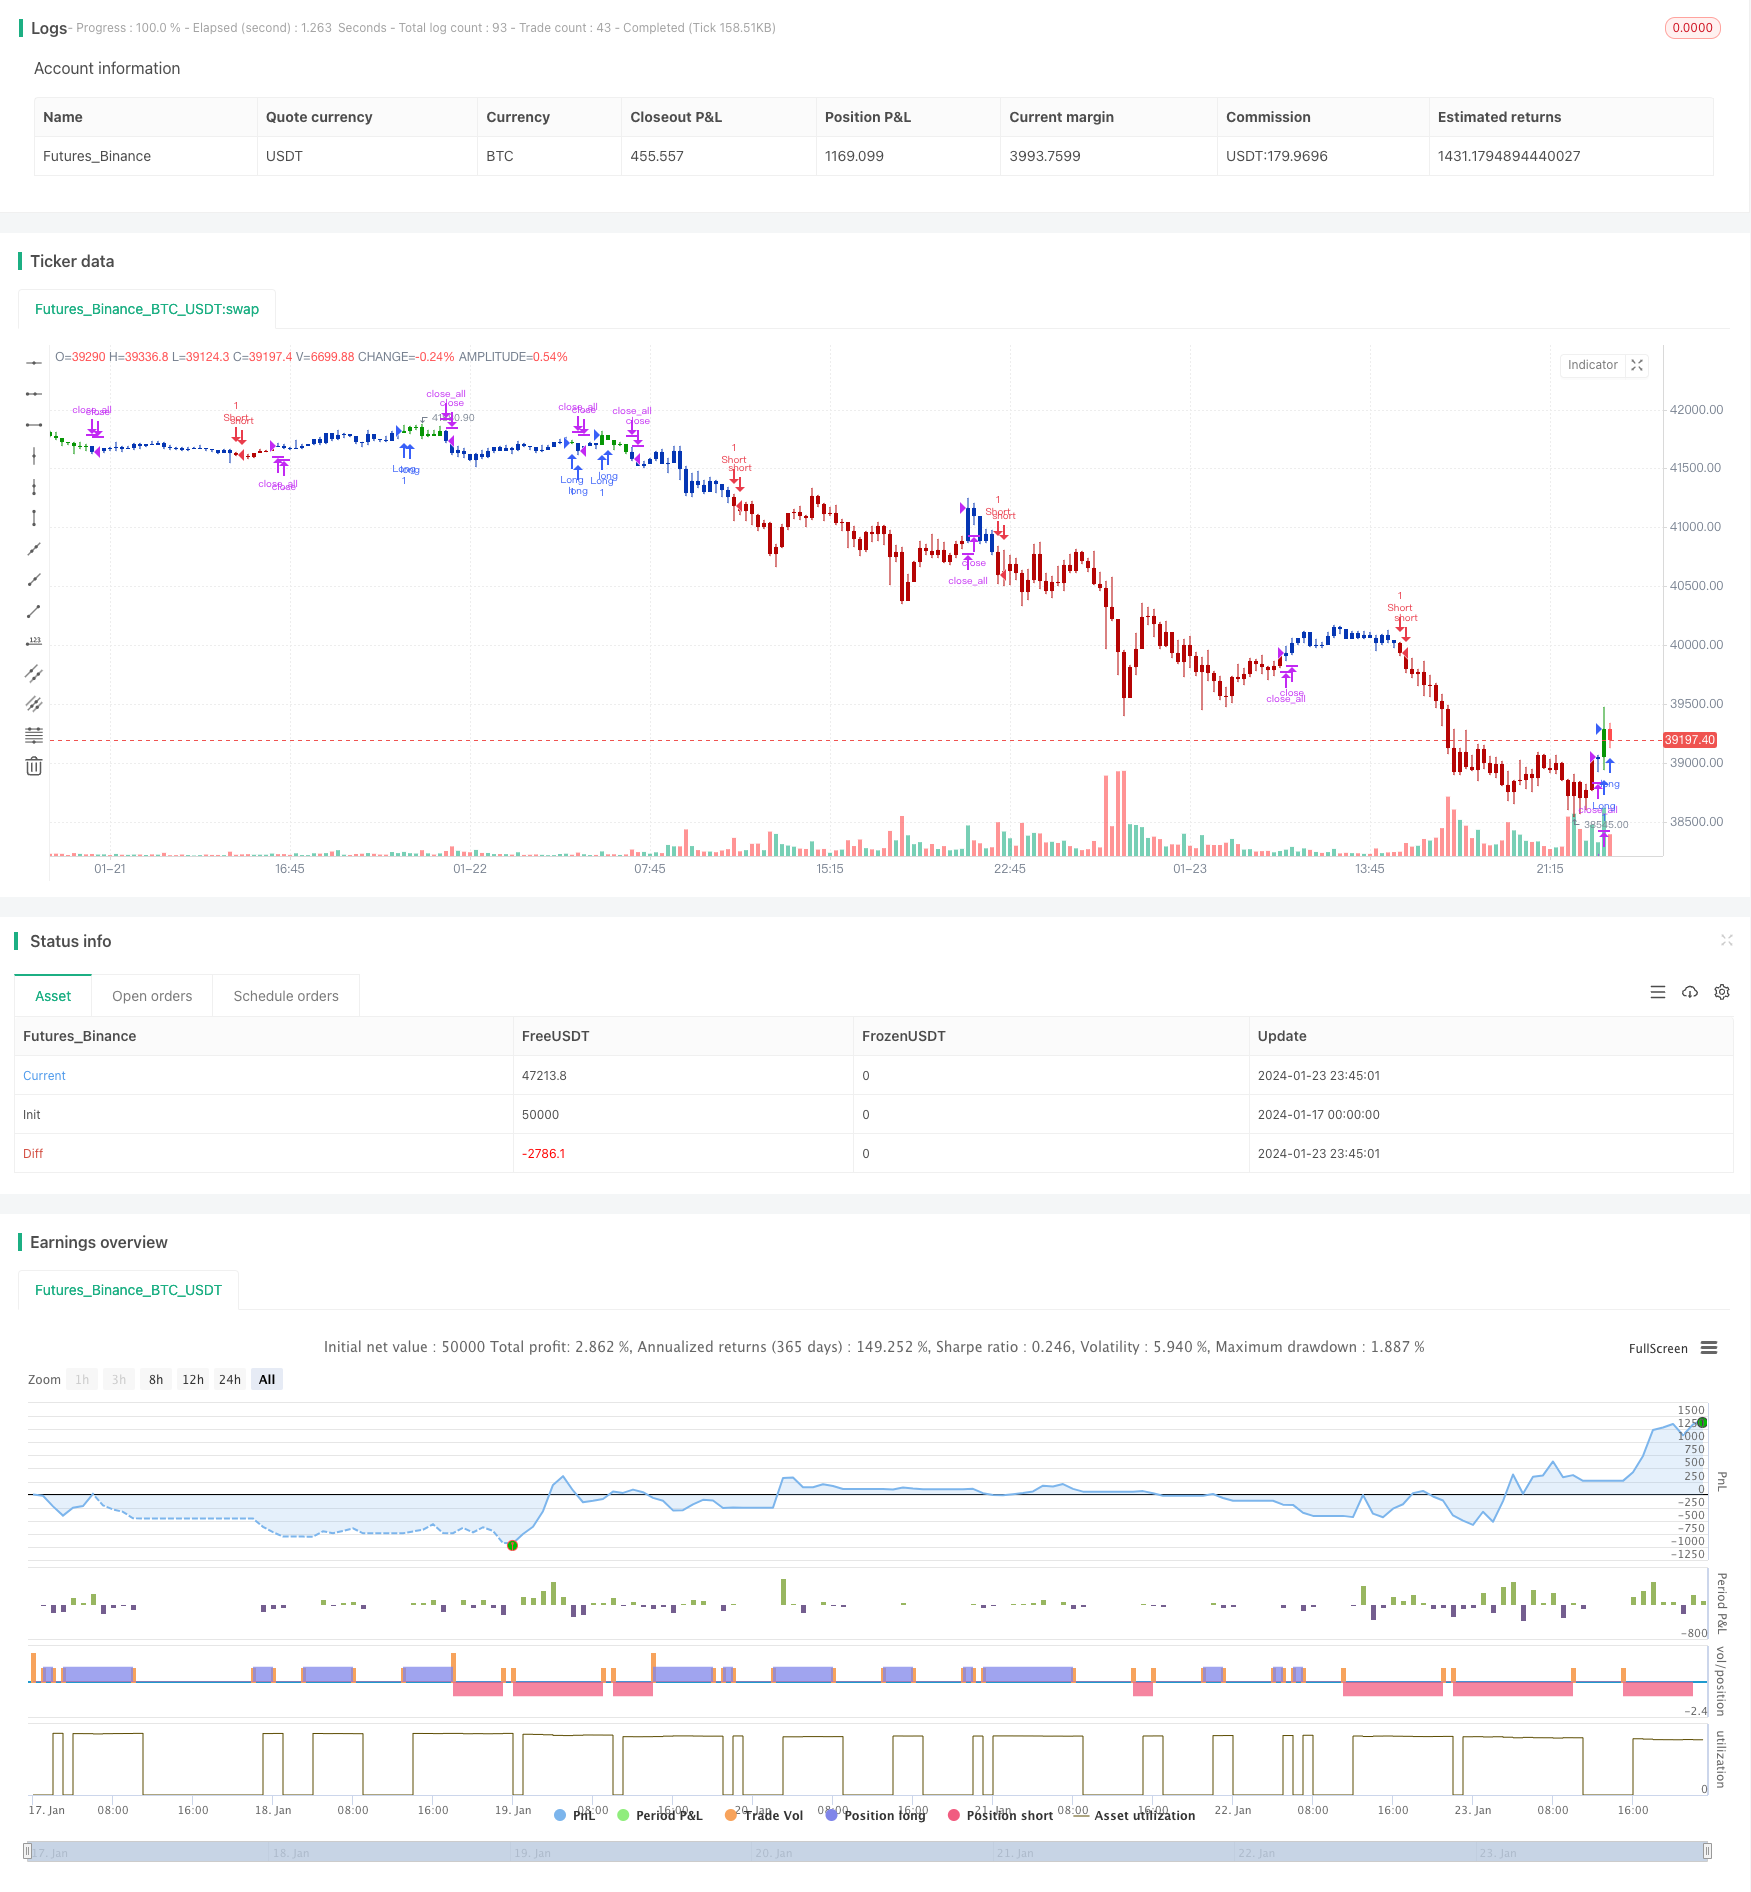
Overview
This strategy combines double factors reversal and improved price volume trend sub-strategies to generate cumulative trading signals. The double factors reversal strategy is based on Ulf Jensen's idea on Page 183 of his book, generating signals when stock prices reverse over two days and the stochastic indicator conditions are met. The improved price volume trend strategy follows the joint research of price and trading volume to judge the direction and momentum of the market. The two strategies can validate each other, and combined use can improve stability.
Strategy Principles
The double factors reversal sub-strategy uses the two-day price reversal principle and the multiple judgment of the stochastic indicator. If the previous closing price is higher but the current closing price reverses downward, and the fast stochastic is below the slow stochastic while the fast stochastic is above 50, a short signal is generated. If the previous closing price is lower but the current closing price reverses upward, and the fast stochastic is above the slow stochastic while the fast stochastic is below 50, a long signal is generated.
The improved price volume trend strategy is based on the joint research of price and trading volume. The calculation formula is: PxVFactor = PriceFactor + Scale * CumPVT, where PriceFactor is the price factor, and CumPVT is the accumulated power indicator. Then calculate the Length-day simple moving average of PxVFactor and compare it with the current PxVFactor value to determine the market trend and momentum.
The combo strategy comprehensively considers the signals of the two sub-strategies. When the double factors reversal and the improved price volume trend are bullish or bearish, corresponding long and short signals are generated.
Advantage Analysis
- The double factors reversal strategy combines price reversal and stochastic indicator judgment, which can effectively identify short-term extremums and capture reversal opportunities.
- The improved price volume trend strategy incorporates the trading volume factor to judge the momentum and consolidation of the market.
- The two strategies verify each other to improve stability and avoid wrong signals.
- Using medium-term parameters of 9 or 14 days is suitable for intraday and short-term operations.
Risk and Optimization
- Reversal strategies carry the risk of being trapped, requiring stop loss to control risk.
- Volume price strategies may increase drawdowns if the market direction is incorrectly judged.
- It can be tested whether the weights of the PriceFactor and CumPVT factors are optimal for further optimization.
- Parameters of different days can be tested for the best return to drawdown ratio.
Conclusion
In conclusion, the combo strategy of double factors reversal and improved price volume trend combines the judgments of reversal and trend in two dimensions. The two can verify signals from each other to improve stability. Adding a trend indicator as an auxiliary judgment is necessary in reversal strategies where it's easy to be trapped. And incorporating trading volume factors is also essential to determine market reversals and momentum. This strategy uses medium-term parameters suitable for intraday and short-term operations, with certain practical value.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | ---- 123 Reversal ---- |
| v_input_2 | 14 | Length |
| v_input_3 | true | KSmoothing |
| v_input_4 | 3 | DLength |
| v_input_5 | 50 | Level |
| v_input_6 | true | ---- Price-Volume Trend ---- |
| v_input_7 | true | LevelPVT |
| v_input_8 | true | Scale |
| v_input_9 | 23 | LengthPVT |
| v_input_10 | false | Trade reverse |
Source Pine Script
/*backtest
start: 2024-01-17 00:00:00
end: 2024-01-24 00:00:00
period: 15m
basePeriod: 5m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
////////////////////////////////////////////////////////////
//  Copyright by HPotter v1.0 23/02/2021
// This is combo strategies for get a cumulative signal.
//
// First strategy
// This System was created from the Book "How I Tripled My Money In The
// Futures Market" by Ulf Jensen, Page 183. This is reverse type of strategies.
// The strategy buys at market, if close price is higher than the previous close
// during 2 days and the meaning of 9-days Stochastic Slow Oscillator is lower than 50.
// The strategy sells at market, if close price is lower than the previous close price
// during 2 days and the meaning of 9-days Stochastic Fast Oscillator is higher than 50.
//
// Second strategy
//  The related article is copyrighted material from
//  Stocks & Commodities.
//
// WARNING:
// - For purpose educate only
// - This script to change bars colors.
////////////////////////////////////////////////////////////
Reversal123(Length, KSmoothing, DLength, Level) =>
    vFast = sma(stoch(close, high, low, Length), KSmoothing)
    vSlow = sma(vFast, DLength)
    pos = 0.0
    pos := iff(close[2] < close[1] and close > close[1] and vFast < vSlow and vFast > Level, 1,
	         iff(close[2] > close[1] and close < close[1] and vFast > vSlow and vFast < Level, -1, nz(pos[1], 0)))
	pos


MPVT(Level,Scale,Length) =>
    pos = 0.0
    xCumPVT = 0.0
    xOHLC4 = ohlc4
    xV = volume
    rV = xV / 50000
    xCumPVT := nz(xCumPVT[1]) + (rV * (xOHLC4 - xOHLC4[1]) / xOHLC4[1])
    nRes = Level + Scale * xCumPVT
    xMARes = sma(nRes, Length)
    pos:= iff(nRes > xMARes, 1,
           iff(nRes < xMARes, -1, nz(pos[1], 0)))
    pos

strategy(title="Combo Backtest 123 Reversal & Modified Price-Volume Trend", shorttitle="Combo", overlay = true)
line1 = input(true, "---- 123 Reversal ----")
Length = input(14, minval=1)
KSmoothing = input(1, minval=1)
DLength = input(3, minval=1)
Level = input(50, minval=1)
//-------------------------
line2 = input(true, "---- Price-Volume Trend ----")
LevelPVT = input(1)
Scale = input(1)
LengthPVT = input(23)
reverse = input(false, title="Trade reverse")
posReversal123 = Reversal123(Length, KSmoothing, DLength, Level)
posMPVT = MPVT(LevelPVT,Scale,LengthPVT)
pos = iff(posReversal123 == 1 and posMPVT == 1 , 1,
	   iff(posReversal123 == -1 and posMPVT == -1, -1, 0))
possig = iff(reverse and pos == 1, -1,
          iff(reverse and pos == -1 , 1, pos))
if (possig == 1 )
    strategy.entry("Long", strategy.long)
if (possig == -1 )
    strategy.entry("Short", strategy.short)
if (possig == 0)
    strategy.close_all()
barcolor(possig == -1 ? #b50404: possig == 1 ? #079605 : #0536b3 )Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-25. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Combo-Strategy-of-Double-Factors-Reversal-and-Improved-Price-Volume-Trend.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive Trading Strategy Combining Dynamic Trend Reversal and Stochastic IndicatorPine Script · Mean reversion · 1d
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- Bollinger Bands Stochastic RSI Extreme Strategy BBSR Extreme StrategyPine Script · Mean reversion · 1h
- BuySell Strategy depends on AOStochRSIATRPine Script · Mean reversion · 30m
- Byron Serpent Cloud Quant StrategyPine Script · Mean reversion · 1h
- Dual Momentum Trend Reversal Strategy Based on RSI and Stochastic RSIPine Script · Mean reversion · 1h