Consecutive Up Down Strategy with Reverse and SL TP Extension
This strategy is an extension of the built-in consecutive up/down bars strategy on TradingView. It has flexible direction settings that allow reverse trading. Also, integrated with various stop loss methods like…
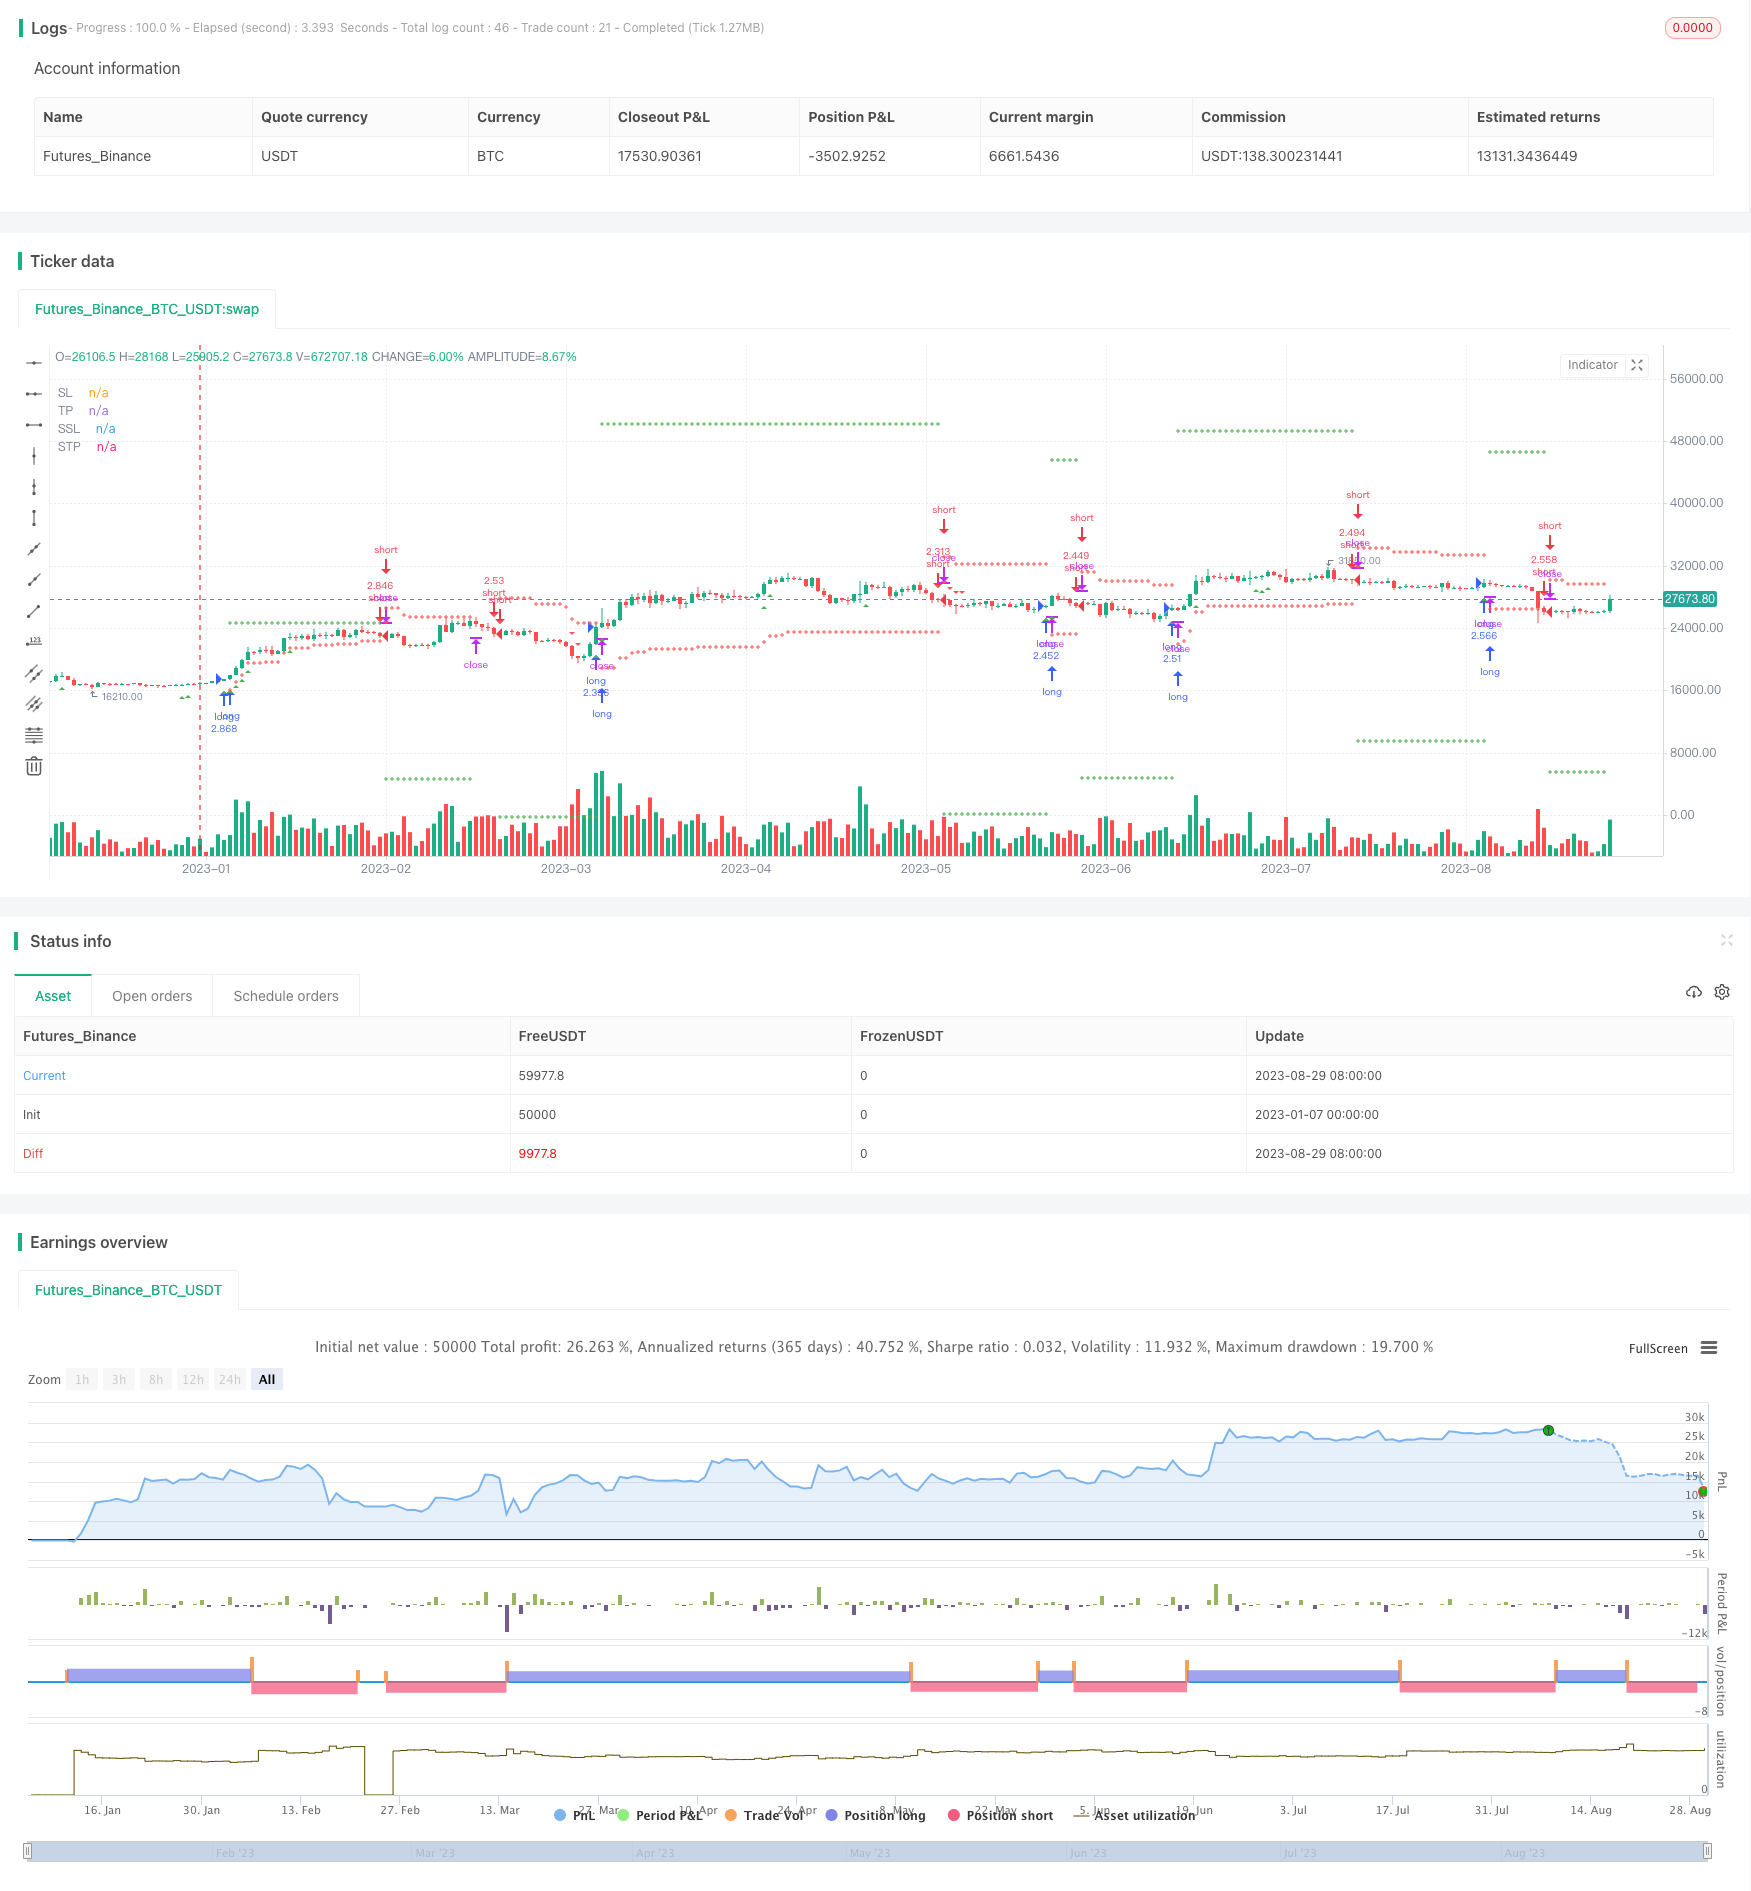
Overview
This strategy is an extension of the built-in consecutive up/down bars strategy on TradingView. It has flexible direction settings that allow reverse trading. Also, integrated with various stop loss methods like swing points/low, ATR stop, and strategy stop, as well as take profit settings accordingly. This makes the strategy better at risk management while keeping the original trading signals.
Strategy Logic
The strategy mainly uses the consecutive up or down bars to generate buy and sell signals. Users can configure the needed consecutive up bars for buy signals, and consecutive down bars for sell signals.
Also, the reverse trade option is added. By enabling it, the original buy signals become sell signals, and vice versa, thus completing the trade reversal.
For entries and exits, direct position reverse is supported to reduce the time with no position.
For stop loss and take profit, swing points/low, ATR stop and strategy stop are provided for choice. The stop loss method will combine with position direction to pick swing low or high as aggressive stop, or use ATR to dynamically define stop price. Take profit sets a fixed distance based on entry price.
If trailing stop enabled, the strategy can loosen stop distance when losing, and tighten when profiting. This achieves automatic trailing effect.
Advantage Analysis
The biggest advantage of this strategy is flexibility to adapt to different market conditions:
- Buy/sell filter parameters can be set for both trending and ranging markets
- Reverse trade allows direction choice when needed
- Direct reverse position reduces time with no position
- Multiple stop loss methods, select as needed
- Trailing stop available for automatic effect
Risk Analysis
The main risks are too many consecutive bars leading to missing trades, and aggressive stop loss causing extended losses. Suggestions are:
- Adjust up/down bars quantity moderately, not too aggressive
- Test different stop loss methods, find the best fit one
- Use trailing stop cautiously, avoid too big losses
Optimization Directions
There is room for further optimization:
- Dynamically adjust up/down bars based on ATR or volatility
- Test stop loss/profit ratio under different holding periods
- Add open price filter to avoid false breakout
- Integrate other indicators for better signal quality
Conclusion
This strategy makes beneficial extensions to the base strategy for better risk control and more flexible trading. It is an effective momentum strategy that is easy to optimize and trade live.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | false | Strategy Direction |
| v_input_2 | true | -----------------Strategy Inputs------------------- |
| v_input_3 | 3 | consecutiveBarsUp |
| v_input_4 | 4 | consecutiveBarsDown |
| v_input_5 | true | -----------------General Inputs------------------- |
| v_input_6 | true | Use Stop Loss and Take Profit |
| v_input_7 | 0 | Type Of Stop: ATR Stop | Swing Lo/Hi | Strategy Stop |
| v_input_8 | 10 | Swing Point Lookback |
| v_input_9 | 2 | Swing Point SL Perc Increment |
| v_input_10 | 14 | ATR Length |
| v_input_11 | 5 | ATR Multiple |
| v_input_12 | 5 | Take Profit Risk Reward Ratio |
| v_input_13 | true | Trailing Stop |
| v_input_14 | true | Allow Direct Position Reverse |
| v_input_15 | false | Reverse Trades |
Source Pine Script
/*backtest
start: 2023-01-07 00:00:00
end: 2023-08-30 05:20:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// Extension of the built-in strategy by Tradingview. The strategy buys after an X amount of
// consecutive bullish bars and viceversa for selling. This logic can be reversed and a Stop Loss
// with Take Profit can be added. There's also an option to adapt the SL into a Trailing Stop.

//@version=4
strategy("Consecutive Up/Down Strategy with Reverse",
     overlay=true,
     default_qty_type=strategy.percent_of_equity,
     default_qty_value=100,
     initial_capital=10000,
     commission_value=0.04,
     calc_on_every_tick=false,
     slippage=0)

direction = input(0, title = "Strategy Direction", type=input.integer, minval=-1, maxval=1)
strategy.risk.allow_entry_in(direction == 0 ? strategy.direction.all : (direction < 0 ? strategy.direction.short : strategy.direction.long))

/////////////////////// STRATEGY INPUTS ////////////////////////////////////////
title1=input(true, "-----------------Strategy Inputs-------------------")

consecutiveBarsUp = input(3)
consecutiveBarsDown = input(4)

/////////////////////// BACKTESTER /////////////////////////////////////////////
title2=input(true, "-----------------General Inputs-------------------")

// Backtester General Inputs
i_SL=input(true, title="Use Stop Loss and Take Profit")
i_SLType=input(defval="ATR Stop", title="Type Of Stop", options=["Strategy Stop", "Swing Lo/Hi", "ATR Stop"])
i_SPL=input(defval=10, title="Swing Point Lookback")
i_PercIncrement=input(defval=2, step=.1, title="Swing Point SL Perc Increment")*0.01
i_ATR = input(14, title="ATR Length")
i_ATRMult = input(5, step=.1, title="ATR Multiple")
i_TPRRR = input(5, step=.1, title="Take Profit Risk Reward Ratio")
TS=input(true, title="Trailing Stop")

// Bought and Sold Boolean Signal
bought = strategy.position_size > strategy.position_size[1]
 or strategy.position_size < strategy.position_size[1]

// Price Action Stop and Take Profit
LL=(lowest(i_SPL))*(1-i_PercIncrement)
HH=(highest(i_SPL))*(1+i_PercIncrement)
LL_price = valuewhen(bought, LL, 0)
HH_price = valuewhen(bought, HH, 0)
entry_LL_price = strategy.position_size > 0 ? LL_price : na
entry_HH_price = strategy.position_size < 0 ? HH_price : na
tp=strategy.position_avg_price + (strategy.position_avg_price - entry_LL_price)*i_TPRRR
stp=strategy.position_avg_price - (entry_HH_price - strategy.position_avg_price)*i_TPRRR

// ATR Stop
ATR=atr(i_ATR)*i_ATRMult
ATRLong = ohlc4 - ATR
ATRShort = ohlc4 + ATR
ATRLongStop = valuewhen(bought, ATRLong, 0)
ATRShortStop = valuewhen(bought, ATRShort, 0)
LongSL_ATR_price = strategy.position_size > 0 ? ATRLongStop : na
ShortSL_ATR_price = strategy.position_size < 0 ? ATRShortStop : na
ATRtp=strategy.position_avg_price + (strategy.position_avg_price - LongSL_ATR_price)*i_TPRRR
ATRstp=strategy.position_avg_price - (ShortSL_ATR_price - strategy.position_avg_price)*i_TPRRR


// Strategy Stop
float LongStop = na
float ShortStop = na
float StratTP = na
float StratSTP = na

/////////////////////// STRATEGY LOGIC /////////////////////////////////////////

price = close
ups = 0.0
ups := price > price[1] ? nz(ups[1]) + 1 : 0
dns = 0.0
dns := price < price[1] ? nz(dns[1]) + 1 : 0

BUY=ups >= consecutiveBarsUp and bar_index > 40
SELL=dns >= consecutiveBarsDown and bar_index > 40

//Trading Inputs
DPR=input(true, "Allow Direct Position Reverse")
reverse=input(false, "Reverse Trades")

// Entries
if reverse
    if not DPR
        strategy.entry("long", strategy.long, when=SELL and strategy.position_size == 0)
        strategy.entry("short", strategy.short, when=BUY and strategy.position_size == 0)
    else
        strategy.entry("long", strategy.long, when=SELL)
        strategy.entry("short", strategy.short, when=BUY)
else
    if not DPR
        strategy.entry("long", strategy.long, when=BUY and strategy.position_size == 0)
        strategy.entry("short", strategy.short, when=SELL and strategy.position_size == 0)
    else
        strategy.entry("long", strategy.long, when=BUY)
        strategy.entry("short", strategy.short, when=SELL)


SL= i_SLType == "Swing Lo/Hi" ? entry_LL_price : i_SLType == "ATR Stop" ? LongSL_ATR_price : LongStop
SSL= i_SLType == "Swing Lo/Hi" ? entry_HH_price : i_SLType == "ATR Stop" ? ShortSL_ATR_price : ShortStop
TP= i_SLType == "Swing Lo/Hi" ? tp : i_SLType == "ATR Stop" ? ATRtp : StratTP
STP= i_SLType == "Swing Lo/Hi" ? stp : i_SLType == "ATR Stop" ? ATRstp : StratSTP

//TrailingStop
dif=(valuewhen(strategy.position_size>0 and strategy.position_size[1]<=0, high,0))
 -strategy.position_avg_price
trailOffset     = strategy.position_avg_price - SL
var tstop = float(na)
if strategy.position_size > 0
    tstop := high- trailOffset - dif
    if tstop<tstop[1]
        tstop:=tstop[1]
else
    tstop := na
StrailOffset     = SSL - strategy.position_avg_price
var Ststop = float(na)
Sdif=strategy.position_avg_price-(valuewhen(strategy.position_size<0
 and strategy.position_size[1]>=0, low,0))
if strategy.position_size < 0
    Ststop := low+ StrailOffset + Sdif
    if Ststop>Ststop[1]
        Ststop:=Ststop[1]
else
    Ststop := na

strategy.exit("TP & SL", "long", limit=TP, stop=TS? tstop : SL, when=i_SL)
strategy.exit("TP & SL", "short", limit=STP, stop=TS? Ststop : SSL, when=i_SL)

/////////////////////// PLOTS //////////////////////////////////////////////////


plot(i_SL and strategy.position_size > 0 and not TS ? SL : i_SL and strategy.position_size > 0 and TS ? tstop : na , title='SL', style=plot.style_cross, color=color.red)
plot(i_SL and strategy.position_size < 0 and not TS ? SSL : i_SL and strategy.position_size < 0 and TS ? Ststop : na , title='SSL', style=plot.style_cross, color=color.red)
plot(i_SL and strategy.position_size > 0 ? TP : na, title='TP', style=plot.style_cross, color=color.green)
plot(i_SL and strategy.position_size < 0 ? STP : na, title='STP', style=plot.style_cross, color=color.green)
// Draw price action setup arrows
plotshape(BUY ? 1 : na, style=shape.triangleup, location=location.belowbar,
 color=color.green, title="Bullish Setup", size=size.auto)
plotshape(SELL ? 1 : na, style=shape.triangledown, location=location.abovebar,
color=color.red, title="Bearish Setup", size=size.auto)Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-08. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Consecutive-Up-Down-Strategy-with-Reverse-and-SL-TP-Extension.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ATR Trailing Stops StrategyPine Script · Breakout · 1h
- ATR Trend Breakout StrategyPine Script · Breakout · 1d
- Advanced Multi Pattern Breakout Trading StrategyPine Script · Breakout · 1d
- BB Breakout StrategyPine Script · Breakout · 1d
- Bollinger Band Breakout Trend Following StrategyPine Script · Breakout · 1d
- Breakout Strategy Based on Turtle TradingPine Script · Breakout · 1d