Strategy vault / Machine learning
Cross Timeframe Hull Moving Average Buy Sell Strategy
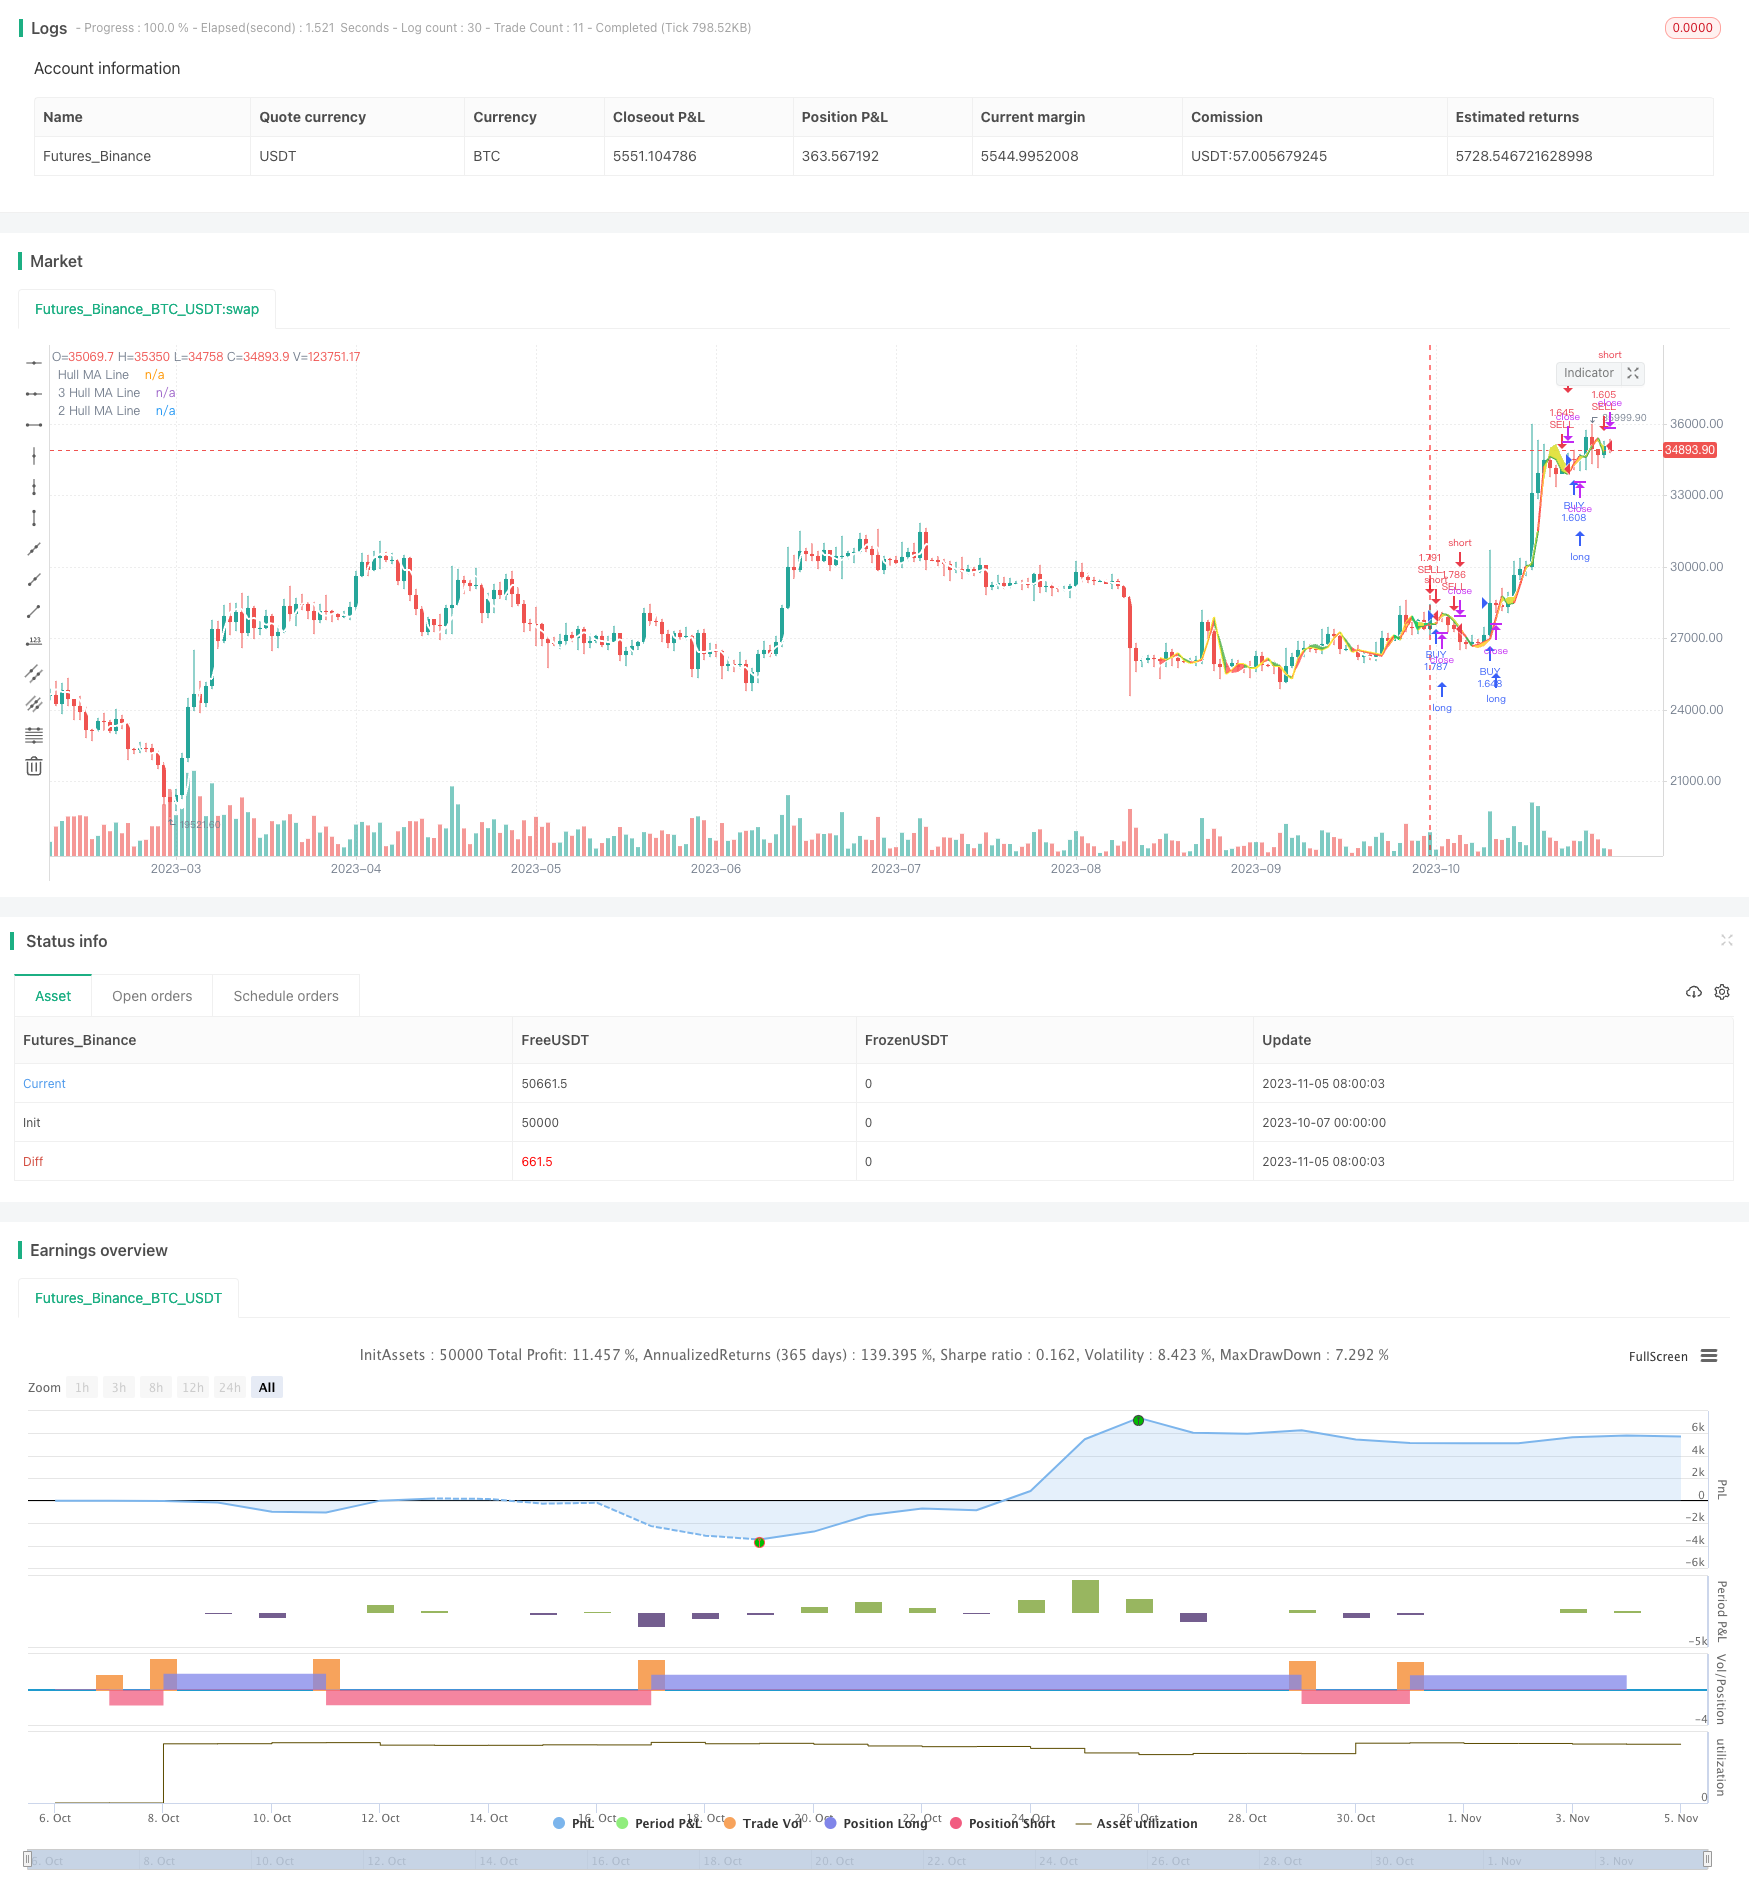
This strategy is based on the Hull Moving Average indicator, calculating Hull MA on different timeframes and comparing the Hull MA trends across timeframes to identify trend changes. It generates buy signals when the…
Overview
This strategy is based on the Hull Moving Average indicator, calculating Hull MA on different timeframes and comparing the Hull MA trends across timeframes to identify trend changes. It generates buy signals when the shorter period Hull MA crosses above the longer period Hull MA, and sell signals when the shorter Hull MA crosses below the longer one.
Strategy Logic
Input parameters: Hull MA period Period, HMA2 timeframe Resolution2, HMA3 timeframe Resolution3
Calculate current bar's Hull MA value HMA
Calculate Hull MA value HMA2 on Resolution2 timeframe
Calculate Hull MA value HMA3 on Resolution3 timeframe
Compare the magnitude relationship between HMA, HMA2, HMA3
Generate buy signal when HMA>HMA2>HMA3
Generate sell signal when HMA<HMA2<HMA3
Display Hull MA values and signals on different timeframes on top left of chart
Use colors to distinguish uptrend and downtrend
Advantage Analysis
Using multiple timeframes can filter false breakouts and avoid traps.
Customizable timeframe parameters, adaptable to different periods and volatility.
Real-time signal display, intuitive operation.
Visualized Hull MA trends help determine current trend.
Risk Analysis
Improper parameter settings may cause over-trading.
Larger timeframe Hull MA has lagging effect, may miss trend turning points.
May generate false signals around bull-bear transition.
Breakout strategies are prone to getting trapped by false breakouts.
Trading commissions are not considered which impacts actual profit.
Risks can be reduced by optimizing parameters, combining other indicators for filtration, and allowing wider stop loss.
Optimization Directions
Optimize Hull MA period adaptable to different periods and volatility.
Add volume indicator to avoid false breakouts.
Add oscillators to determine trend strength.
Incorporate machine learning models for buy/sell timing.
Combine sentiment indicators to detect market hype.
Adjust stop loss strategy for better risk management.
Customize buy/sell conditions with other indicator signals.
Add price channel or wave based trading strategies.
Conclusion
This strategy uses multi-timeframe Hull MA to determine trend direction by comparing moving average slopes across timeframes and generates signals at trend reversals. Multi-timeframe Hull MA is more effective in filtering false breakouts than single MA. But this strategy also has limitations in parameter tuning, trend determination etc. Integrating more indicators, optimizing parameters, improving stop loss can enhance profitability and control risk.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 6 | Hull MA Period |
| v_input_2 | 60 | HMA2 Resolution |
| v_input_3 | 240 | HMA3 Resolution |
| v_input_4_open | 0 | Source of Price: open | high | low | close | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_5 | 40 | Panel offset (X-Axis) |
| v_input_6 | false | Panel offset (y-Axis) |
Source Pine Script
/*backtest
start: 2023-10-07 00:00:00
end: 2023-11-06 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
//
strategy("wtfBUYorSELLffs",overlay=true,currency="USD",initial_capital=100000,default_qty_type=strategy.percent_of_equity,default_qty_value=100,commission_type=strategy.commission.percent,commission_value=0.1)
Period=input(title="Hull MA Period",type=input.integer,defval=6,minval=1)
Resolution2=input(title="HMA2 Resolution", type=input.resolution,defval="60")
Resolution3=input(title="HMA3 Resolution", type=input.resolution,defval="240")
Price=input(title="Source of Price",type=input.source,defval=open)
xOffset       = input(40, title="Panel offset (X-Axis)")
yOffset       = input(0, title="Panel offset (y-Axis)")
lightgray = #D3D3D3FF
pnlTextColor = color.silver
pnlColor = color.black
HMA = hma(Price,Period)
HMA2 = security(syminfo.tickerid, Resolution2, HMA,barmerge.gaps_off,barmerge.lookahead_off)
HMA3 = security(syminfo.tickerid, Resolution3, HMA,barmerge.gaps_off,barmerge.lookahead_off)
HUP = HMA > HMA[1]
H1UP = security(syminfo.tickerid, Resolution2, HUP,barmerge.gaps_off,barmerge.lookahead_off)
H2UP = security(syminfo.tickerid, Resolution3, HUP,barmerge.gaps_off,barmerge.lookahead_off)

int barSize = timeframe.isdaily ? timeframe.multiplier*86400000 :
           timeframe.isseconds? timeframe.multiplier*1000 :
           timeframe.isminutes? timeframe.multiplier*60000 : (time[0]-time[1])
int   lapos_x = timenow + barSize*xOffset
float lapos_y = highest(20) + yOffset*syminfo.mintick * syminfo.pointvalue
f_draw_infopanel(_x, _y, _line, _text)=>
    _rep_text = ""
    for _l = 0 to _line
        _rep_text := _rep_text + "\n"
    _rep_text := _rep_text + _text
    // var label _la = na
    // label.delete(_la)
//     _la := label.new(
//          x=_x, y=_y,
//          text=_rep_text, xloc=xloc.bar_time, yloc=yloc.price,
//          color=pnlColor, style=label.style_labelup, textcolor=pnlTextColor, size=size.normal)
// f_draw_infopanel(lapos_x, lapos_y, 8, "╚═══════════════════════╝")
f_draw_infopanel(lapos_x, lapos_y, 6,  "HMA3 on TF " + Resolution3 + "  = " + tostring(HMA3,"#.####") + (H2UP ? " BUY" : " SELL"))
f_draw_infopanel(lapos_x, lapos_y, 4,  "HMA2 on TF " + Resolution2 + "  = " +  tostring(HMA2,"#.####") + (H1UP ? " BUY" : " SELL"))
f_draw_infopanel(lapos_x, lapos_y, 2,  "HMA1 on TF " + timeframe.period + "  = " + tostring(HMA,"#.####") + (HUP ? " BUY" : " SELL"))
f_draw_infopanel(lapos_x, lapos_y, 0,  "╔═════════ HMA(" + tostring(Period,"#") +") ════════╗")
change_color=HMA>HMA3?color.green:color.red
change_color2=HMA2>HMA3?color.lime:color.yellow
plot1=plot(HMA3,color=change_color2,title="3 Hull MA Line",linewidth=2,transp=75)
plot2=plot(HMA2,color=change_color,title="2 Hull MA Line",linewidth=2,transp=75)
plot3=plot(HMA,color=color.white,title="Hull MA Line",linewidth=2,transp=75)
fill(plot1,plot3,color=change_color,transp=90)
fill(plot2,plot3,color=change_color2,transp=75)
if (H2UP and H1UP and HUP)
    strategy.entry("BUY",strategy.long)
if (not H2UP and not H1UP and not HUP)
    strategy.entry("SELL",strategy.short)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-07. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Cross-Timeframe-Hull-Moving-Average-Buy-Sell-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- AI Driven Dynamic Volatility Adaptive Trend Breakout Trading StrategyPine Script · Machine learning · 2d
- AI Powered Volatility Price System Divergence Trading StrategyPine Script · Machine learning · 1h
- Configurable BBRSIAroon Strategy BacktestPine Script · Machine learning · 5m
- Double Decker RSI Trading StrategyPine Script · Machine learning · 1h
- Dual Moving Average Matching Strategy Based on Bollinger BandsPine Script · Machine learning · 1h
- Dynamic Weighted Moving Average Trading StrategyPine Script · Machine learning · 1d