Crossing Strategy Between Bollinger Bands and Hull Indicator
This strategy generates trading signals based on the crossover between Bollinger Bands and the Hull indicator. It goes long when the Hull indicator crosses above the lower band of Bollinger Bands, and goes short when…
Summary
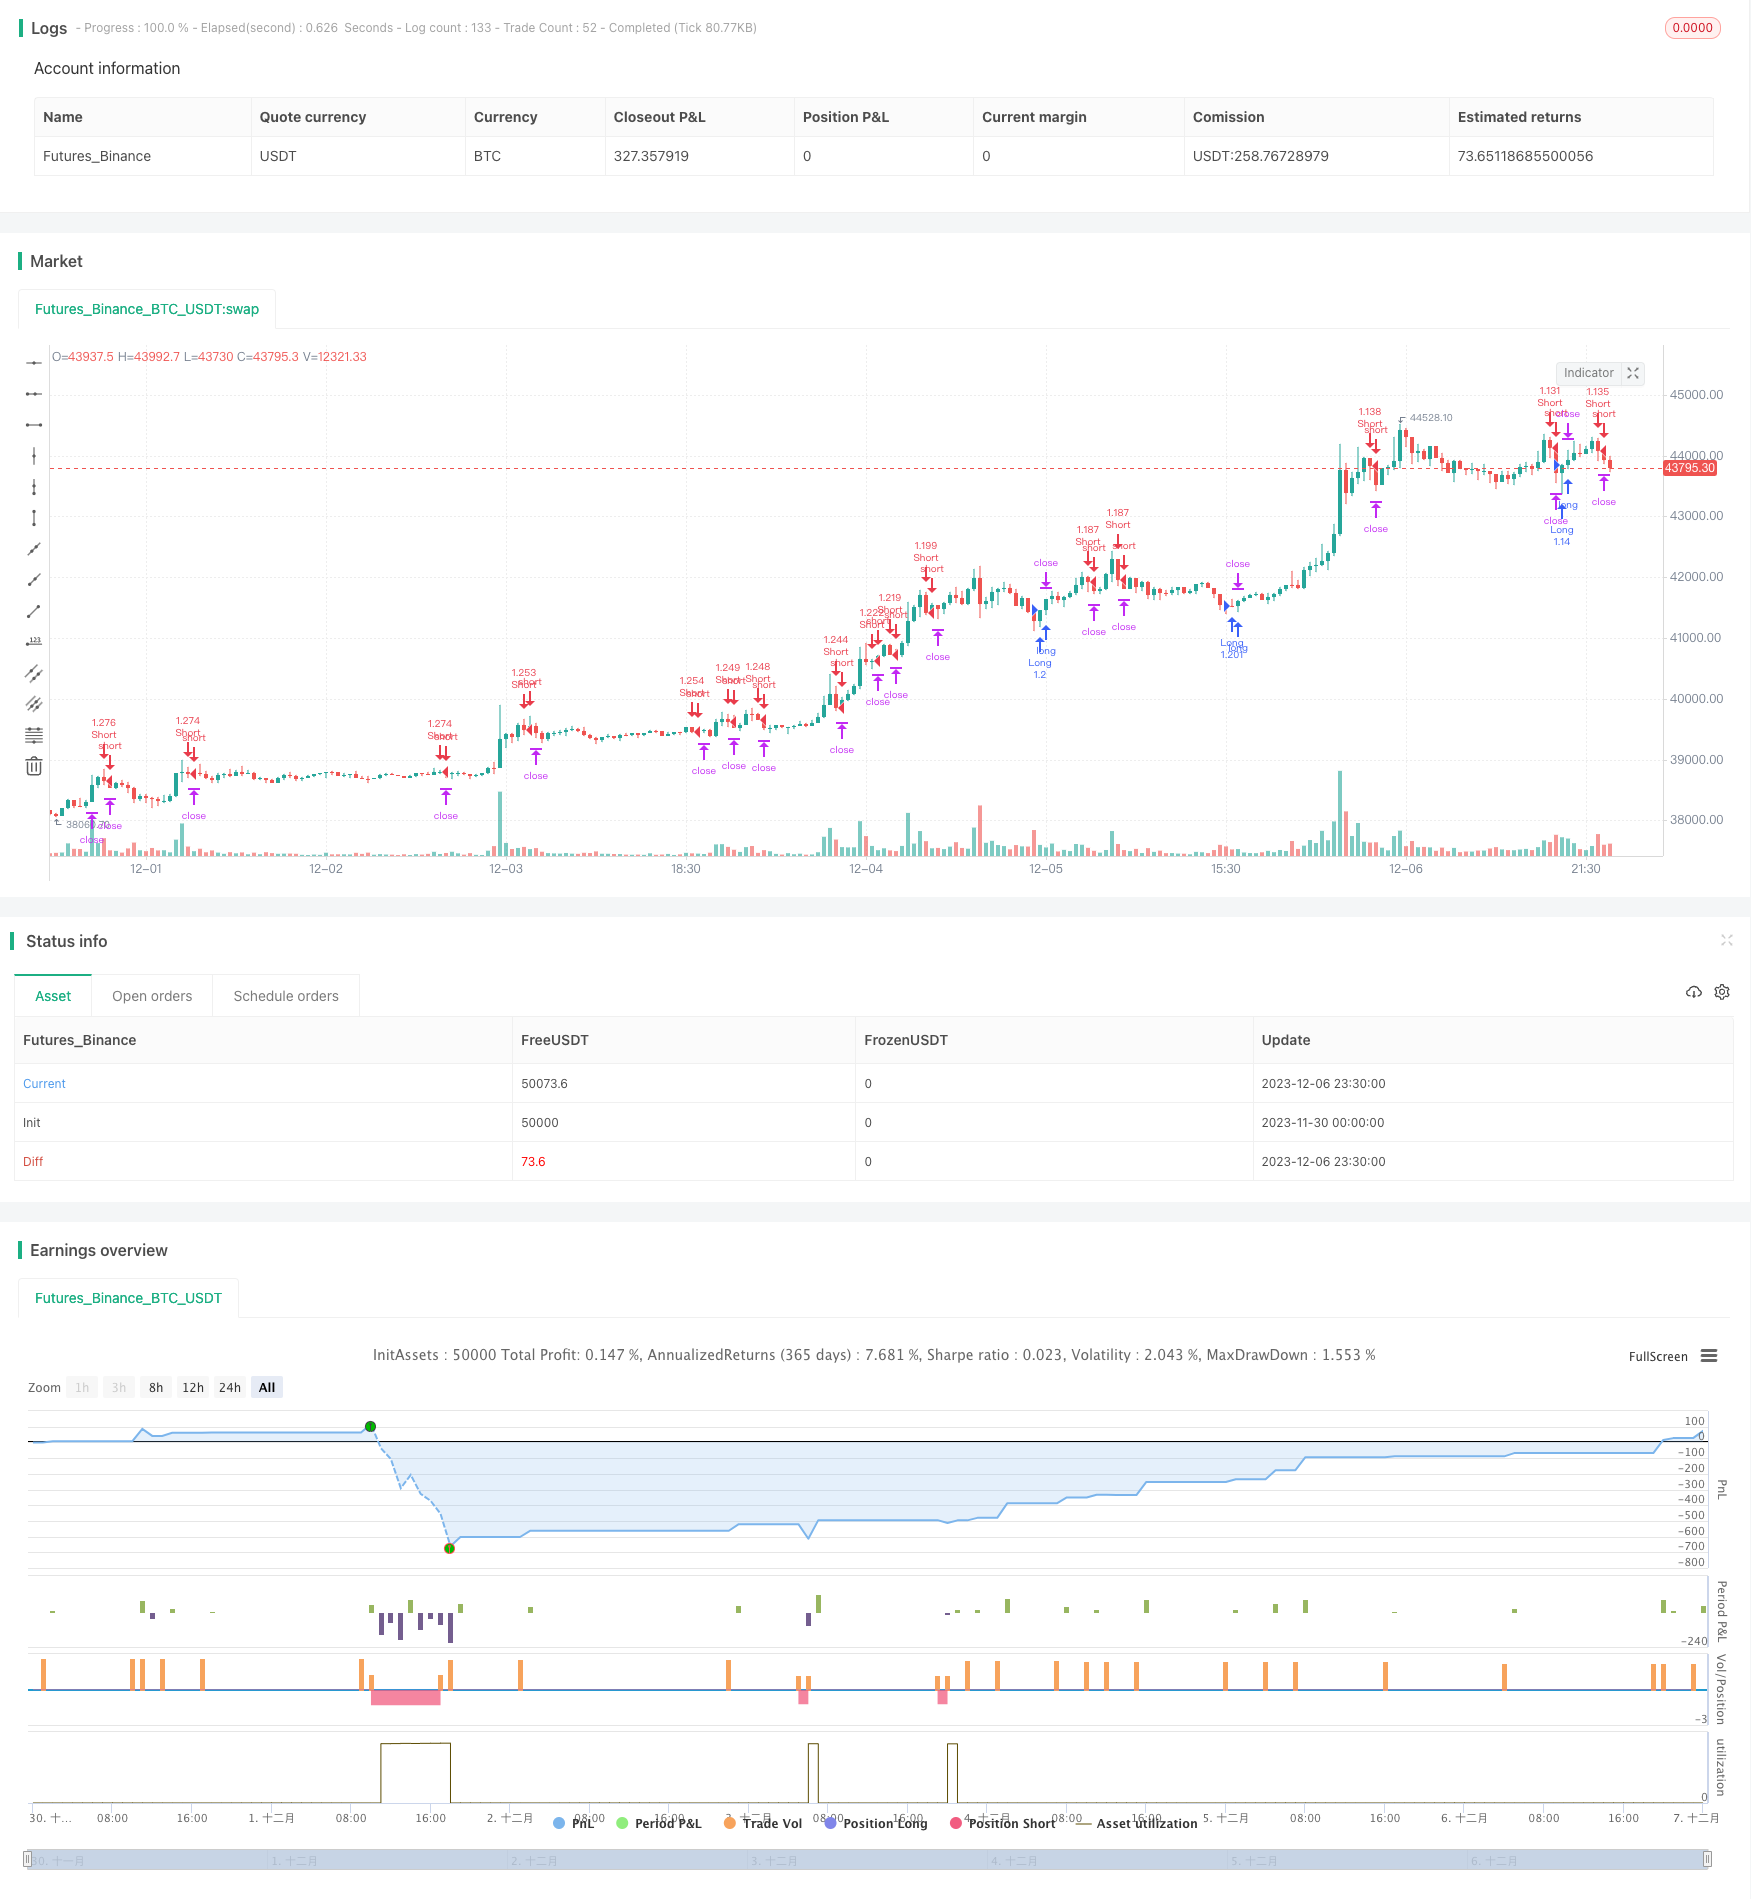
This strategy generates trading signals based on the crossover between Bollinger Bands and the Hull indicator. It goes long when the Hull indicator crosses above the lower band of Bollinger Bands, and goes short when the Hull indicator crosses below the upper band of Bollinger Bands. The strategy combines the breakout strategy of Bollinger Bands and the trend-following strategy of the Hull indicator to utilize the advantages of both.
Principles
The strategy mainly uses the crossover between Bollinger Bands and the Hull indicator to generate trading signals.
Bollinger Bands contain three lines: middle line, upper line and lower line. The middle line is the N-day moving average, while the upper and lower lines are middle line ± standard deviation. If price breaks through the upper line, it indicates a breakthrough opportunity; if price breaks through the lower line, it indicates a callback opportunity.
The Hull indicator is a trend-following indicator. It uses the difference between two weighted moving averages of different periods to determine the current trend. If the short period moving average is above the long period one, it indicates an uptrend, and vice versa.
The strategy combines the strengths of both indicators. When the Hull indicator crosses above the lower band of Bollinger Bands, it is considered that stock price may enter an uptrend, so go long. When the Hull indicator crosses below the upper band, it is considered that stock price may enter a downward callback, so go short.
Advantages
Combines the strengths of Bollinger Bands and Hull indicator to make trading signals more reliable.
Uses Hull indicator to determine trend direction and Bollinger Bands to determine support/resistance levels, generating crossover signals to improve profitability.
Parameters of both indicators can be optimized for stocks of different cycles to expand applicability.
Risks and Solutions
The strategy may generate more false signals during range-bound movements, causing losses. Parameters can be optimized or filters can be added to reduce false signals.
Prices may fluctuate violently, causing both indicators to issue signals simultaneously. Ensure signal sequencing to avoid erroneous crossover signal judgment. Consider adding stop loss to control losses.
Strategy sets position size to 100% directly. In actual deployment, position sizing needs to be adjusted to avoid magnified losses due to full position opening.
Optimization Directions
Test and optimize parameters of both indicators to adapt to more stock cycles.
Add filters like trading volume or volatility to avoid wrong signals during consolidation.
Optimize stop loss strategies by setting trailing stop loss or stop limit orders.
Adjust position sizing rules by adding re-entry conditions to avoid loss magnification.
Conclusion
This strategy combines the breakout strategy of Bollinger Bands and trend-following strategy of the Hull indicator by using crossover signals between them to achieve both trend-following and breakout effects. The strategy has strong adaptability to medium- and short-term stocks given no major fundamental changes. But parameters, position sizing, stop loss strategies still need optimization during actual deployment to make the strategy more robust.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 3 | period |
| v_input_2 | true | i |
| v_input_3 | 20 | length1 |
| v_input_4_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_5 | 2 | mult |
| v_input_6 | 500 | TP |
| v_input_7 | 500 | SL |
| v_input_8 | 20 | TS |
| v_input_9 | 10 | TO |
Source Pine Script
/*backtest
start: 2023-11-30 00:00:00
end: 2023-12-07 00:00:00
period: 30m
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/


//@version=3
strategy(title="Strategy Hull Bollinger", shorttitle="Hull bollinger",overlay=true, calc_on_order_fills=true, default_qty_type=strategy.percent_of_equity, default_qty_value=100, overlay=false)

n=input(title="period",defval=3)


n2ma=2*wma(close,round(n/2))
nma=wma(close,n)
diff=n2ma-nma
sqn=round(sqrt(n))


n2ma1=2*wma(close[1],round(n/2))
nma1=wma(close[1],n)
diff1=n2ma1-nma1
sqn1=round(sqrt(n))


n1=wma(diff,sqn)
n2=wma(diff1,sqn)
c=n1>n2?green:red

i = input(1)
PP = close[i]

length1 = input(20, minval=1)
src = input(close, title="Source")
mult = input(2.0, minval=0.001, maxval=10, step=0.2)
basis = sma(src, length1)
dev = mult * stdev(src, length1)
upper = basis + dev
lower = basis - dev


TP = input(500) * 10
SL = input(500) * 10
TS = input(20) * 10
TO = input(10) * 10
CQ = 100

TPP = (TP > 0) ? TP : na
SLP = (SL > 0) ? SL : na
TSP = (TS > 0) ? TS : na
TOP = (TO > 0) ? TO : na

longCondition = crossover(n1,lower)
if (longCondition)
    strategy.entry("Long", strategy.long)


shortCondition = crossunder(n1,upper)
if (shortCondition)
    strategy.entry("Short", strategy.short)

strategy.exit("Close Short", "Short", qty_percent=CQ, profit=TPP, loss=SLP, trail_points=TSP, trail_offset=TOP)
strategy.exit("Close Long", "Long", qty_percent=CQ, profit=TPP, loss=SLP, trail_points=TSP, trail_offset=TOP)Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-08. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Crossing-Strategy-Between-Bollinger-Bands-and-Hull-Indicator.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bollinger Bands Breakout Trading StrategyPine Script · Breakout · 1h
- Bollinger Bands Dynamic Breakout StrategyPine Script · Breakout · 1h
- Momentum Breakout Moving Average StrategyPine Script · Breakout · 1d
- Moving Average Crossover and Upper Rail Breakthrough Impulse StrategyPine Script · Breakout · 1m
- Moving Average Support and Resistance Breakout StrategyPine Script · Breakout · 1d
- Multi factor Intelligent Trading StrategyPine Script · Breakout · 1d