DCCI Breakout Strategy
The DCCI Breakout Strategy is a short-term trading strategy that identifies oversold and overbought situations using the CCI indicator. It combines the CCI indicator and WMA moving average line. It goes long when the…
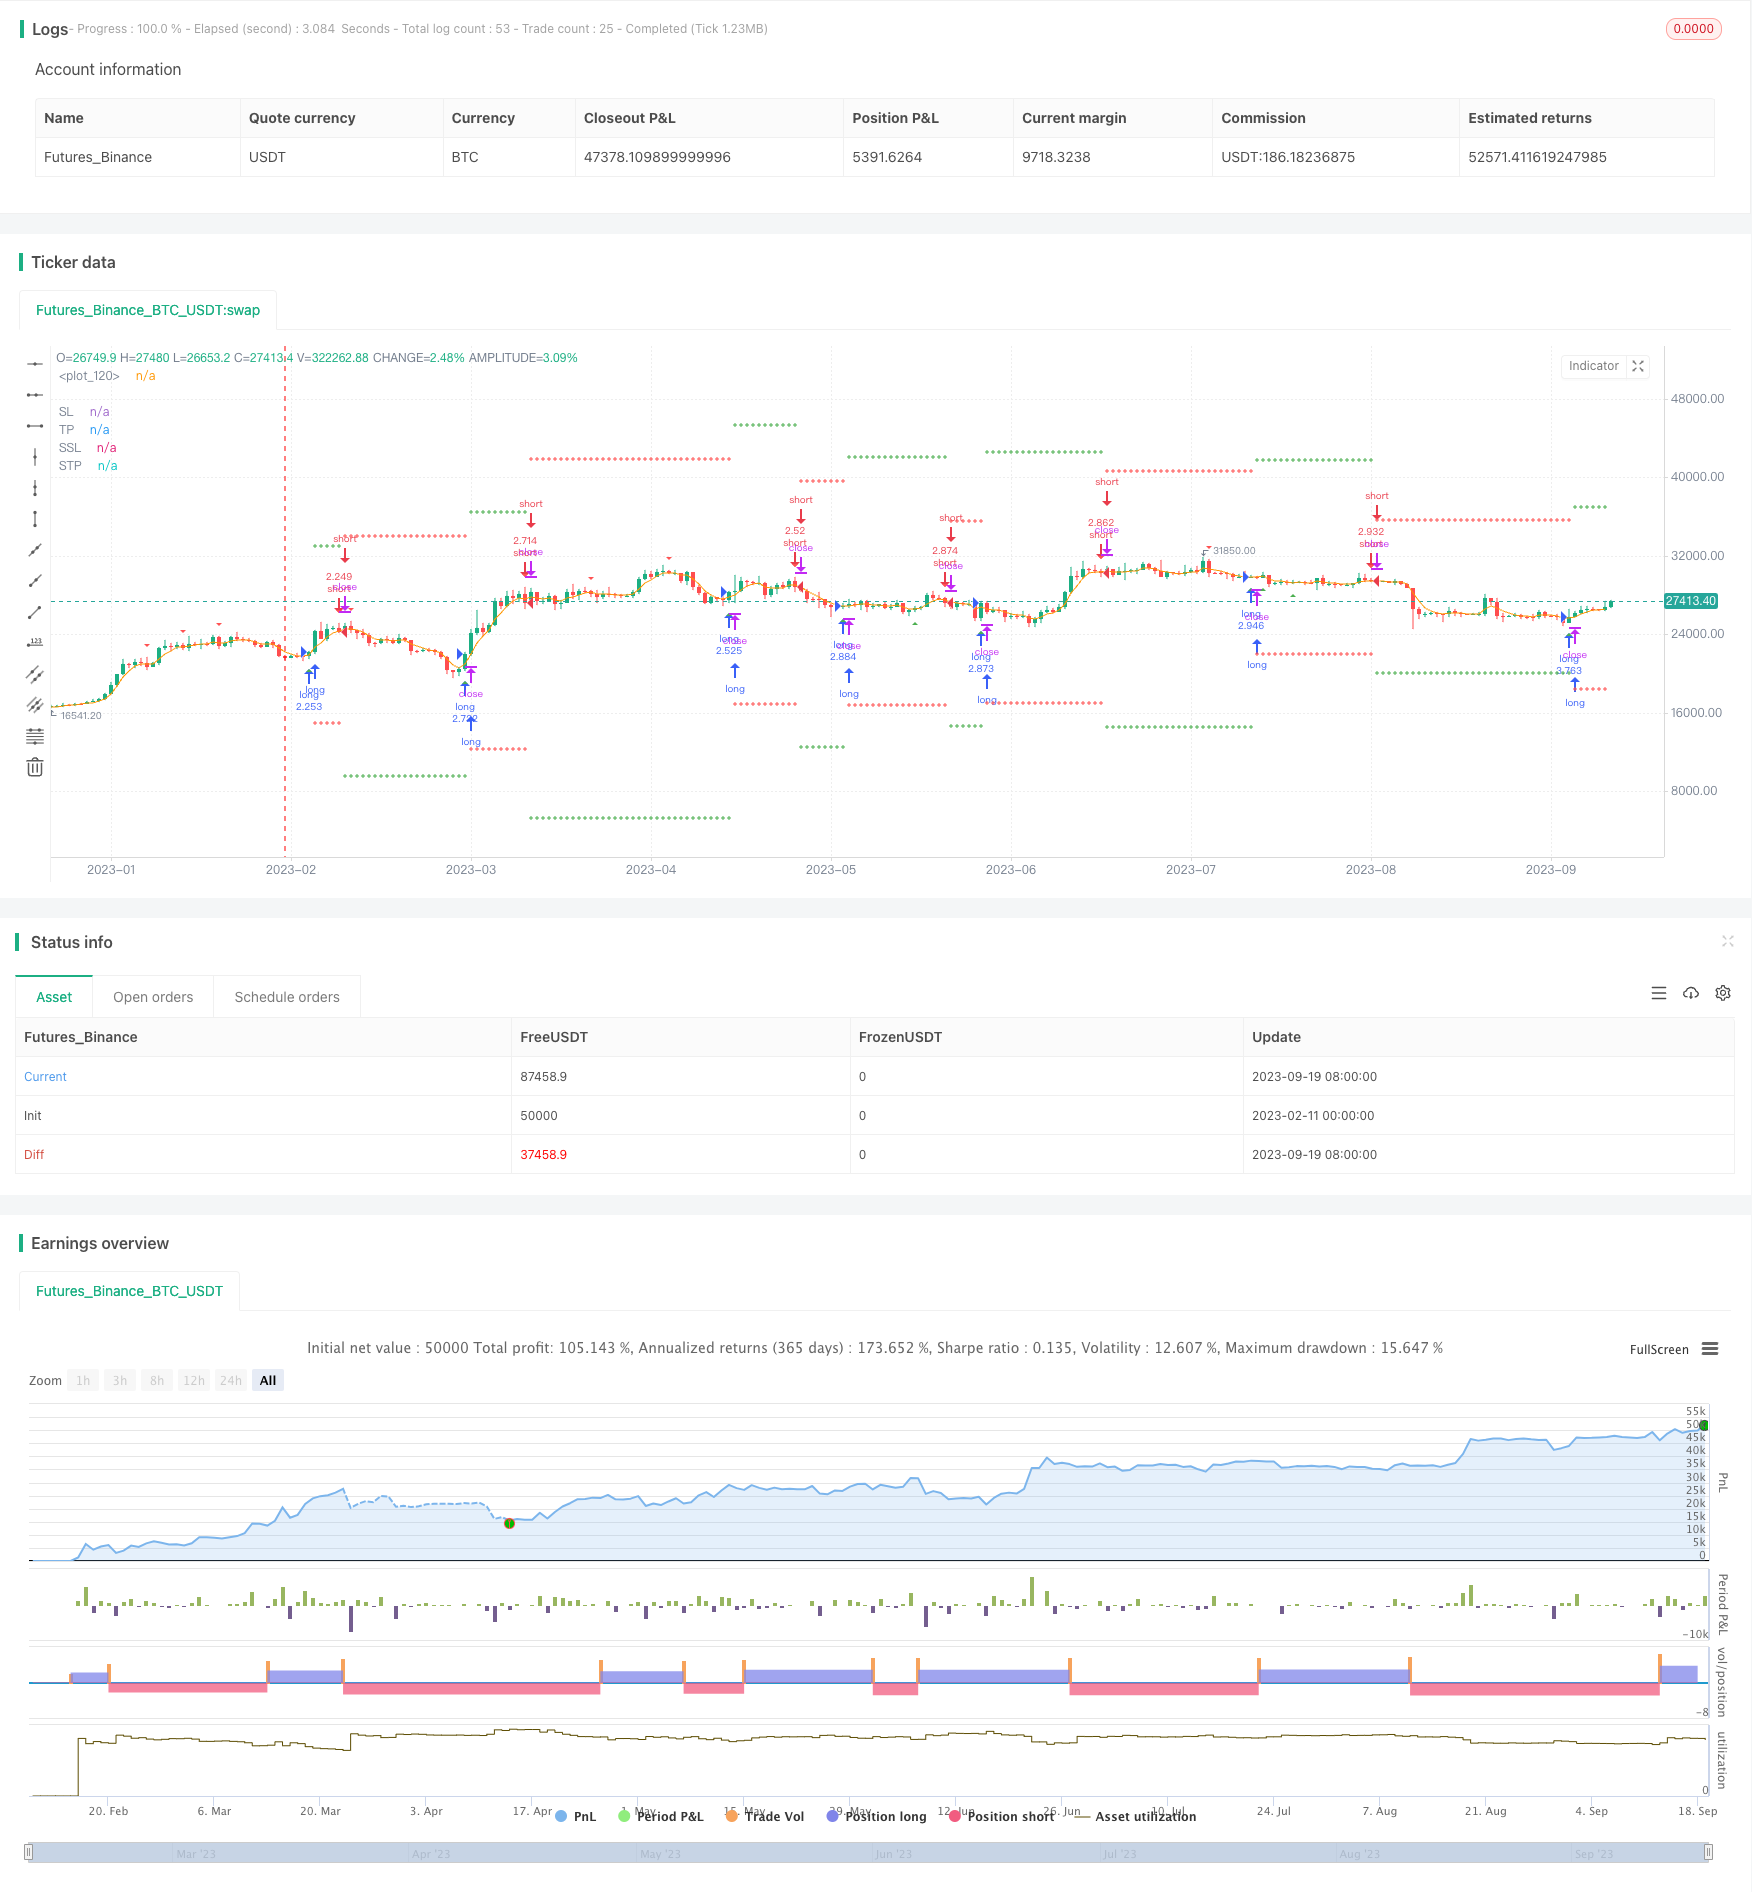
Overview
The DCCI Breakout Strategy is a short-term trading strategy that identifies oversold and overbought situations using the CCI indicator. It combines the CCI indicator and WMA moving average line. It goes long when the CCI indicator bounces back from the oversold zone and goes short when the CCI indicator falls back from the overbought zone, exiting after making a profit.
Strategy Logic
The strategy uses the CCI indicator to judge the overbought/oversold conditions of the market. The CCI indicator can effectively identify abnormal price situations. Values below -100 indicate the market is oversold while values above 100 indicate the market is overbought. The strategy will go long when the CCI indicator crosses above -100 coming from below; and will go short when the CCI indicator crosses below 100 coming from above.
At the same time, the strategy also incorporates the WMA moving average line to determine trend direction. Only when the closing price is above the WMA line will long signals be valid; only when the closing price is below the WMA line will short signals be valid. This helps filter out some ambiguous trade signals.
After entering a position, the strategy uses stop loss to control risks. There are three optional stop loss methods: fixed strategy stop, swing high/low stop, ATR stop. When long, the position will be stopped out if price falls to the stop level; when short, the position will be stopped out if price rises to the stop level.
Advantage Analysis
The strategy has the following advantages:
Captures oversold and overbought opportunities in a timely manner by identifying reversals using the CCI indicator.
Avoids trading against the trend by incorporating trend direction analysis using moving averages.
Provides multiple optional stop loss methods that can be adjusted based on market conditions.
Simple and clear trading signals that are easy to implement.
Risk Analysis
The strategy also has the following risks:
The CCI indicator can easily generate false signals that cannot be completely avoided.
Improper stop loss placement may cause over-stopping out.
Inability to identify trends means too many unnecessary trades may be generated in ranging markets.
Inability to judge overall market direction may result in trading in the wrong direction.
To address these risks, the main optimization approaches are:
Incorporate other indicators to filter CCI signals.
Optimize stop placement through backtesting.
Add trend identification indicators to avoid choppy markets.
Determine direction of trade based on analysis of major support and resistance areas.
Optimization Directions
The main aspects for optimizing this strategy include:
CCI Parameter Optimization: Adjust CCI lookback period, optimize indicator parameters.
Stop Loss Optimization: Test different stop methods and select the optimal stop loss. Consider adding trailing stops.
Filter Optimization: Add additional filters like MACD, RSI to build a multi-indicator filtering system to reduce false signals.
Trend Filtering: Add trend identifying indicators like moving averages to avoid countertrend trades.
Auto Profit Taking: Build dynamic profit taking mechanisms to automatically take profits based on market volatility.
Conclusion
Overall, the DCCI Breakout Strategy is a very practical short-term trading system. It identifies overbought/oversold situations using the CCI indicator and incorporates the moving average for directional bias. Risk is managed through stop losses. The simple and clear signals make this strategy easy to implement for short-term trading. Continual testing and optimization can further improve strategy performance.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | false | Strategy Direction |
| v_input_2 | true | -----------------Strategy Inputs------------------- |
| v_input_3 | false | Strategy Stop Mult |
| v_input_4 | 16 | CCI Length |
| v_input_5 | 5 | WMA Length |
| v_input_6 | true | -----------------General Inputs------------------- |
| v_input_7 | true | Use Stop Loss and Take Profit |
| v_input_8 | 0 | Type Of Stop: ATR Stop | Swing Lo/Hi | Strategy Stop |
| v_input_9 | 10 | Swing Point Lookback |
| v_input_10 | 2 | Swing Point SL Perc Increment |
| v_input_11 | 14 | ATR Length |
| v_input_12 | 10 | ATR Multiple |
| v_input_13 | 1.5 | Take Profit Risk Reward Ratio |
| v_input_14 | true | Allow Direct Position Reverse |
| v_input_15 | false | Reverse Trades |
Source Pine Script
/*backtest
start: 2023-02-11 00:00:00
end: 2023-09-20 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © tweakerID

// ---From the "Bitcoin Trading Strategies" book, by David Hanson---

// After testing, works better with an ATR stop instead of the Strategy Stop. This paramater
// can be changed from the strategy Inputs panel.

// "CCI Scalping Strategy
// Recommended Timeframe: 5 minutes
// Indicators: 20 Period CCI, 20 WMA
// Long when: Price closes above 20 WMA and CCI is below -100, enter when CCI crosses above -100.
// Stop: Above 20 WMA"

//@version=4
strategy("CCI Scalping Strat",
     overlay=true,
     default_qty_type=strategy.percent_of_equity,
     default_qty_value=100,
     initial_capital=10000,
     commission_value=0.04,
     calc_on_every_tick=false,
     slippage=0)

direction = input(0, title = "Strategy Direction", type=input.integer, minval=-1, maxval=1)
strategy.risk.allow_entry_in(direction == 0 ? strategy.direction.all : (direction < 0 ? strategy.direction.short : strategy.direction.long))

/////////////////////// STRATEGY INPUTS ////////////////////////////////////////
title1=input(true, "-----------------Strategy Inputs-------------------")

i_Stop = input(0, step=.05, title="Strategy Stop Mult")*.01
i_CCI=input(16, title="CCI Length")
i_WMA=input(5, title="WMA Length")

/////////////////////// BACKTESTER /////////////////////////////////////////////
title2=input(true, "-----------------General Inputs-------------------")

// Backtester General Inputs
i_SL=input(true, title="Use Stop Loss and Take Profit")
i_SLType=input(defval="ATR Stop", title="Type Of Stop", options=["Strategy Stop", "Swing Lo/Hi", "ATR Stop"])
i_SPL=input(defval=10, title="Swing Point Lookback")
i_PercIncrement=input(defval=2, step=.1, title="Swing Point SL Perc Increment")*0.01
i_ATR = input(14, title="ATR Length")
i_ATRMult = input(10, step=.1, title="ATR Multiple")
i_TPRRR = input(1.5, step=.1, title="Take Profit Risk Reward Ratio")

// Bought and Sold Boolean Signal
bought = strategy.position_size > strategy.position_size[1]
 or strategy.position_size < strategy.position_size[1]

// Price Action Stop and Take Profit
LL=(lowest(i_SPL))*(1-i_PercIncrement)
HH=(highest(i_SPL))*(1+i_PercIncrement)
LL_price = valuewhen(bought, LL, 0)
HH_price = valuewhen(bought, HH, 0)
entry_LL_price = strategy.position_size > 0 ? LL_price : na
entry_HH_price = strategy.position_size < 0 ? HH_price : na
tp=strategy.position_avg_price + (strategy.position_avg_price - entry_LL_price)*i_TPRRR
stp=strategy.position_avg_price - (entry_HH_price - strategy.position_avg_price)*i_TPRRR

// ATR Stop
ATR=atr(i_ATR)*i_ATRMult
ATRLong = ohlc4 - ATR
ATRShort = ohlc4 + ATR
ATRLongStop = valuewhen(bought, ATRLong, 0)
ATRShortStop = valuewhen(bought, ATRShort, 0)
LongSL_ATR_price = strategy.position_size > 0 ? ATRLongStop : na
ShortSL_ATR_price = strategy.position_size < 0 ? ATRShortStop : na
ATRtp=strategy.position_avg_price + (strategy.position_avg_price - LongSL_ATR_price)*i_TPRRR
ATRstp=strategy.position_avg_price - (ShortSL_ATR_price - strategy.position_avg_price)*i_TPRRR

/////////////////////// STRATEGY LOGIC /////////////////////////////////////////

//CCI
CCI=cci(close, i_CCI)
//WMA
WMA=wma(close, i_WMA)

//Stops
LongStop=valuewhen(bought, WMA, 0)*(1-i_Stop)
ShortStop=valuewhen(bought, WMA, 0)*(1+i_Stop)
StratTP=strategy.position_avg_price + (strategy.position_avg_price - LongStop)*i_TPRRR
StratSTP=strategy.position_avg_price - (ShortStop - strategy.position_avg_price)*i_TPRRR

BUY = (close > WMA) and crossover(CCI , -100)
SELL = (close < WMA) and crossunder(CCI , 100)

//Trading Inputs
DPR=input(true, "Allow Direct Position Reverse")
reverse=input(false, "Reverse Trades")

// Entries
if reverse
    if not DPR
        strategy.entry("long", strategy.long, when=SELL and strategy.position_size == 0)
        strategy.entry("short", strategy.short, when=BUY and strategy.position_size == 0)
    else
        strategy.entry("long", strategy.long, when=SELL)
        strategy.entry("short", strategy.short, when=BUY)
else
    if not DPR
        strategy.entry("long", strategy.long, when=BUY and strategy.position_size == 0)
        strategy.entry("short", strategy.short, when=SELL and strategy.position_size == 0)
    else
        strategy.entry("long", strategy.long, when=BUY)
        strategy.entry("short", strategy.short, when=SELL)


SL= i_SLType == "Swing Lo/Hi" ? entry_LL_price : i_SLType == "ATR Stop" ? LongSL_ATR_price : LongStop
SSL= i_SLType == "Swing Lo/Hi" ? entry_HH_price : i_SLType == "ATR Stop" ? ShortSL_ATR_price : ShortStop
TP= i_SLType == "Swing Lo/Hi" ? tp : i_SLType == "ATR Stop" ? ATRtp : StratTP
STP= i_SLType == "Swing Lo/Hi" ? stp : i_SLType == "ATR Stop" ? ATRstp : StratSTP

strategy.exit("TP & SL", "long", limit=TP, stop=SL, when=i_SL)
strategy.exit("TP & SL", "short", limit=STP, stop=SSL, when=i_SL)

/////////////////////// PLOTS //////////////////////////////////////////////////


plot(WMA)
plot(i_SL and strategy.position_size > 0 ? SL : na , title='SL', style=plot.style_cross, color=color.red)
plot(i_SL and strategy.position_size < 0 ? SSL : na , title='SSL', style=plot.style_cross, color=color.red)
plot(i_SL and strategy.position_size > 0 ? TP : na, title='TP', style=plot.style_cross, color=color.green)
plot(i_SL and strategy.position_size < 0 ? STP : na, title='STP', style=plot.style_cross, color=color.green)
// Draw price action setup arrows
plotshape(BUY ? 1 : na, style=shape.triangleup, location=location.belowbar,
 color=color.green, title="Bullish Setup", size=size.auto)
plotshape(SELL ? 1 : na, style=shape.triangledown, location=location.abovebar,
 color=color.red, title="Bearish Setup", size=size.auto)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-18. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/DCCI-Breakout-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Choppiness K line Breakthrough StrategyPine Script · Breakout · 2h
- Price Action Structural Breakout Strategy with Trailing StopPine Script · Breakout · 2m
- ATR Trailing Stops StrategyPine Script · Breakout · 1h
- ATR Trend Breakout StrategyPine Script · Breakout · 1d
- Advanced Multi Pattern Breakout Trading StrategyPine Script · Breakout · 1d
- BB Breakout StrategyPine Script · Breakout · 1d