Strategy vault / Trend following
Double Moving Average Crossover Strategy
The double moving average crossover strategy is a trend-following strategy that uses the crossover of two moving averages of different periods as trading signals. It enters long or short positions when the fast MA…
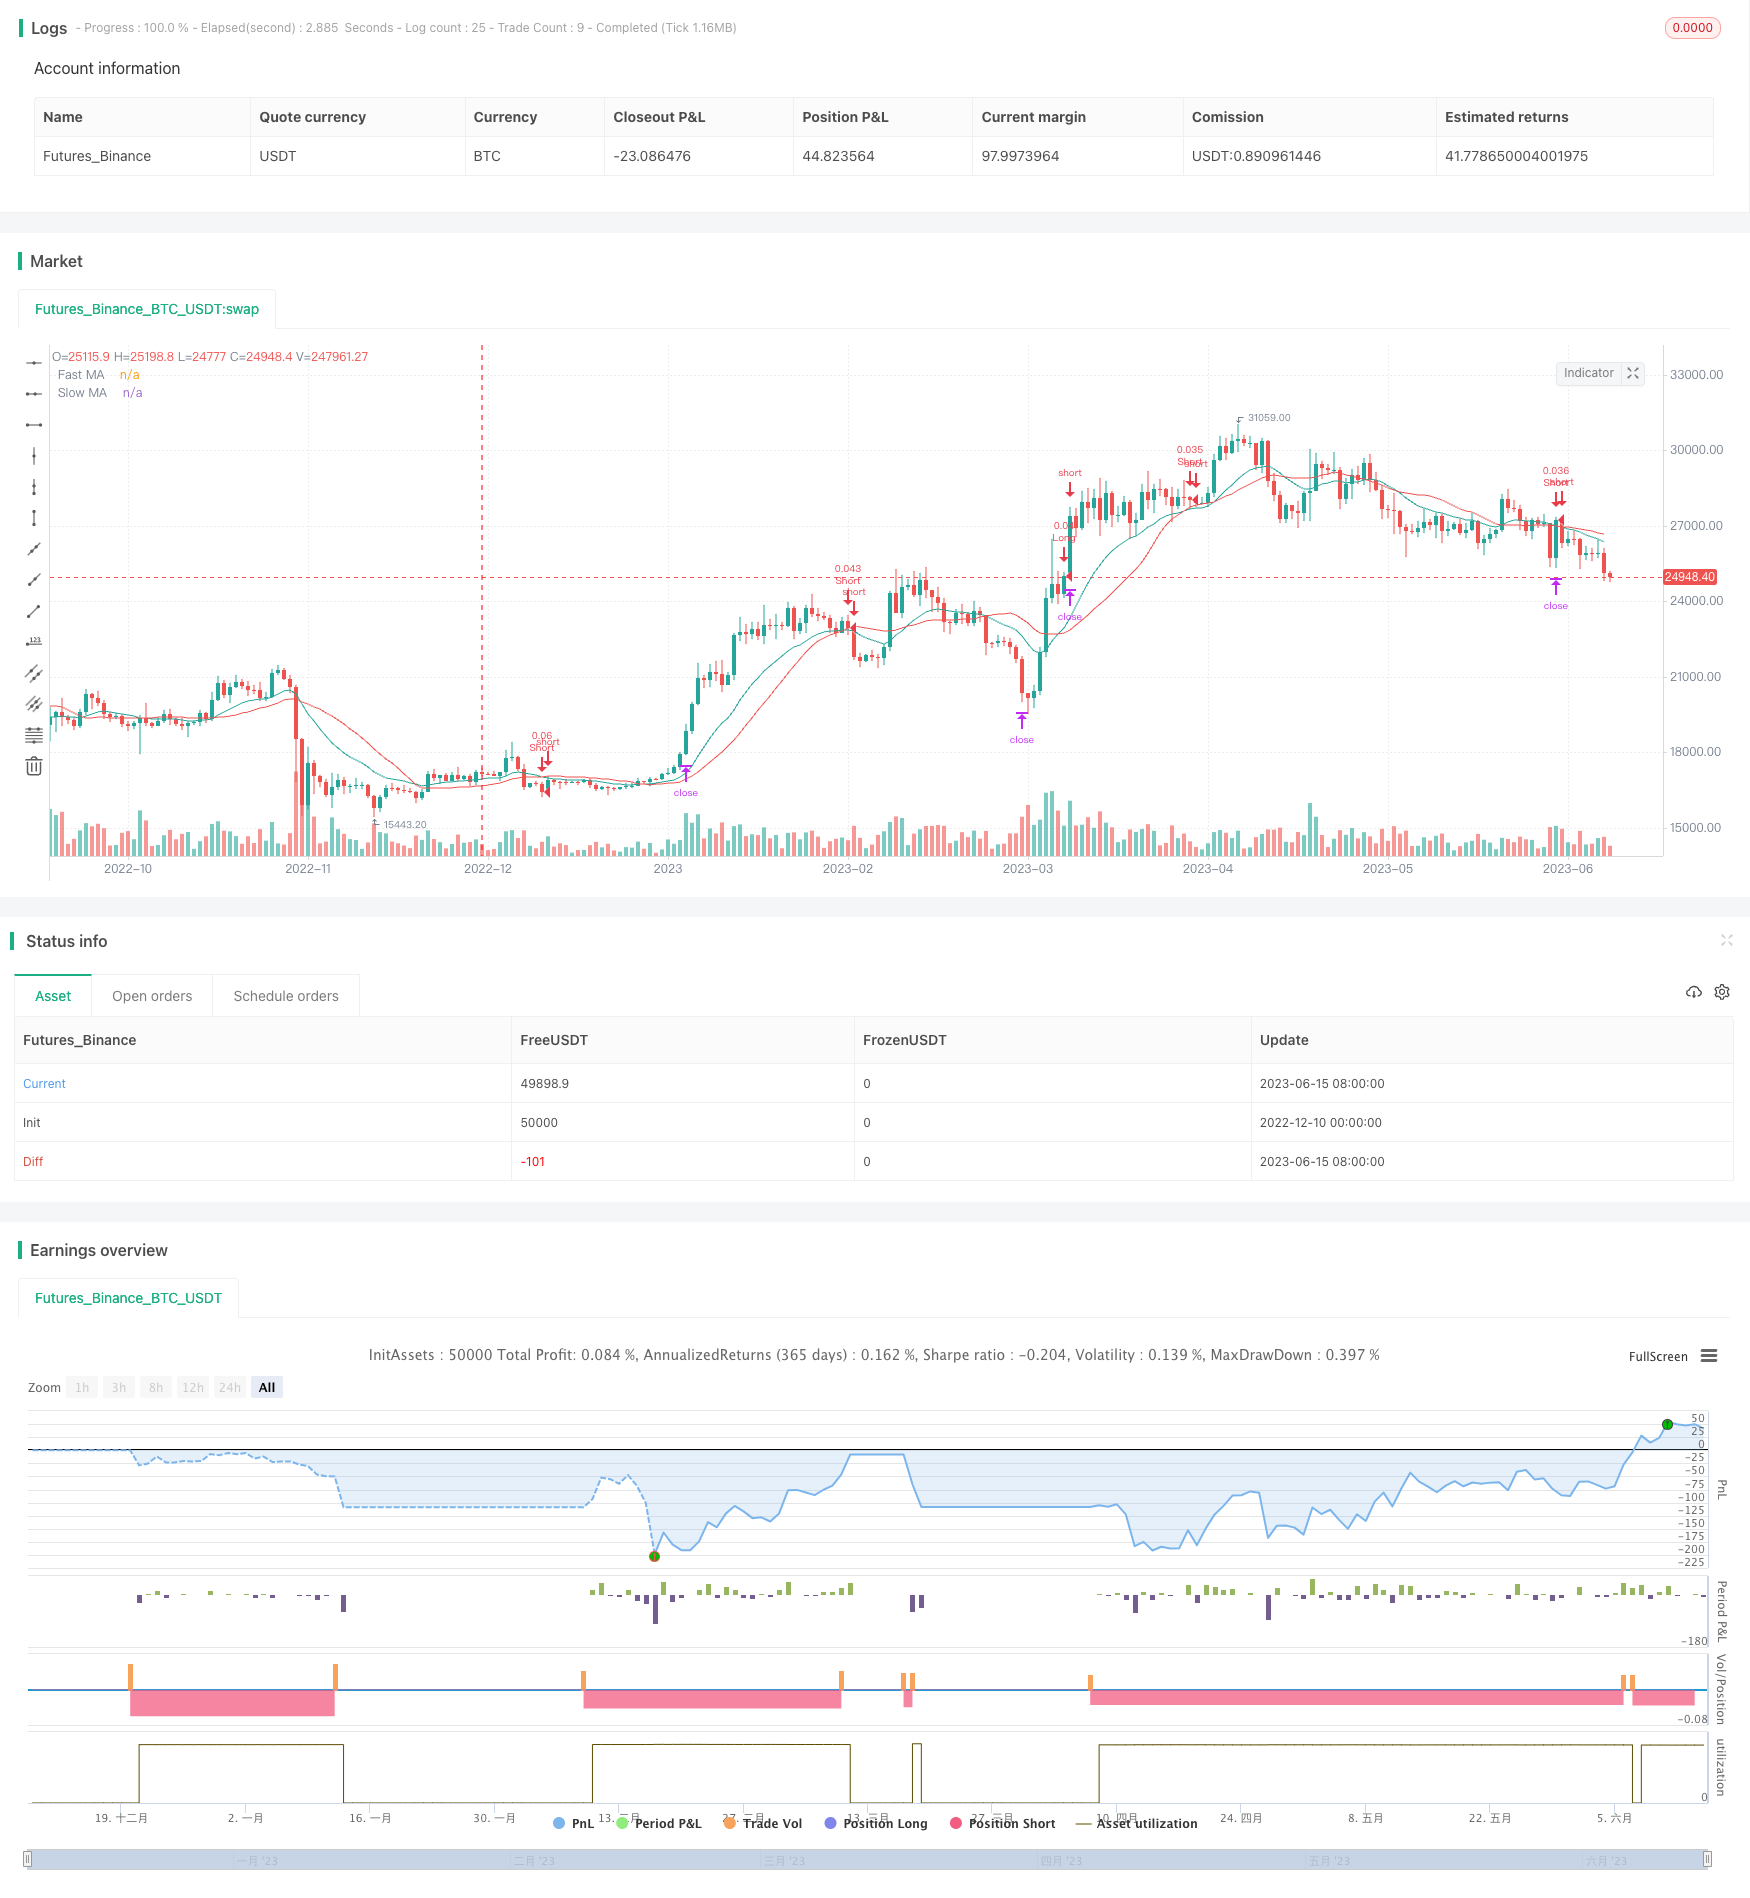
Overview
The double moving average crossover strategy is a trend-following strategy that uses the crossover of two moving averages of different periods as trading signals. It enters long or short positions when the fast MA crosses above or below the slow MA and determines trend direction after the crossover. It can capture intermediate-term trends while reducing unnecessary trading frequency from excessive fluctuations.
Strategy Logic
The strategy employs two moving averages: a fast MA with a shorter period (e.g. 15 periods) to capture short-term price moves, and a slow MA with a longer period (e.g. 21 periods) to identify major trend direction. Trading signals are generated from the crossover between the two MAs: the fast MA crossing above the slow MA gives buy signals, while the fast MA crossing below gives sell signals.
By tuning the MA period combinations, the strategy can adjust the timeframe of trends to capture. Shorter MA combos target short-term oscillations while longer MA combos filter out noise and focus on longer-term trends only.
The strategy also incorporates risk management modules including take profit, stop loss and trailing stop loss. These help limit the max profit/loss of individual trades and contain overall risk.
Advantages
The double MA strategy has the following edges:
- Simple logic and easy to understand/implement;
- Flexibility to adapt to market conditions by tuning MA periods;
- Stability from fewer trade signals;
- Effective risk control via stop losses;
- Ease of optimization on MA, risk parameters etc.
Risks
There are also some risks to consider:
- Excessive crossovers and trading frequency during range-bound markets;
- Lagging MAs may miss price reversal points and fail to stop loss in time;
- Vulnerability to false breakouts resulting in unnecessary losses;
- General price tracking inaccuracy due to lag of MAs.
These weaknesses can be alleviated via optimizations like filtering signals, trailing stop loss etc.
Enhancement Opportunities
The strategy can be enhanced in aspects like:
- Adding filters on volume or volatility to avoid whipsaws;
- Testing more MA types and fine-tuning periods/formulas to fit different products and timeframes;
- Examining MA types like EMA, LWMA for fastest price tracking;
- Automating MA tuning and stop loss sizing with machine learning;
- Alternate stop loss techniques e.g. gap, average price, chandelier.
Significant lift in win rate, risk-adjusted returns is expected from these augmentations.
Conclusion
Overall, the dual moving average crossover strategy offers simplicity, flexibility and controllable risks. Its ease of implementation and optimization makes it an ideal initial quant strategy. With recurrent testing and tuning, it has the credentials to evolve into a robust system over time.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1_ohlc4 | 0 | Fast MA Source: ohlc4 | high | low | open | hl2 | hlc3 | hlcc4 | close |
| v_input_2 | 15 | Fast MA Period |
| v_input_3_ohlc4 | 0 | Slow MA Source: ohlc4 | high | low | open | hl2 | hlc3 | hlcc4 | close |
| v_input_4 | 21 | Slow MA Period |
| v_input_5 | false | Invert Trade Direction? |
| v_input_6 | 100 | Take Profit percentage(0.1%) |
| v_input_7 | 100 | Stop Loss |
| v_input_8 | false | Trailing Stop Loss |
| v_input_9 | false | Trailing Stop Loss Offset |
| v_input_10 | true | Use Start Time Limiter? |
| v_input_11 | 2018 | Start From Year |
| v_input_12 | 5 | Start From Month |
| v_input_13 | true | Start From Day |
| v_input_14 | false | Start From Hour |
| v_input_15 | false | Start From Minute |
Source Pine Script
/*backtest
start: 2022-12-10 00:00:00
end: 2023-06-16 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3
strategy(title = "Silent Trader Strategy", shorttitle = "Silent Trader", overlay = true, pyramiding = 0, default_qty_type = strategy.cash, default_qty_value = 1000, commission_value = 0.0675, initial_capital = 1000, currency = currency.USD, calc_on_order_fills = true, calc_on_every_tick = true)

maFastSource   = input(defval = ohlc4, title = "Fast MA Source")
maFastLength   = input(defval = 15, title = "Fast MA Period", minval = 1)
maSlowSource   = input(defval = ohlc4, title = "Slow MA Source")
maSlowLength   = input(defval = 21, title = "Slow MA Period", minval = 1)

tradeInvert     = input(defval = false, title = "Invert Trade Direction?")
inpTakeProfit   = input(defval = 100, title = "Take Profit percentage(0.1%)", minval = 0)
inpStopLoss     = input(defval = 100, title = "Stop Loss", minval = 0)
inpTrailStop    = input(defval = 0, title = "Trailing Stop Loss", minval = 0)
inpTrailOffset  = input(defval = 0, title = "Trailing Stop Loss Offset", minval = 0)

useTakeProfit   = inpTakeProfit  >= 1 ? inpTakeProfit  : na
useStopLoss     = inpStopLoss    >= 1 ? inpStopLoss    : na
useTrailStop    = inpTrailStop   >= 1 ? inpTrailStop   : na
useTrailOffset  = inpTrailOffset >= 1 ? inpTrailOffset : na

useTimeLimit    = input(defval = true, title = "Use Start Time Limiter?")
startYear       = input(defval = 2018, title = "Start From Year",  minval = 0, step = 1)
startMonth      = input(defval = 05, title = "Start From Month",  minval = 0,step = 1)
startDay        = input(defval = 01, title = "Start From Day",  minval = 0,step = 1)
startHour       = input(defval = 00, title = "Start From Hour",  minval = 0,step = 1)
startMinute     = input(defval = 00, title = "Start From Minute",  minval = 0,step = 1)

startTimeOk() =>
    inputTime = timestamp(syminfo.timezone, startYear, startMonth, startDay, startHour, startMinute)
    timeOk = time > inputTime ? true : false
    r = (useTimeLimit and timeOk) or not useTimeLimit

maFast = ema(maFastSource, maFastLength)
maSlow = sma(maSlowSource, maSlowLength)

fast = plot(maFast, title = "Fast MA", color = #26A69A, linewidth = 1, style = line, transp = 50)
slow = plot(maSlow, title = "Slow MA", color = #EF5350, linewidth = 1, style = line, transp = 50)

aboveBelow = maFast >= maSlow ? true : false
tradeDirection = tradeInvert ? aboveBelow ? false : true : aboveBelow ? true : false

if( startTimeOk() )
    enterLong = not tradeDirection[1] and tradeDirection
    exitLong = tradeDirection[1] and not tradeDirection
    strategy.entry( id = "Long", long = true, when = enterLong )
    //strategy.close( id = "Long", when = exitLong )

    enterShort = tradeDirection[1] and not tradeDirection
    exitShort = not tradeDirection[1] and tradeDirection
    strategy.entry( id = "Short", long = false, when = enterShort )
    //strategy.close( id = "Short", when = exitShort )

    strategy.exit("Exit Long", from_entry = "Long",  profit = close * useTakeProfit / 1000 / syminfo.mintick, loss = close * useStopLoss / 1000 / syminfo.mintick, trail_points = close * useTrailStop / 1000 / syminfo.mintick, trail_offset = close * useTrailOffset / 1000 / syminfo.mintick)
strategy.exit("Exit Short", from_entry = "Short", profit = close * useTakeProfit / 1000 / syminfo.mintick, loss = close * useStopLoss / 1000 / syminfo.mintick, trail_points = close * useTrailStop / 1000 / syminfo.mintick, trail_offset = close * useTrailOffset / 1000 / syminfo.mintick)Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-11. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Double-Moving-Average-Crossover-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- Bollinger Band Moving Average Crossover StrategyPine Script · Trend following · 1h
- Bollinger Bands and EMA Trend Following StrategyPine Script · Trend following · 1h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Candlestick Pattern Trend Filter StrategyPine Script · Trend following · 1d