Strategy vault / Mean reversion
Double Strategy Combination Stochastic Slow and Relative Strength Index
This strategy combines the classic Stochastic Slow strategy and Relative Strength Index (RSI) strategy to form a double strategy. It will open position when Stochastic exceeds 80 (short) or drops below 20 (long)…
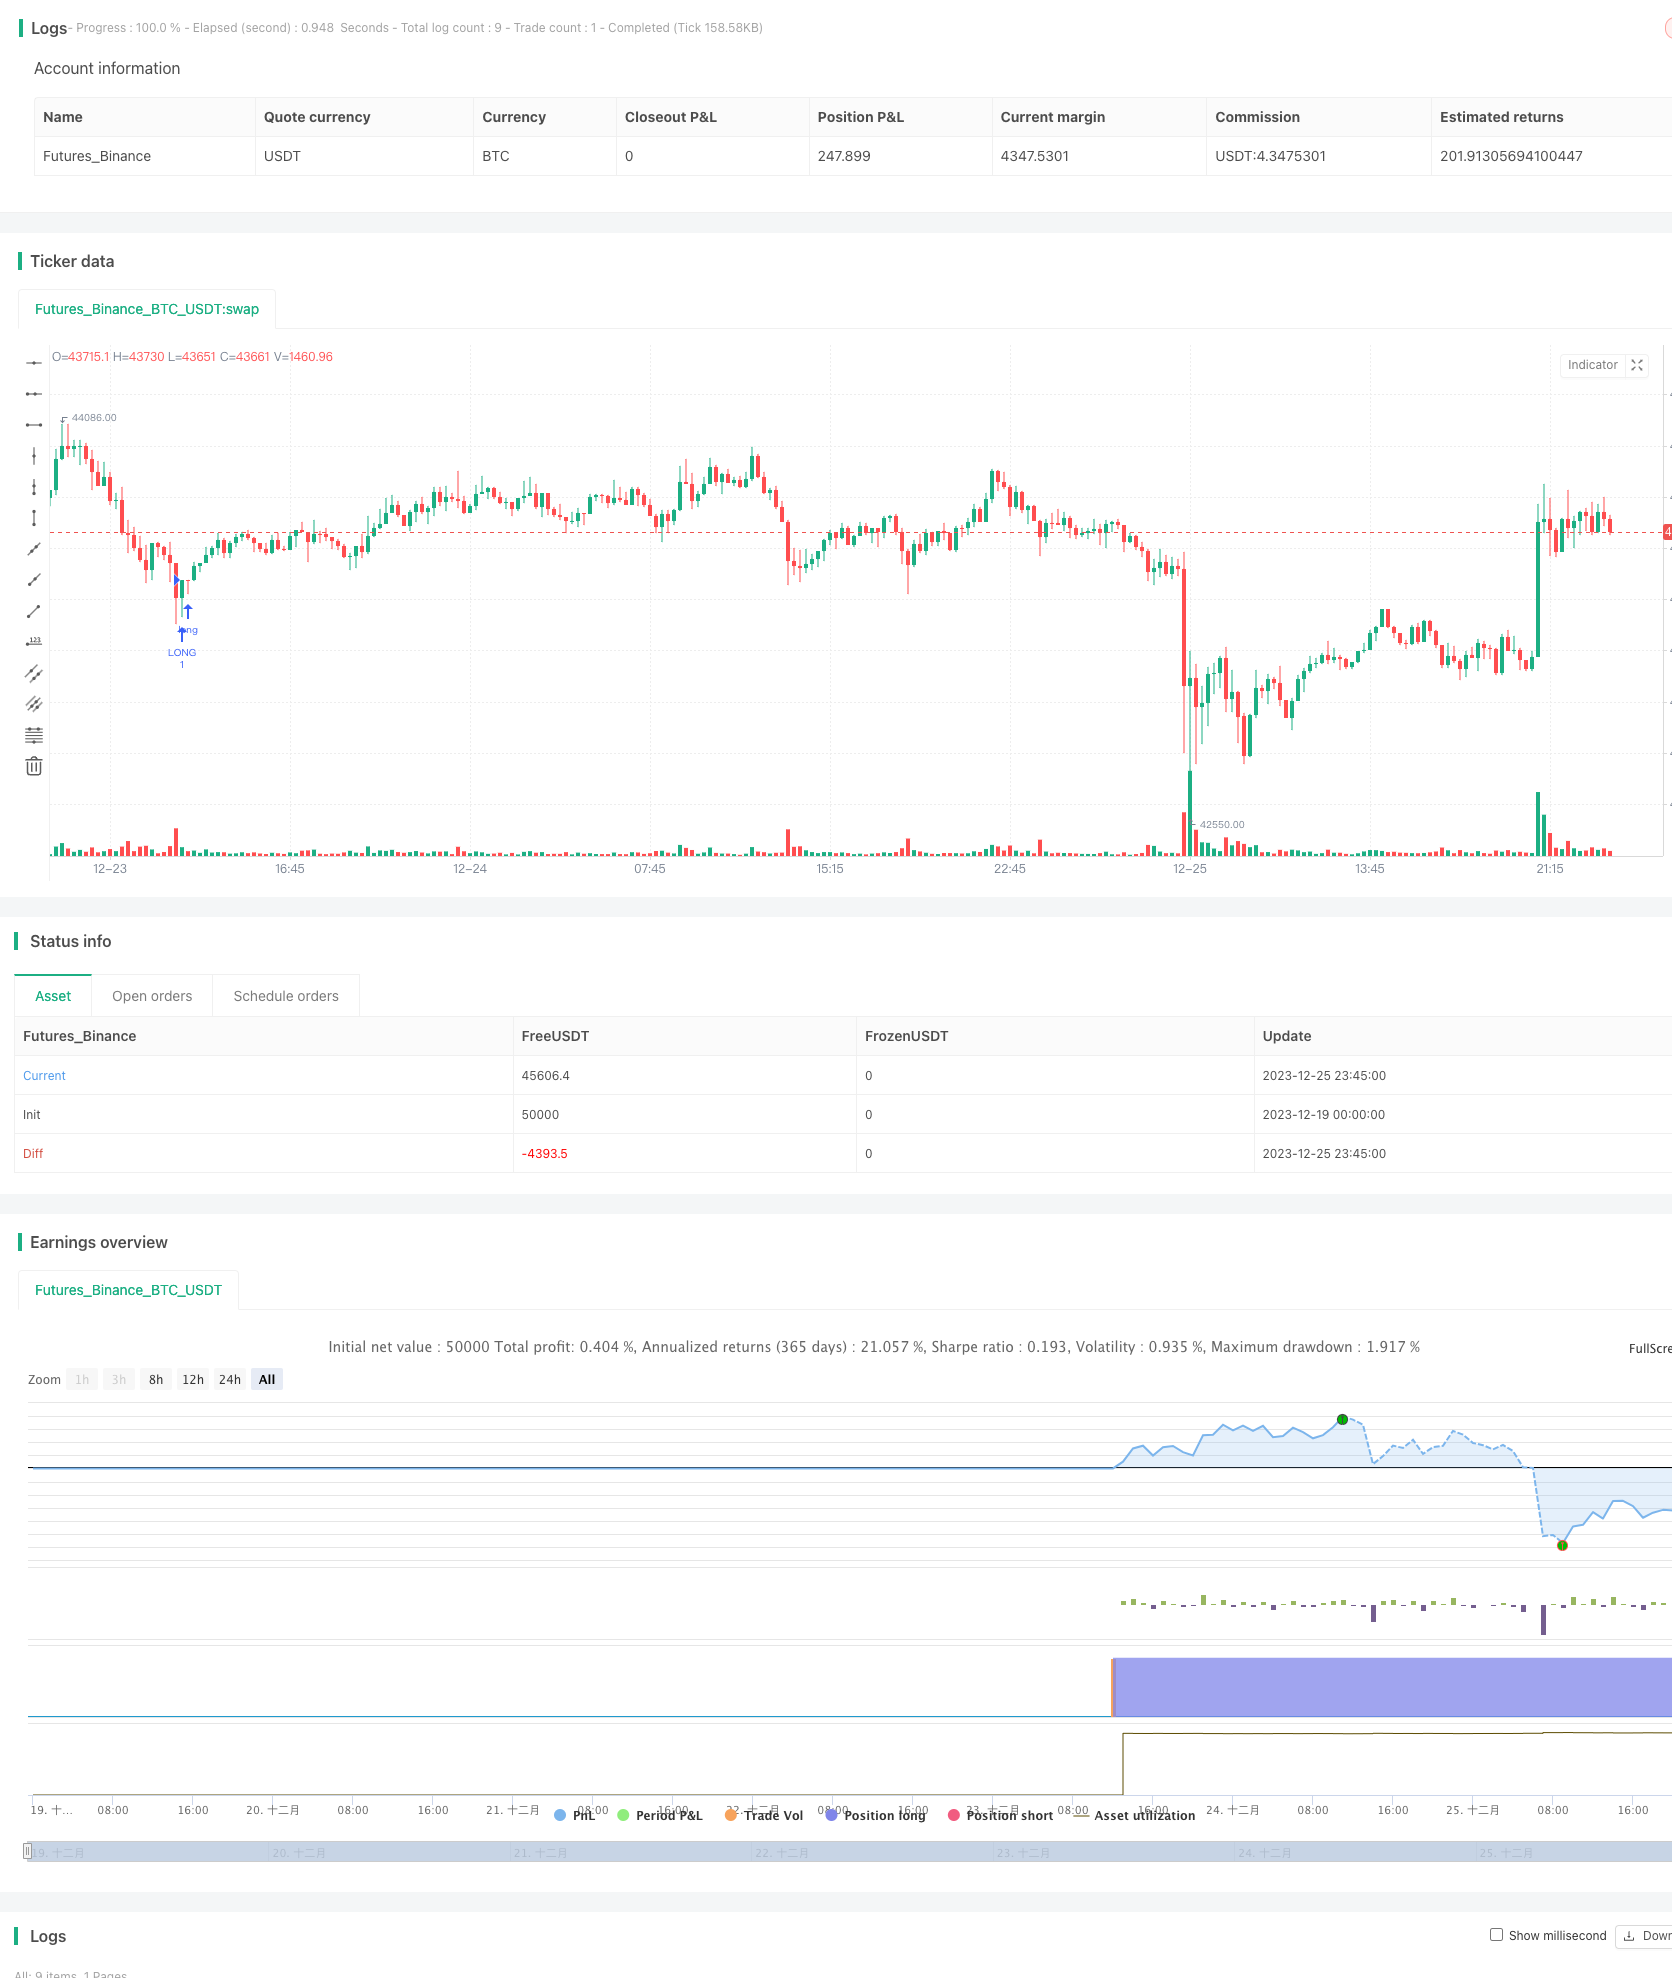
Overview
This strategy combines the classic Stochastic Slow strategy and Relative Strength Index (RSI) strategy to form a double strategy. It will open position when Stochastic exceeds 80 (short) or drops below 20 (long) meanwhile RSI exceeds 70 (short) or drops below 30 (long).
Strategy Logic
This strategy mainly utilizes two classic indicators – Stochastic Slow indicator and RSI indicator, and sets threshold values to determine overbought and oversold conditions.
Stochastic Slow Part:
- Set Stochlength as 14, the lookback period for Stochastic calculation
- Set StochOverBought as 80 and StochOverSold as 20, threshold values for overbought and oversold
- Set smoothK as 3 and smoothD as 3, smoothing parameters for %K and %D line
The calculated %K and %D lines are named as k and d in the code.
When %K crosses over %D from below, it is a long signal. When crosses under from above, it is a short signal. Combine with overbought/oversold judgment, it can be used to identify opportunities.
RSI Part:
- Set RSIlength as 14, the lookback period for RSI calculation
- Set RSIOverBought as 70 and RSIOverSold as 30, threshold values for overbought and oversold
The calculated RSI indicator is named as vrsi in the code.
When RSI rises above 70, it sends an overbought signal. When drops below 30, it sends an oversold signal.
Double Strategy Entry Logic:
This strategy will only open position when both Stochastic and RSI indicate overbought/oversold signals at the same time, meaning passing their own threshold values.
This combination utilizes the complementary property of two indicators to increase signal reliability and decrease false signals.
Advantage Analysis
The advantages of this double strategy combination are:
- Combination of two indicators can validate each other, decrease false signals and increase signal quality
- Stochastic judges overbought/oversold conditions, RSI does the same job. Combination makes the results more reliable.
- Stochastic uses %K and %D crossover system, smoothing parameters make it robust to outliers
- RSI reacts fast to latest changes, Stochastic judges middle-to-long term trends and turning points. Complete strategy.
- Conservative trading style, only open positions when both indicators agree. Less trades, avoid over-trading.
Risks and Solutions
There are some risks associated with this strategy:
Parameter tuning risk
Improper parameter settings may lead to missing good opportunities or generating false signals. We can optimize parameters through quantitative algorithms or manual tuning to find the best combination.
Lack of signals
Due to the dual indicator system, signal frequency could be relatively low and position utilization ratio is not high. We can properly relax the parameters to generate more entry signals.
Lagging risk
Both Stochastic and RSI have some lagging effect, which may cause missing rapid chances. More sensitive indicators can be introduced for assistance.
Instruments specificity
This strategy may fits better for some violent fluctuated instruments like stock indices and gold. For smooth instruments, it may not be applicable.
Optimization Directions
This strategy can be further optimized in the following aspects:
Parameter optimization
Optimize the parameters quantitatively or manually to find the best parameter combination.
Introduce stop loss mechanism
Set stop loss based on price movement or percentage to control single trade loss.
Combine with other indicators
Introduce other indicators like volume, moving average to assist judging signal quality.
Relax double strategy conditions
Appropriately relax the thresholds of double strategy to generate more entry signals.
Conclusion
This strategy combines Stochastic Slow and RSI in double-confirmation mode, entering positions only when both indicators agree on overbought/oversold signals. It features high signal reliability, conservative trading style etc. Also has some risks like parameter tuning, lack of signals. Further improvements can be made through parameter optimization, stop loss introduction, adding assisting indicators to enhance stability.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 14 | lookback length of Stochastic |
| v_input_2 | 80 | Stochastic overbought condition |
| v_input_3 | 20 | Stochastic oversold condition |
| v_input_4 | 3 | smoothing of Stochastic %K |
| v_input_5 | 3 | moving average of Stochastic %K |
| v_input_6 | 14 | lookback length of RSI |
| v_input_7 | 70 | RSI overbought condition |
| v_input_8 | 30 | RSI oversold condition |
Source Pine Script
/*backtest
start: 2023-12-19 00:00:00
end: 2023-12-26 00:00:00
period: 15m
basePeriod: 5m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=2
strategy("Stochastic + RSI, Double Strategy (by ChartArt)", shorttitle="CA_-_RSI_Stoch_Strat", overlay=true)

// ChartArt's Stochastic Slow + Relative Strength Index, Double Strategy
//
// Version 1.0
// Idea by ChartArt on October 23, 2015.
//
// This strategy combines the classic RSI
// strategy to sell when the RSI increases
// over 70 (or to buy when it falls below 30),
// with the classic Stochastic Slow strategy
// to sell when the Stochastic oscillator
// exceeds the value of 80 (and to buy when
// this value is below 20).
//
// This simple strategy only triggers when
// both the RSI and the Stochastic are together
// in overbought or oversold conditions.
//
// List of my work:
// https://www.tradingview.com/u/ChartArt/


///////////// Stochastic Slow
Stochlength = input(14, minval=1, title="lookback length of Stochastic")
StochOverBought = input(80, title="Stochastic overbought condition")
StochOverSold = input(20, title="Stochastic oversold condition")
smoothK = input(3, title="smoothing of Stochastic %K ")
smoothD = input(3, title="moving average of Stochastic %K")
k = sma(stoch(close, high, low, Stochlength), smoothK)
d = sma(k, smoothD)


///////////// RSI
RSIlength = input( 14, minval=1 , title="lookback length of RSI")
RSIOverBought = input( 70  , title="RSI overbought condition")
RSIOverSold = input( 30  , title="RSI oversold condition")
RSIprice = close
vrsi = rsi(RSIprice, RSIlength)


///////////// Double strategy: RSI strategy + Stochastic strategy

if (not na(k) and not na(d))
    if (crossover(k,d) and k < StochOverSold)
        if (not na(vrsi)) and (crossover(vrsi, RSIOverSold))
            strategy.entry("LONG", strategy.long, comment="StochLE + RsiLE")


if (crossunder(k,d) and k > StochOverBought)
    if (crossunder(vrsi, RSIOverBought))
        strategy.entry("SHORT", strategy.short, comment="StochSE + RsiSE")


//plot(strategy.equity, title="equity", color=red, linewidth=2, style=areabr)WQQQQQQQQQQQQQQQQQQQQQQQQQQQQQQQQQQQQQQQPublished by ChaoZhang on the FMZ strategy square · last modified 2023-12-27. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Double-Strategy-Combination-Stochastic-Slow-and-Relative-Strength-Index.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- Bollinger Bands Stochastic RSI Extreme Strategy BBSR Extreme StrategyPine Script · Mean reversion · 1h
- BuySell Strategy depends on AOStochRSIATRPine Script · Mean reversion · 30m
- Byron Serpent Cloud Quant StrategyPine Script · Mean reversion · 1h
- Dual Momentum Trend Reversal Strategy Based on RSI and Stochastic RSIPine Script · Mean reversion · 1h
- Dynamic Adaptive Multi Timeframe Trend Following and Range Reversal Hybrid StrategyPine Script · Mean reversion · 2d