Dual directional Trend Tracking Strategy Based on Range Breakout
This strategy calculates the last highest price (lastbull) and the last lowest price (lastbear). It then compares the current price with lastbull and lastbear to determine if the price has entered a certain range and…
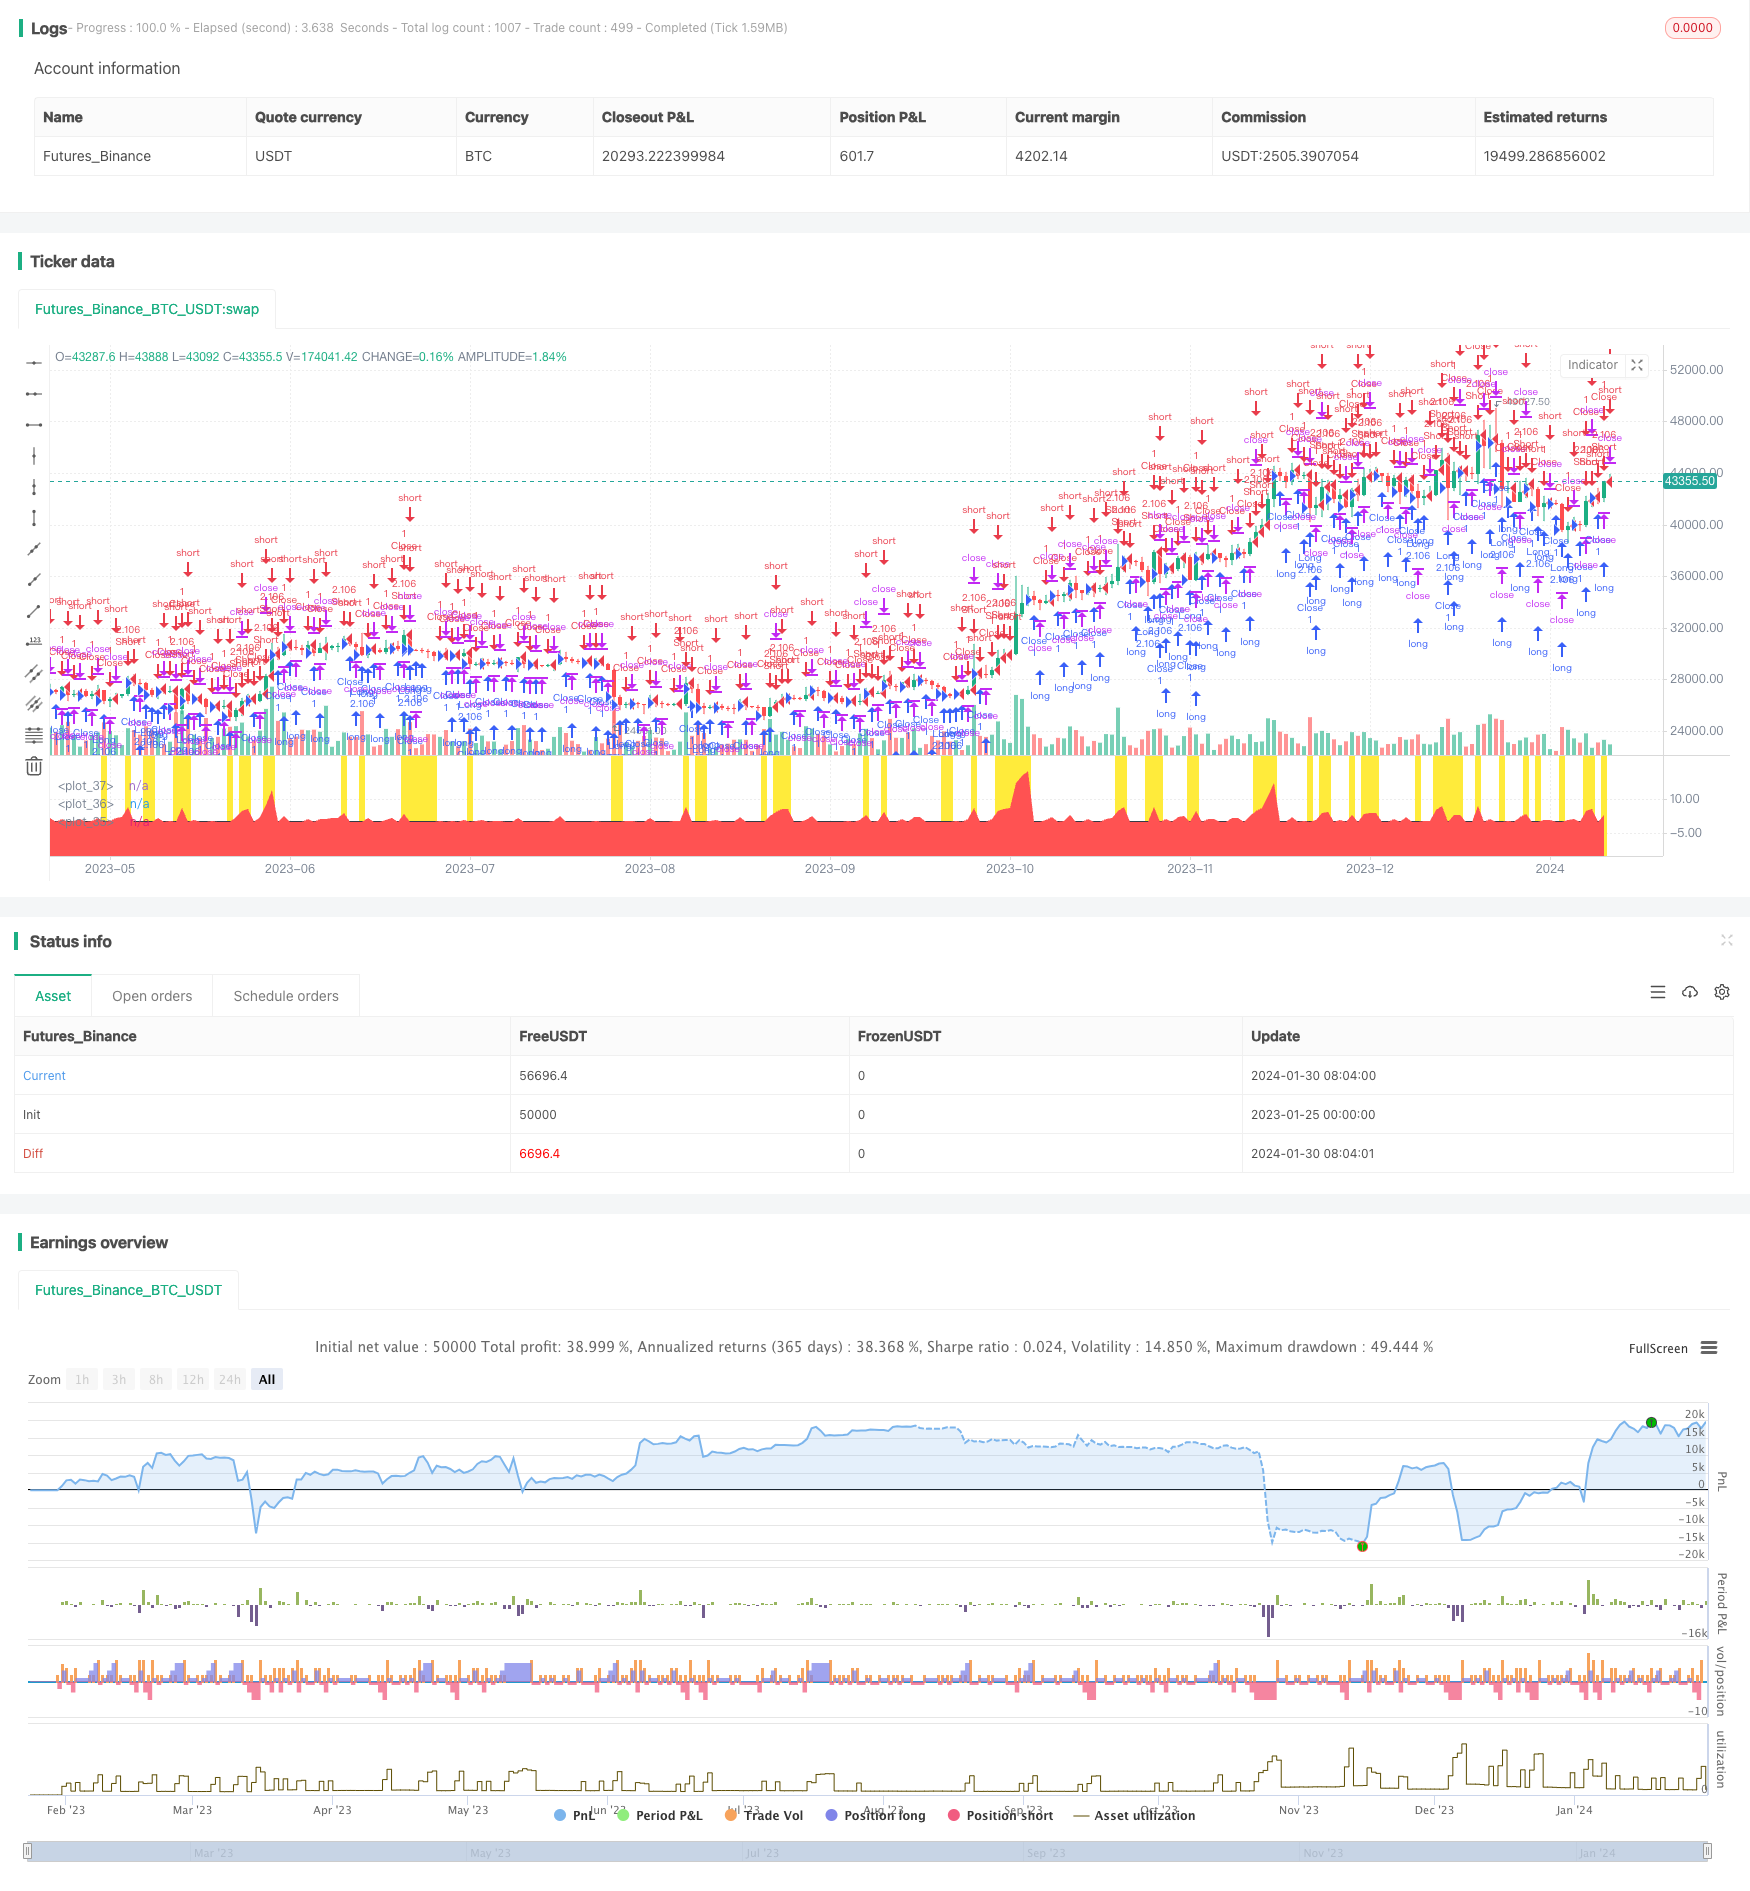
Overview
This strategy calculates the last highest price (lastbull) and the last lowest price (lastbear). It then compares the current price with lastbull and lastbear to determine if the price has entered a certain range and thus generates trading signals. It goes long when the price rises over lastbull by a certain percentage, and goes short when the price falls below lastbear by a certain percentage.
Strategy Logic
The strategy first calculates the last highest price lastbull and the last lowest price lastbear. Then it calculates the change percentage ddl of current price close relative to lastbull, and the change percentage dds relative to lastbear.
When ddl is lower than the configured long signal threshold signallong, a long signal up is generated. When dds is higher than the configured short signal threshold signalshort, a short signal dn is generated.
Upon receiving long signal, it opens long position if the needlong parameter is true. Upon receiving short signal, it opens short position if the needshort parameter is true. The position size capital is calculated from account equity.
It closes long position when price rises after opening long, and closes short position when price falls after opening short.
Advantage Analysis
This strategy combines trend and range analysis. It can catch trends and generate trading signals from range breakouts. Compared to simple trend tracking strategies, it can quickly catch new trend direction after range breakout.
The parameters are highly configurable for different products. The trading time range can be configured to avoid significant events.
Risk Analysis
There is no stop loss mechanism in this strategy to limit the loss per trade. The position sizing can be impacted heavily by price fluctuation when the trading range is large.
Stop loss can be added to limit the per trade loss. The position sizing algorithm can be customized based on products to stabilize the position size.
Optimization Directions
- Add moving stop loss to control per trade loss risk
- Improve position sizing algorithm, e.g. use ATR, to stabilize position size
- Add filtering for entry signals, e.g. only enter when golden cross happens
- Trade multiple products with correlation to lower systemic risk
Summary
This strategy combines trend analysis and range breakout to generate trading signals, which can catch new trends and take advantage of range bound characteristics. The parameters are highly configurable for different products. There is large room for optimization to adapt more complex market environments.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | Long |
| v_input_2 | true | Short |
| v_input_3 | 100 | Lot |
| v_input_4 | 3 | Short, % |
| v_input_5 | -3 | Long, % |
| v_input_6 | 1900 | From Year |
| v_input_7 | 2100 | To Year |
| v_input_8 | true | From Month |
| v_input_9 | 12 | To Month |
| v_input_10 | true | From day |
| v_input_11 | 31 | To day |
Source Pine Script
/*backtest
start: 2023-01-25 00:00:00
end: 2024-01-31 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//Noro
//2019

//@version=4
strategy(title = "Noro's DDL Strategy", shorttitle = "DDL str", overlay = false, default_qty_type = strategy.percent_of_equity, default_qty_value = 100, pyramiding = 3)

//Settings
needlong = input(true, title = "Long")
needshort = input(true, title = "Short")
capital = input(100, defval = 100, minval = 1, maxval = 10000, title = "Lot")
signalshort = input(3.0, title = "Short, %")
signallong = input(-3.0, title = "Long, %")
fromyear = input(1900, defval = 1900, minval = 1900, maxval = 2100, title = "From Year")
toyear = input(2100, defval = 2100, minval = 1900, maxval = 2100, title = "To Year")
frommonth = input(01, defval = 01, minval = 01, maxval = 12, title = "From Month")
tomonth = input(12, defval = 12, minval = 01, maxval = 12, title = "To Month")
fromday = input(01, defval = 01, minval = 01, maxval = 31, title = "From day")
today = input(31, defval = 31, minval = 01, maxval = 31, title = "To day")

//Levels
bull = close > close[1] ? 1 : 0
bear = close < close[1] ? 1 : 0
lastbull = 0.0
lastbull := bull ? close : lastbull[1]
lastbear = 0.0
lastbear := bear ? close : lastbear[1]

//Signals
ddl = ((close / lastbull) - 1) * 100
up = ddl < signallong
dds = ((close / lastbear) - 1) * 100
dn = dds > signalshort

//Lines
plot(dds, style = plot.style_area, color = color.red, transp = 0)
plot(ddl, style = plot.style_area, color = color.lime, transp = 0)
plot(0, color = color.black, linewidth = 2, transp = 0)

//Background
col = (up and needlong) or (dn and needshort) ? color.yellow : na
bgcolor(col, transp = 20)

//Orders
lot = 0.0
lot := strategy.position_size == 0 ? strategy.equity / close * capital / 100 : lot[1]
truetime = true
if up
    strategy.entry("Long", strategy.long, lot, when = needlong and truetime)
if dn
    strategy.entry("Short", strategy.short, lot, when = needshort and truetime)
if strategy.position_size > 0 and close > open
    strategy.entry("Close", strategy.short, 0)
if strategy.position_size < 0 and close < open
strategy.entry("Close", strategy.long, 0)Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-01. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-directional-Trend-Tracking-Strategy-Based-on-Range-Breakout.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ATR Trailing Stops StrategyPine Script · Breakout · 1h
- ATR Trend Breakout StrategyPine Script · Breakout · 1d
- Advanced Multi Pattern Breakout Trading StrategyPine Script · Breakout · 1d
- BB Breakout StrategyPine Script · Breakout · 1d
- Bollinger Band Breakout Trend Following StrategyPine Script · Breakout · 1d
- Breakout Strategy Based on Turtle TradingPine Script · Breakout · 1d