Strategy vault / Mean reversion
Dual Factor Momentum Tracking Reversal Strategy
This strategy combines the price reversal factor and momentum factor of stocks to construct a dual-factor model for capturing opportunities arising from short-term reversals and long-term persistence in the market…
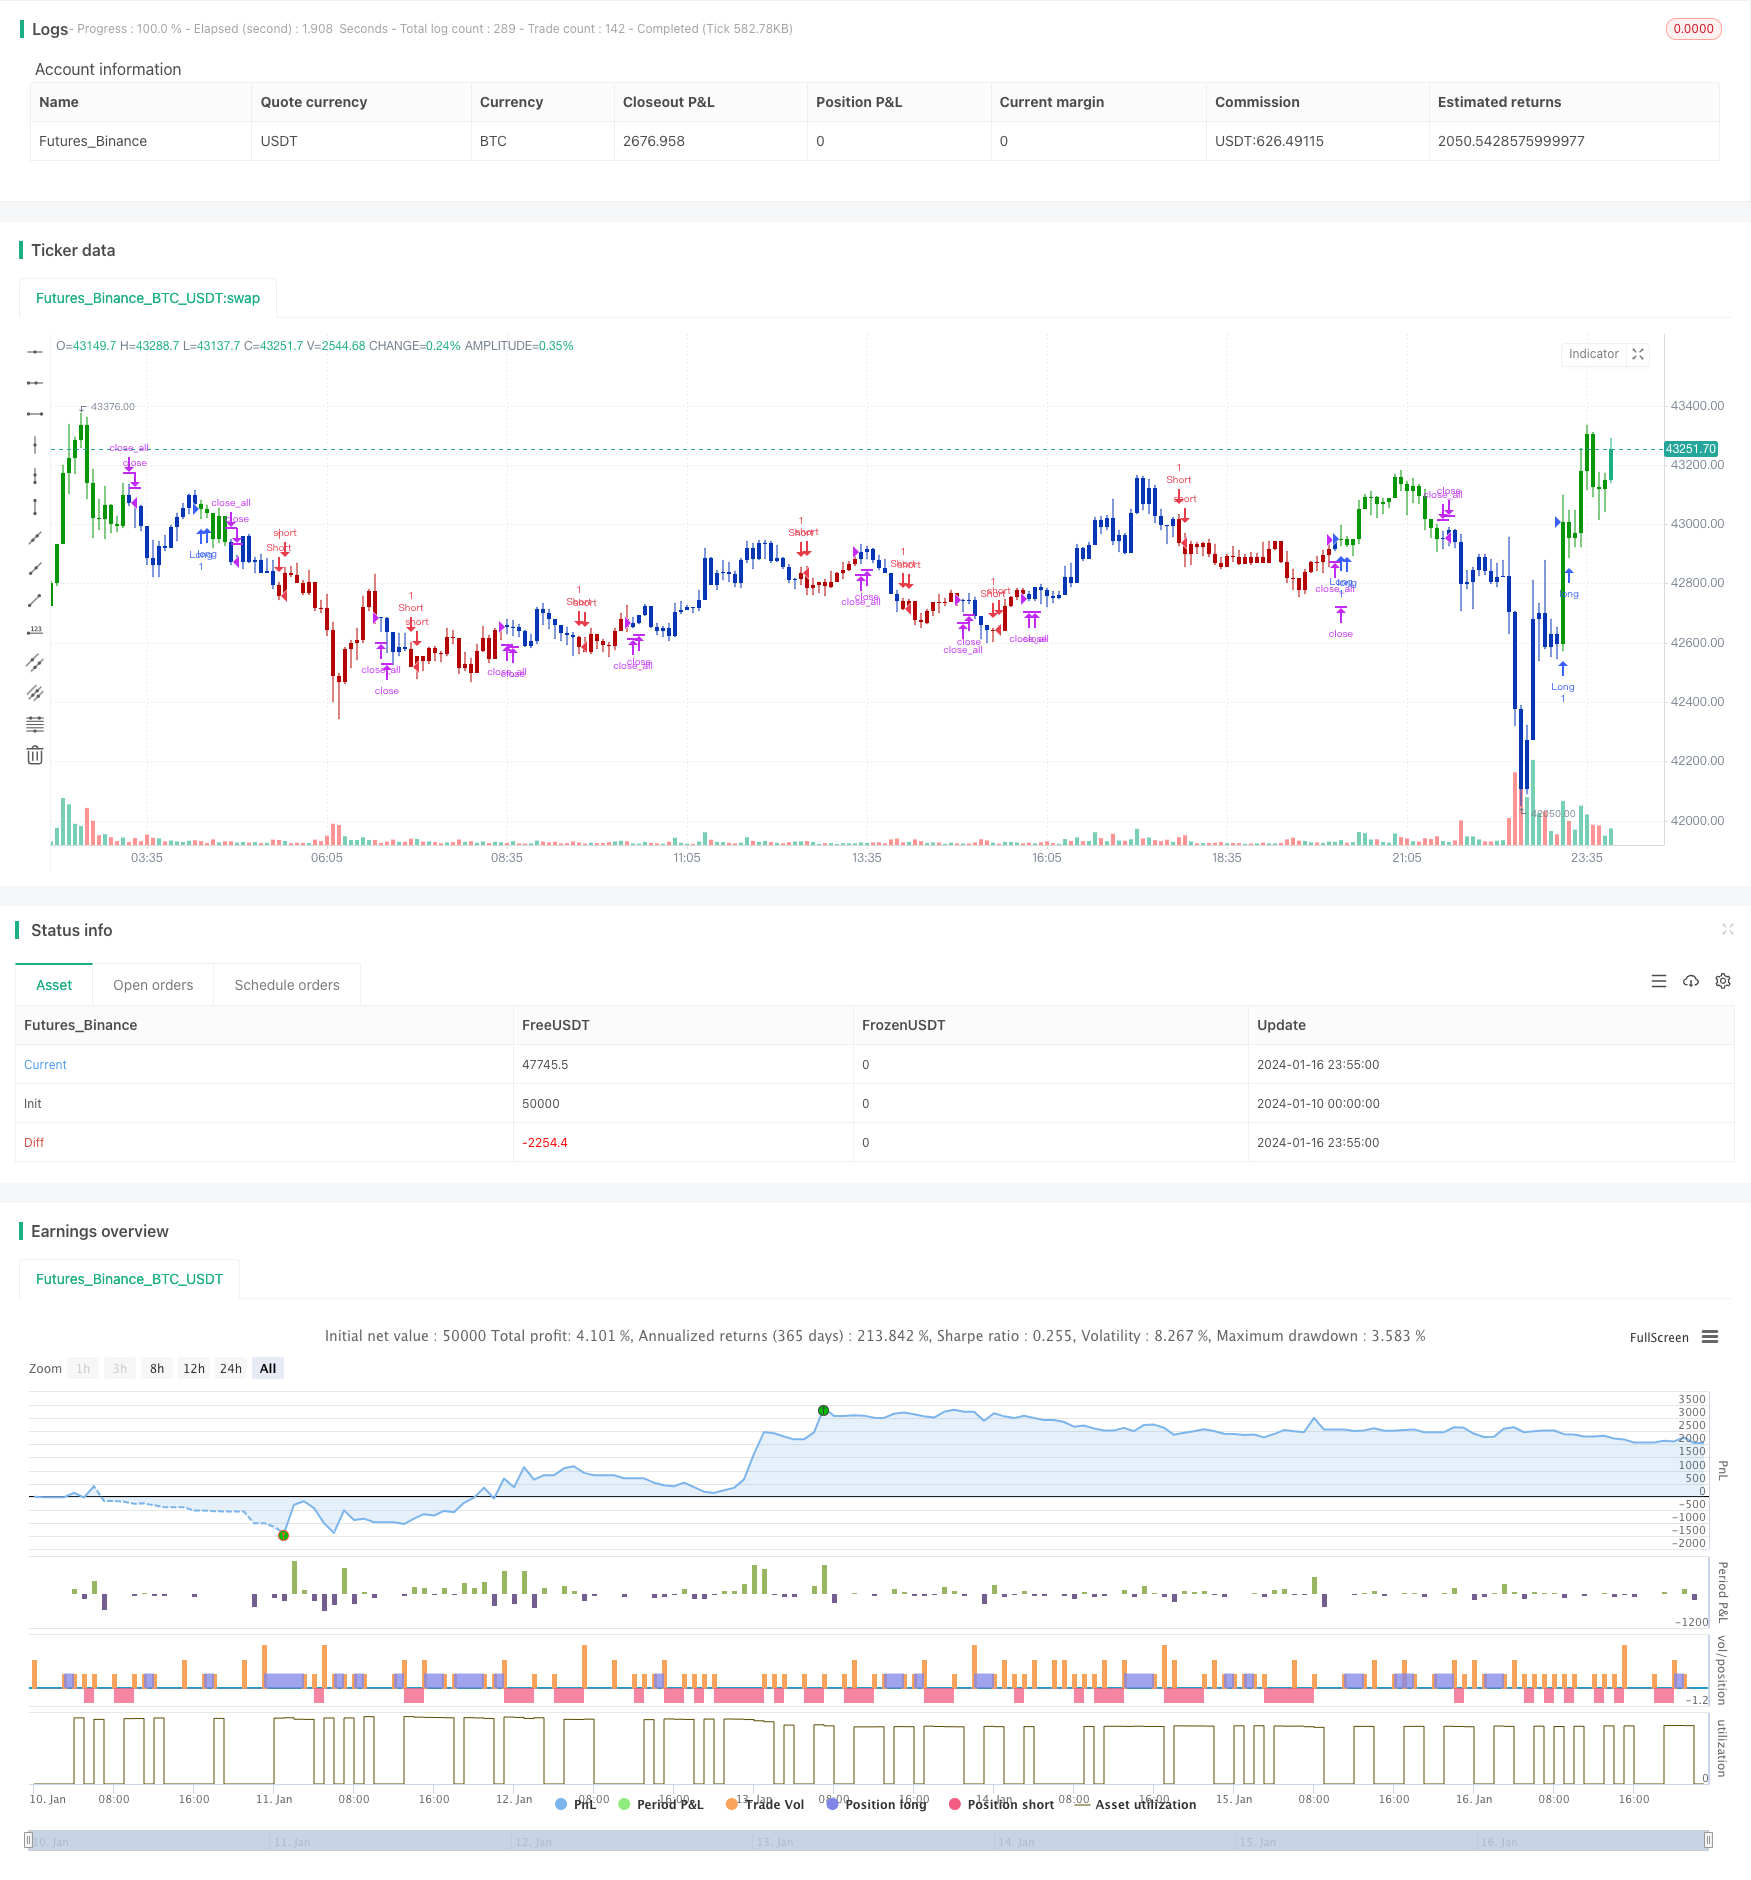
Overview
This strategy combines the price reversal factor and momentum factor of stocks to construct a dual-factor model for capturing opportunities arising from short-term reversals and long-term persistence in the market. It first uses 123 chart patterns to determine near-term price reversal signals, then incorporates the Laguerre RSI indicator to judge the medium-to-long term trend, and eventually achieves effective integration of dual-factor signals.
Strategy Principles
The strategy consists of two parts:
123 Reversal Pattern Factor
This part detects short-term price reversal signals by examining the change in closing prices over the past two days. Specifically, if yesterday's closing price is lower than the previous two days' and today's closing price is higher than yesterday's, it can be determined as a bullish price reversal signal. The Stoch indicator serves as an auxiliary means to assist judgement.
Laguerre Filtered RSI Factor
This part builds a more responsive RSI indicator using Laguerre filters. The sensitivity of traditional RSI indicators to price changes is relatively low. By contrast, Laguerre filters can construct indicators using less historical data, thereby improving sensitivity to price fluctuations. The new RSI indicator is used to determine the medium-to-long term trend.
Ultimately, the strategy combines the signals from both factors, ensuring short-term reversals occur in alignment with overall market trends, in order to capitalize on retracement opportunities.
Advantages of the Strategy
The biggest advantage of this strategy lies in the successful combination of reversal and trend factors. The reversal factor captures short-term pullback opportunities after price consolidations, while the trend factor ensures the overall long/short bias does not change. Compared to standalone reversal or momentum models, this dual-factor model can improve the accuracy of long/short signals while lowering false signals.
Additionally, the introduction of the Laguerre RSI boosts the model's sensitivity to price changes, which is especially crucial for high-frequency trading.
Risk Analysis
The primary risk this strategy faces is the possibility of conflicting signals from the two factors. Particularly during volatile market corrections, short-term prices may reverse frequently while medium-to-long term trends also begin to shift. In such cases, the two types of signals can easily mismatch or experience delays. This leads to incorrect strategy signals and missed entry opportunities or unnecessary losses.
In addition, poor parameter configurations may also lead to poor strategy performance. The parameters for the technical indicators belonging to the reversal and trend factors need to be separately optimized and tested. Improper parameter combinations can significantly diminish the strategy's efficacy.
Optimization Directions
The main focuses of future optimizations for this strategy involve signal filtering and parameter selection. More filtering conditions could be introduced to take effect when the dual-factor signals conflict, ensuring trades are only placed in high-certainty scenarios. This can drastically reduce false signals.
For parameter selection, machine learning and scientific experiment methods could be attempted to systematically test various parameter combinations and arrive at optimal configurations. This requires considerable computing power but can significantly improve the stability of the strategy.
Summary
This strategy has successfully merged reversal and trend factors through a dual-factor model to capitalize on short-term pullbacks and medium-to-long term persistence. The introduction of the Laguerre filtered RSI also improves model sensitivity to price changes. The next phase shall focus on signal filtering and parameter optimization to further enhance the strategy.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 14 | Length |
| v_input_2 | true | KSmoothing |
| v_input_3 | 3 | DLength |
| v_input_4 | 50 | Level |
| v_input_5 | 0.5 | gamma |
| v_input_6 | 0.8 | BuyBand |
| v_input_7 | 0.2 | SellBand |
| v_input_8 | false | Trade reverse |
Source Pine Script
/*backtest
start: 2024-01-10 00:00:00
end: 2024-01-17 00:00:00
period: 5m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
////////////////////////////////////////////////////////////
//  Copyright by HPotter v1.0 21/01/2021
// This is combo strategies for get a cumulative signal.
//
// First strategy
// This System was created from the Book "How I Tripled My Money In The
// Futures Market" by Ulf Jensen, Page 183. This is reverse type of strategies.
// The strategy buys at market, if close price is higher than the previous close
// during 2 days and the meaning of 9-days Stochastic Slow Oscillator is lower than 50.
// The strategy sells at market, if close price is lower than the previous close price
// during 2 days and the meaning of 9-days Stochastic Fast Oscillator is higher than 50.
//
// Second strategy
// This is RSI indicator which is more sesitive to price changes.
// It is based upon a modern math tool - Laguerre transform filter.
// With help of Laguerre filter one becomes able to create superior
// indicators using very short data lengths as well. The use of shorter
// data lengths means you can make the indicators more responsive to
// changes in the price.
//
// WARNING:
// - For purpose educate only
// - This script to change bars colors.
////////////////////////////////////////////////////////////
Reversal123(Length, KSmoothing, DLength, Level) =>
    vFast = sma(stoch(close, high, low, Length), KSmoothing)
    vSlow = sma(vFast, DLength)
    pos = 0.0
    pos := iff(close[2] < close[1] and close > close[1] and vFast < vSlow and vFast > Level, 1,
	         iff(close[2] > close[1] and close < close[1] and vFast > vSlow and vFast < Level, -1, nz(pos[1], 0)))
	pos

LB_RSI(gamma,BuyBand,SellBand) =>
    pos = 0.0
    xL0 = 0.0
    xL1 = 0.0
    xL2 = 0.0
    xL3 = 0.0
    xL0 := (1-gamma) * close + gamma * nz(xL0[1], 1)
    xL1 := - gamma * xL0 + nz(xL0[1], 1) + gamma * nz(xL1[1], 1)
    xL2 := - gamma * xL1 + nz(xL1[1], 1) + gamma * nz(xL2[1], 1)
    xL3 := - gamma * xL2 + nz(xL2[1], 1) + gamma * nz(xL3[1], 1)
    CU = (xL0 >= xL1 ? xL0 - xL1 : 0) + (xL1 >= xL2 ? xL1 - xL2 : 0)  + (xL2 >= xL3 ? xL2 - xL3 : 0)
    CD = (xL0 >= xL1 ? 0 : xL1 - xL0) + (xL1 >= xL2 ? 0 : xL2 - xL1)  + (xL2 >= xL3 ? 0 : xL3 - xL2)
    nRes = iff(CU + CD != 0, CU / (CU + CD), 0)
    pos := iff(nRes > BuyBand, 1,
    	     iff(nRes < SellBand, -1, nz(pos[1], 0)))
    pos

strategy(title="Combo Backtest 123 Reversal & Laguerre-based RSI", shorttitle="Combo", overlay = true)
Length = input(14, minval=1)
KSmoothing = input(1, minval=1)
DLength = input(3, minval=1)
Level = input(50, minval=1)
//-------------------------
gamma = input(0.5, minval=-0.1, maxval = 0.9)
BuyBand = input(0.8, step = 0.01)
SellBand = input(0.2, step = 0.01)
reverse = input(false, title="Trade reverse")
posReversal123 = Reversal123(Length, KSmoothing, DLength, Level)
posLB_RSI = LB_RSI(gamma,BuyBand,SellBand)
pos = iff(posReversal123 == 1 and posLB_RSI == 1 , 1,
	   iff(posReversal123 == -1 and posLB_RSI == -1, -1, 0))
possig = iff(reverse and pos == 1, -1,
          iff(reverse and pos == -1 , 1, pos))
if (possig == 1)
    strategy.entry("Long", strategy.long)
if (possig == -1)
    strategy.entry("Short", strategy.short)
if (possig == 0)
    strategy.close_all()
barcolor(possig == -1 ? #b50404: possig == 1 ? #079605 : #0536b3 )Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-18. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-Factor-Momentum-Tracking-Reversal-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- Bollinger Bands Stochastic RSI Extreme Strategy BBSR Extreme StrategyPine Script · Mean reversion · 1h
- BuySell Strategy depends on AOStochRSIATRPine Script · Mean reversion · 30m
- Byron Serpent Cloud Quant StrategyPine Script · Mean reversion · 1h
- Dual Momentum Trend Reversal Strategy Based on RSI and Stochastic RSIPine Script · Mean reversion · 1h
- Dynamic Adaptive Multi Timeframe Trend Following and Range Reversal Hybrid StrategyPine Script · Mean reversion · 2d