Strategy vault / Mean reversion
Dual factor Quantitative Reversal Tracking Strategy
This strategy combines the 123 reversal pattern and the Awesome Oscillator indicator to implement dual-factor quantitative reversal tracking trading. The basic idea is to determine market reversal while combining the…
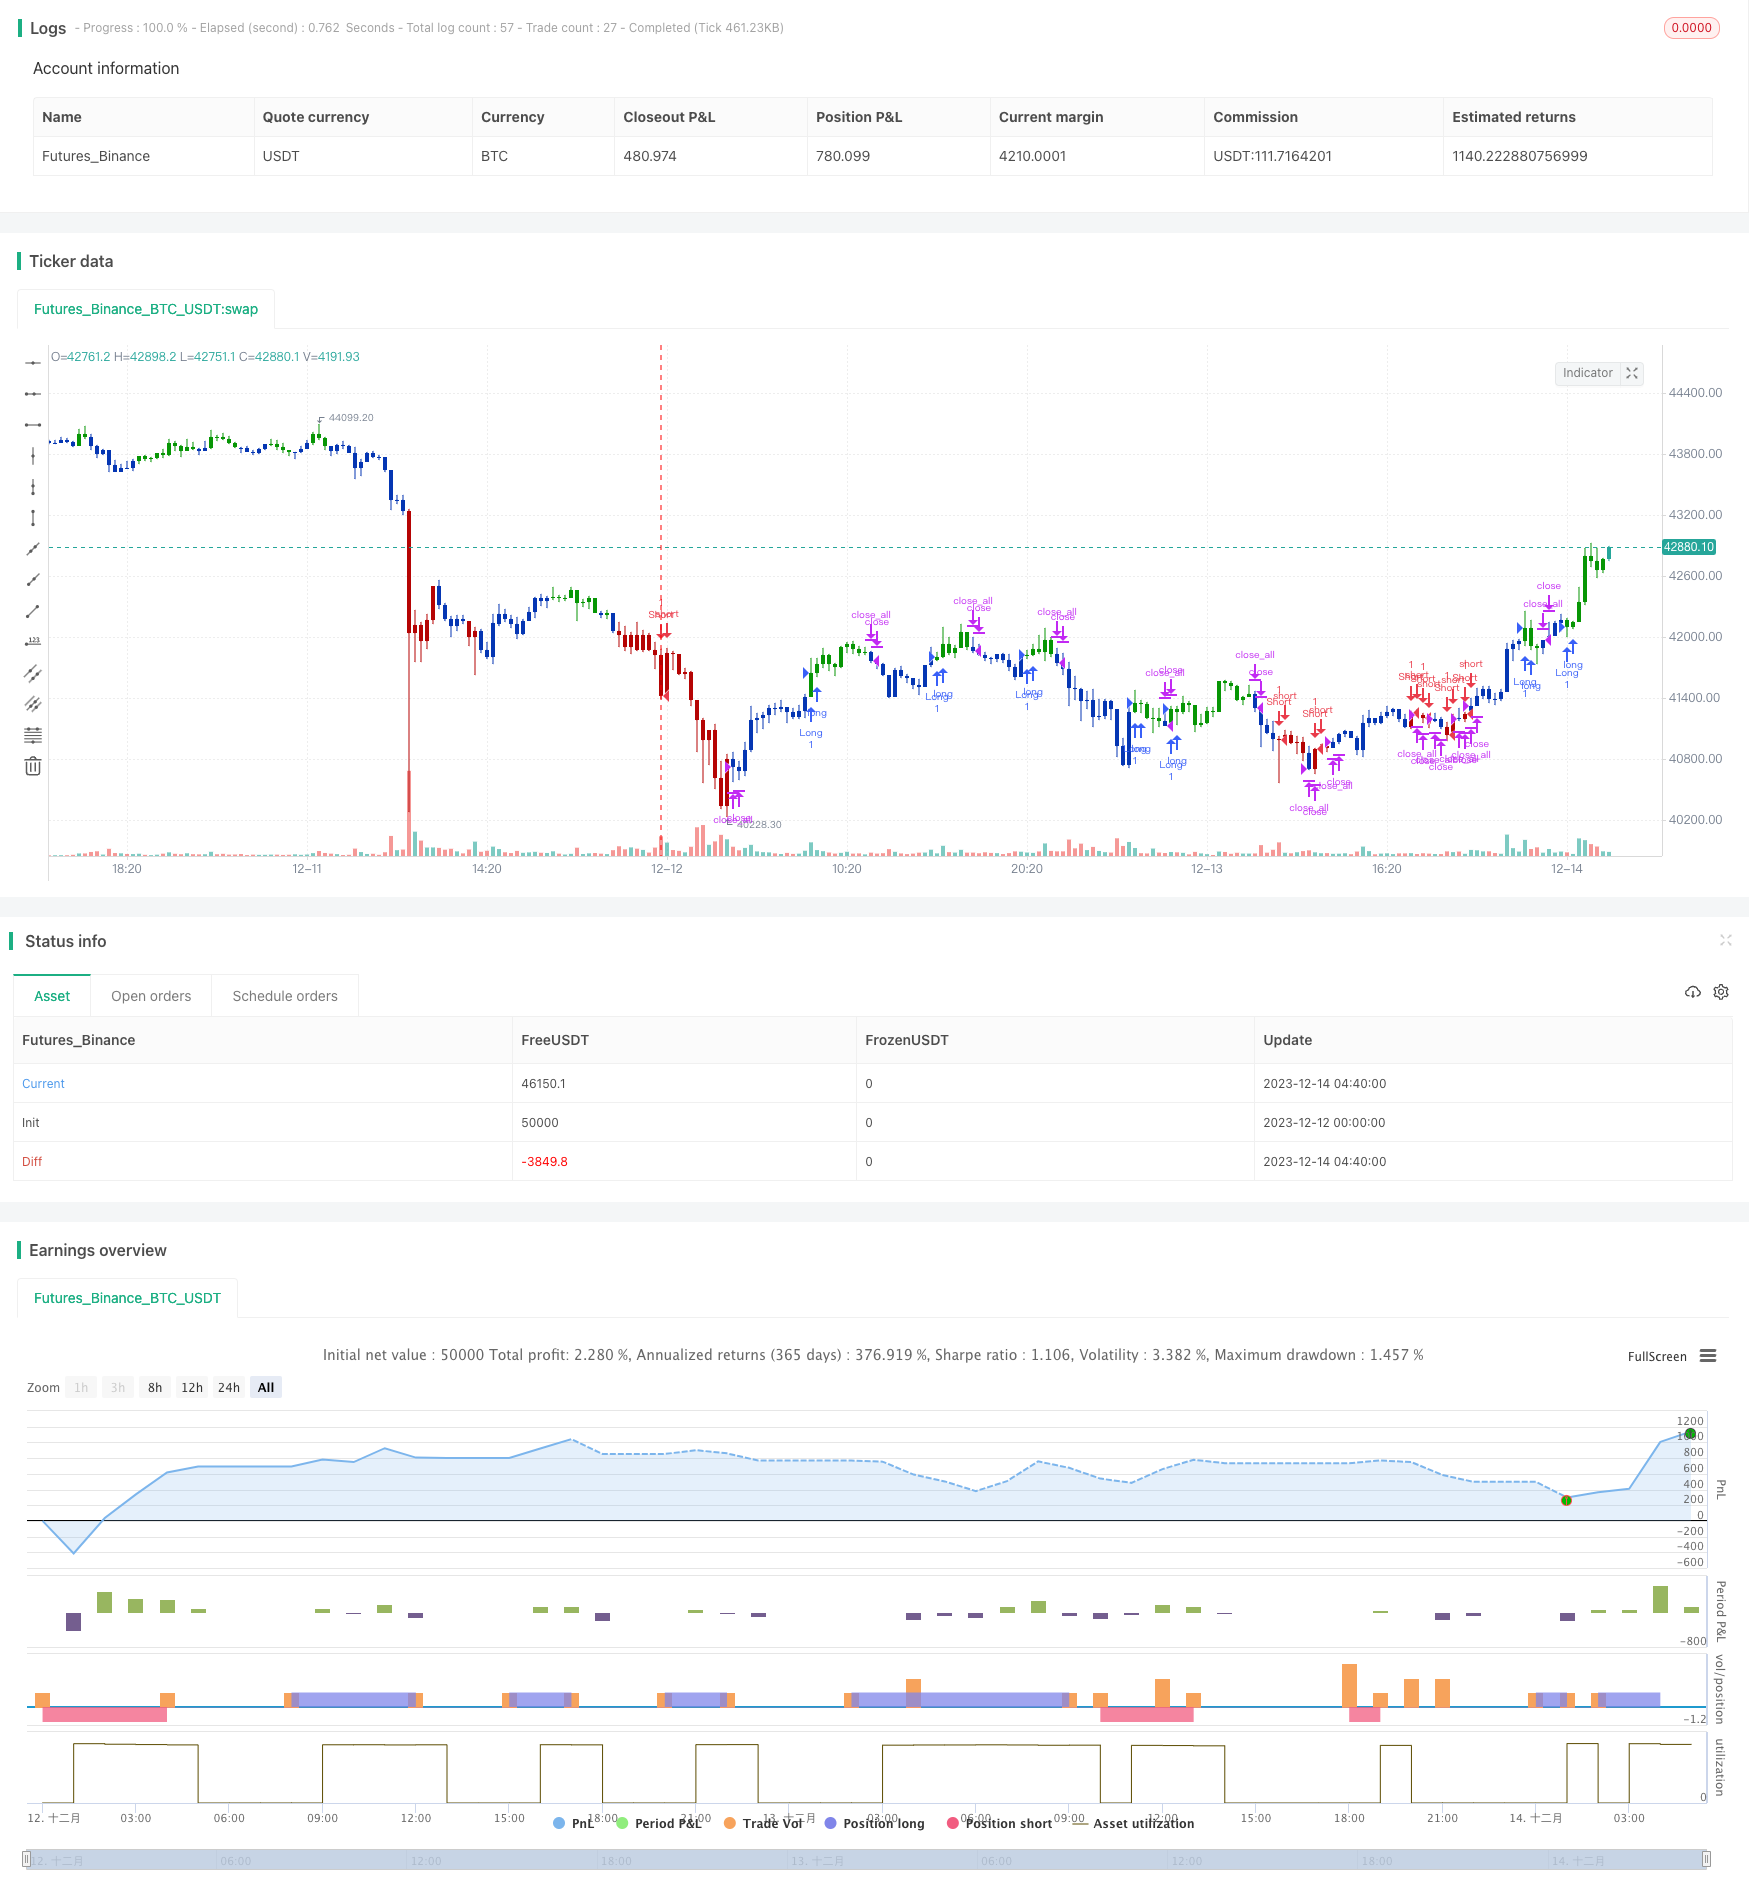
Overview
This strategy combines the 123 reversal pattern and the Awesome Oscillator indicator to implement dual-factor quantitative reversal tracking trading. The basic idea is to determine market reversal while combining the signal from the Awesome Oscillator to achieve more accurate entry timing.
The strategy is mainly suitable for medium-short term reversal trading. By multi-factor confirmation, it can effectively filter out false reversals and improve signal quality.
Strategy Principle
123 Reversal Pattern
Judge the relationship between the closing prices of the previous two days and the current closing price to form a "high-high-low" or "low-low-high" pattern, indicating a possible reversal signal.
At the same time, require the Stochastic indicator to be in the overbought or oversold area to further confirm the reversal signal and filter out false reversals.
Awesome Oscillator
The Awesome Oscillator is a momentum indicator built based on the difference between medium-term moving average and short-term moving average. When the fast line crosses the slow line downward, it is a sell signal; when it crosses upward, it is a buy signal.
This strategy adopts the indicator's judgment of bullish or bearish state to determine buy and sell points.
Dual-factor Confirmation
Through the dual confirmation of the 123 reversal pattern and Awesome Oscillator, false reversals can be effectively filtered out and the accuracy of entry timing can be improved.
Advantages of the Strategy
Using dual factors to determine reversal points can effectively filter out false reversal signals.
As a momentum indicator, the Awesome Oscillator can improve the accuracy of entry timing.
The addition of the Stochastic indicator can avoid the risk of buying at the peak and selling at the bottom.
Reversal strategies themselves have advantages in higher winning rate and risk-reward ratio.
Risks of the Strategy
The risk of reversal failure still exists. Using dual factors can reduce the probability, but cannot completely avoid this risk.
Over-optimization risk. Indicator parameters need to be tested and optimized for different markets to prevent over-optimization.
Risk of trading against the market trend. In a strong trending market, reversal strategies are prone to contrarian losses. Stop loss can be set to control risks.
Optimization Directions
Test and optimize combinations of indicator parameters to improve robustness.
Add stop loss strategy to control single loss.
Combine industry and sector selections to avoid inappropriate stock picking.
Optimize holding period to prevent blind trend following.
Test different moving average systems as auxiliary conditions.
Conclusion
In summary, while ensuring a certain profit probability and risk-reward ratio, this dual-factor quantitative reversal tracking strategy uses Awesome Oscillator as an entry timing tool, and avoids buying at the peak through the Stochastic indicator, which can effectively control the risks of reversal trading and has strong practicality.
However, the inherent risks of reversal strategies cannot be ignored. It is still necessary to optimize indicator parameters, set stop loss conditions, etc. to control risks. If used properly, this strategy can bring investors stable excess returns.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | ---- 123 Reversal ---- |
| v_input_2 | 14 | Length |
| v_input_3 | true | KSmoothing |
| v_input_4 | 3 | DLength |
| v_input_5 | 50 | Level |
| v_input_6 | true | ---- Awesome Oscillator (AO) ---- |
| v_input_7 | 34 | Length Slow |
| v_input_8 | 5 | Length Fast |
| v_input_9 | false | Trade reverse |
Source Pine Script
/*backtest
start: 2023-12-12 00:00:00
end: 2023-12-14 05:00:00
period: 20m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
////////////////////////////////////////////////////////////
//  Copyright by HPotter v1.0 12/08/2021
// This is combo strategies for get a cumulative signal.
//
// First strategy
// This System was created from the Book "How I Tripled My Money In The
// Futures Market" by Ulf Jensen, Page 183. This is reverse type of strategies.
// The strategy buys at market, if close price is higher than the previous close
// during 2 days and the meaning of 9-days Stochastic Slow Oscillator is lower than 50.
// The strategy sells at market, if close price is lower than the previous close price
// during 2 days and the meaning of 9-days Stochastic Fast Oscillator is higher than 50.
//
// Second strategy
//    This indicator is based on Bill Williams` recommendations from his book
//    "New Trading Dimensions". We recommend this book to you as most useful reading.
//    The wisdom, technical expertise, and skillful teaching style of Williams make
//    it a truly revolutionary-level source. A must-have new book for stock and
//    commodity traders.
//    The 1st 2 chapters are somewhat of ramble where the author describes the
//    "metaphysics" of trading. Still some good ideas are offered. The book references
//    chaos theory, and leaves it up to the reader to believe whether "supercomputers"
//    were used in formulating the various trading methods (the author wants to come across
//    as an applied mathemetician, but he sure looks like a stock trader). There isn't any
//    obvious connection with Chaos Theory - despite of the weak link between the title and
//    content, the trading methodologies do work. Most readers think the author's systems to
//    be a perfect filter and trigger for a short term trading system. He states a goal of
//    10%/month, but when these filters & axioms are correctly combined with a good momentum
//    system, much more is a probable result.
//    There's better written & more informative books out there for less money, but this author
//    does have the "Holy Grail" of stock trading. A set of filters, axioms, and methods which are
//    the "missing link" for any trading system which is based upon conventional indicators.
//    This indicator plots the oscillator as a histogram where periods fit for buying are marked
//    as blue, and periods fit for selling as red. If the current value of AC (Awesome Oscillator)
//    is over the previous, the period is deemed fit for buying and the indicator is marked blue.
//    If the AC values is not over the previous, the period is deemed fir for selling and the indicator
//    is marked red.
//
// WARNING:
// - For purpose educate only
// - This script to change bars colors.
////////////////////////////////////////////////////////////
Reversal123(Length, KSmoothing, DLength, Level) =>
    vFast = sma(stoch(close, high, low, Length), KSmoothing)
    vSlow = sma(vFast, DLength)
    pos = 0.0
    pos := iff(close[2] < close[1] and close > close[1] and vFast < vSlow and vFast > Level, 1,
	         iff(close[2] > close[1] and close < close[1] and vFast > vSlow and vFast < Level, -1, nz(pos[1], 0)))
	pos


BWAO(nLengthSlow,nLengthFast) =>
    pos = 0.0
    xSMA1_hl2 = sma(hl2, nLengthFast)
    xSMA2_hl2 = sma(hl2, nLengthSlow)
    xSMA1_SMA2 = xSMA1_hl2 - xSMA2_hl2
    pos := iff(xSMA1_SMA2 > xSMA1_SMA2[1], 1,
    	      iff(xSMA1_SMA2 < xSMA1_SMA2[1], -1, nz(pos[1], 0)))
    pos

strategy(title="Combo Backtest 123 Reversal & Awesome Oscillator (AO)", shorttitle="Combo", overlay = true)
line1 = input(true, "---- 123 Reversal ----")
Length = input(14, minval=1)
KSmoothing = input(1, minval=1)
DLength = input(3, minval=1)
Level = input(50, minval=1)
//-------------------------
line2 = input(true, "---- Awesome Oscillator (AO) ----")
nLengthSlow = input(34, minval=1, title="Length Slow")
nLengthFast = input(5, minval=1, title="Length Fast")
reverse = input(false, title="Trade reverse")
posReversal123 = Reversal123(Length, KSmoothing, DLength, Level)
posBWAO = BWAO(nLengthSlow,nLengthFast)
pos = iff(posReversal123 == 1 and posBWAO == 1 , 1,
	   iff(posReversal123 == -1 and posBWAO == -1, -1, 0))
possig = iff(reverse and pos == 1, -1,
          iff(reverse and pos == -1 , 1, pos))
if (possig == 1 )
    strategy.entry("Long", strategy.long)
if (possig == -1 )
    strategy.entry("Short", strategy.short)
if (possig == 0)
    strategy.close_all()
barcolor(possig == -1 ? #b50404: possig == 1 ? #079605 : #0536b3 )Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-20. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-factor-Quantitative-Reversal-Tracking-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive Trading Strategy Combining Dynamic Trend Reversal and Stochastic IndicatorPine Script · Mean reversion · 1d
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- Bollinger Bands Stochastic RSI Extreme Strategy BBSR Extreme StrategyPine Script · Mean reversion · 1h
- BuySell Strategy depends on AOStochRSIATRPine Script · Mean reversion · 30m
- Byron Serpent Cloud Quant StrategyPine Script · Mean reversion · 1h
- Dual Momentum Trend Reversal Strategy Based on RSI and Stochastic RSIPine Script · Mean reversion · 1h