Strategy vault / Trend following
Dual Moving Average Crossover Strategy 432760
The Dual Moving Average Crossover Strategy is a typical trend following strategy. It calculates two moving averages with different periods and uses their crossover as trading signals to capture the direction and…
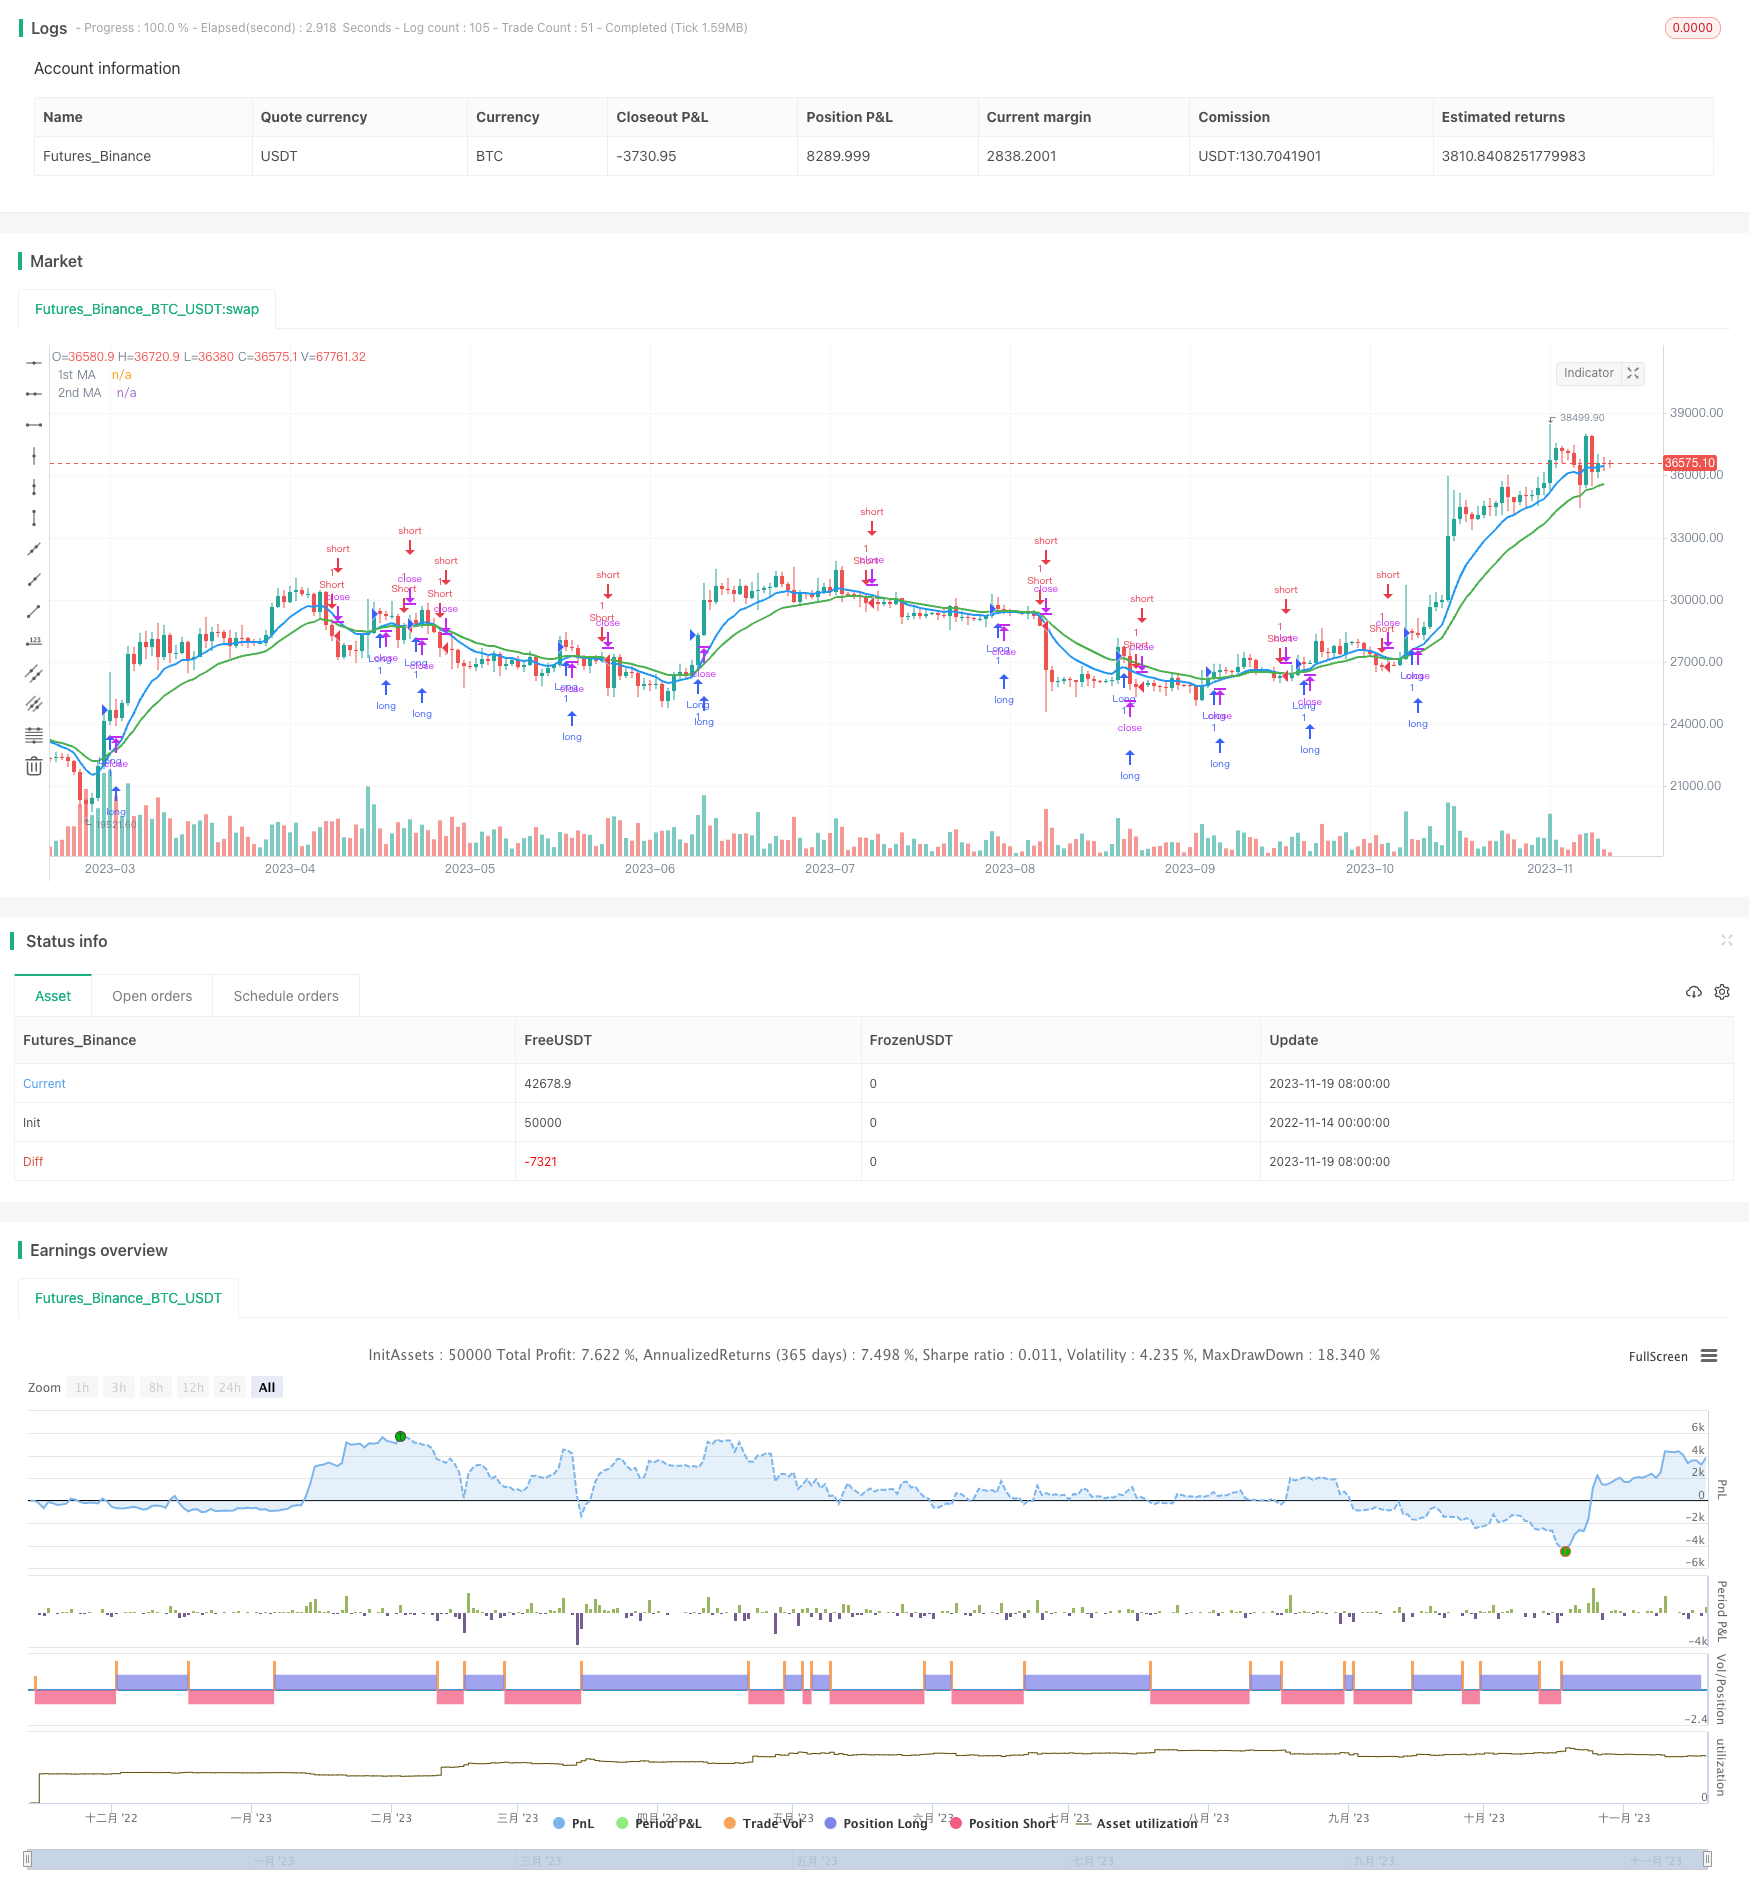
Overview
The Dual Moving Average Crossover Strategy is a typical trend following strategy. It calculates two moving averages with different periods and uses their crossover as trading signals to capture the direction and momentum of market trends.
Strategy Logic
The strategy is mainly based on two moving averages. The first moving average has a shorter period and can respond to price changes faster. The second moving average has a longer period and can filter out some noise. When the short term moving average crosses over the long term moving average, it is considered a buy signal. When the short term moving average crosses below the long term moving average, it is considered a sell signal.
Specifically, this strategy calculates a 10-period exponential moving average (price1) and a 20-period exponential moving average (price2). If the open and close prices of the current bar are both higher than the two moving averages, a buy signal is generated. If the open and close prices are both lower than the two moving averages, a sell signal is generated.
This design allows earlier entry when a trend starts to form and follows the trend. When the trend reverses, it can also exit the market early to effectively control risks.
Advantages
- Catch trends early and follow strong trends
- Dual MA crossover filters noise
- Double confirmation from open and close prices reduces ineffective trades
Risks
- Prone to whipsaws and reverse trades
- Frequent crossover signals may occur
- Large parameter tuning space may lead to overfitting
Enhancement
- Test different parameter sets to find optimum
- Add stop loss to limit loss size
- Add filters to reduce bad trades
- Combine other indicators to confirm signals
Summary
The strategy is relatively simple and practical, capturing trends with dual MA crossover, making it a fundamental quant strategy. But it also has some risks and needs further optimization for different market regimes. There is room for enhancing parameters, stops, filters etc. to make it more robust.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_2 | 10 | 1st MA Length |
| v_input_3 | 0 | 1st MA Type: EMA | SMA |
| v_input_4 | 20 | 2nd MA Length |
| v_input_5 | 0 | 2nd MA Type: EMA | SMA |
Source Pine Script
/*backtest
start: 2022-11-14 00:00:00
end: 2023-11-20 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=3
//study(title="MA River CC v1", overlay = true)
strategy("MA River CC v1", overlay=true)
src = input(close, title="Source")

price = request.security(syminfo.tickerid, timeframe.period, src)
ma1 = input(10, title="1st MA Length")
type1 = input("EMA", "1st MA Type", options=["SMA", "EMA"])

ma2 = input(20, title="2nd MA Length")
type2 = input("EMA", "2nd MA Type", options=["SMA", "EMA"])

price1 = if (type1 == "SMA")
    sma(price, ma1)
else
    ema(price, ma1)

price2 = if (type2 == "SMA")
    sma(price, ma2)
else
    ema(price, ma2)


//plot(series=price, style=line,  title="Price", color=black, linewidth=1, transp=0)
plot(series=price1, style=line,  title="1st MA", color=blue, linewidth=2, transp=0)
plot(series=price2, style=line, title="2nd MA", color=green, linewidth=2, transp=0)


buy_entry = (open>price1 and open>price2) and (close>price1 and close>price2)
sell_entry = (open<price1 and open<price2) and (close<price1 and close<price2)
buy_close = sell_entry
sell_close = buy_entry
//longCondition = crossover(price1, price2)
if(buy_entry)
    strategy.entry("Long", strategy.long)

if(sell_entry)
    strategy.entry("Short", strategy.short)

strategy.close("Long" , when=buy_close)
strategy.close("Short",when=sell_close)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-21. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-Moving-Average-Crossover-Strategy-432760.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- Bollinger Band Moving Average Crossover StrategyPine Script · Trend following · 1h
- Bollinger Bands and EMA Trend Following StrategyPine Script · Trend following · 1h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Candlestick Pattern Trend Filter StrategyPine Script · Trend following · 1d