Strategy vault / Trend following
Dual Moving Average Golden Cross Quantitative Strategy
This strategy judges price trends and trading opportunities by calculating dual moving average crossovers. When the fast MA crosses above the slow MA, it is considered a golden cross to go long. When the fast MA…
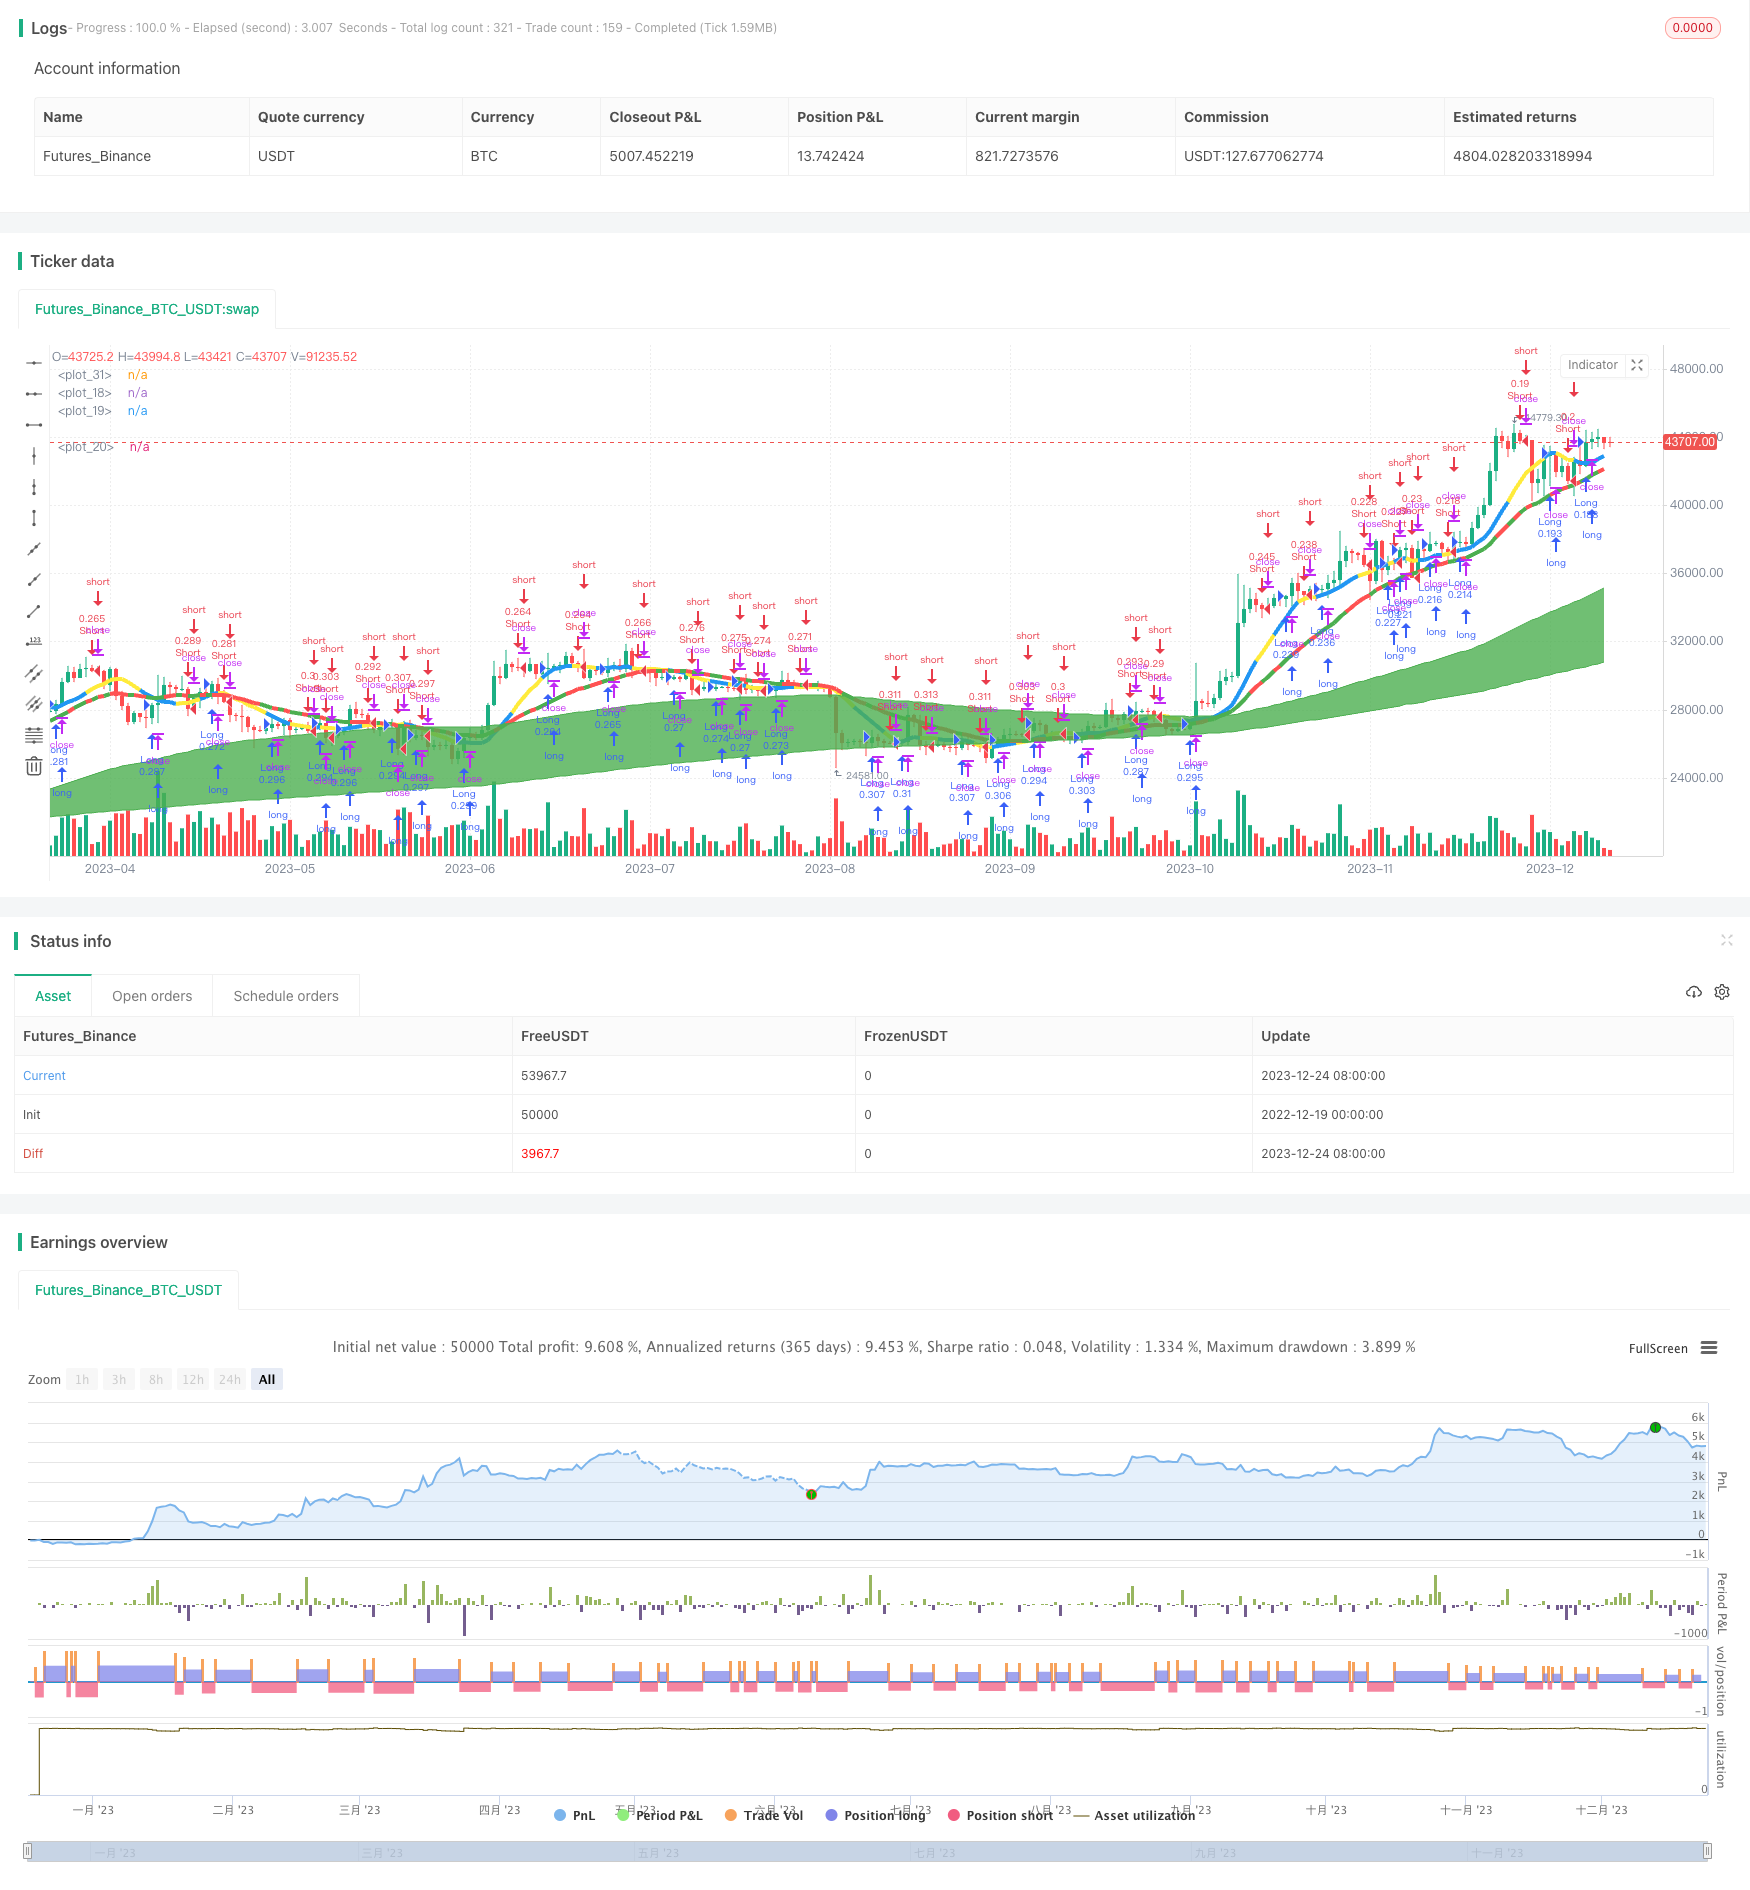
Overview
This strategy judges price trends and trading opportunities by calculating dual moving average crossovers. When the fast MA crosses above the slow MA, it is considered a golden cross to go long. When the fast MA crosses below the slow MA, it is considered a death cross to go short. At the same time, combine the Volume Indicator to judge the reliability of crossovers to avoid false signals.
Strategy Principle
The core principles of this strategy are:
Calculate two groups of moving averages with different parameters, one group responds quickly to price changes and the other reacts relatively slowly. When the fast MA crosses above the slow MA, it signals an upward price trend. When the fast MA crosses below the slow MA, it signals a downward price trend.
When the MAs cross, check the change of the Volume Indicator. If the Volume Indicator also breaks through significantly, the crossover signal is reliable. If there is no corresponding breakout in Volume, it may be a false signal.
Enter long or short positions based on the crossover direction and volume judgment. Set take profit criteria to close positions when reaching a certain profit level.
Specifically, the strategy judges price trends using 7-period dual MAs crossover. It uses Volume indicators to check signal reliability. When getting reliable signals, it goes long or short per the SIGNAL. It sets profit targets to take profits.
Advantage Analysis
The main advantages of this strategy are:
Combining dual MAs to determine trend direction and Volume filter to avoid false signals and being trapped.
Only taking positions when Volume confirms, increasing success rate.
Having profit taking mechanism to take profits in time and avoid giving back profits.
Risk Analysis
The main risks of this strategy are:
MA crossover delay may miss best opportunity. Can optimize parameters to make MAs more sensitive.
Hard to judge when Volume diverges. Can add more indicators for confirmation.
Improper stop profit setting may lead to over trading or holding winners too long. Need to test and optimize stop profit parameters.
Optimization Directions
The strategy can be optimized from the following aspects:
Optimize MA periods to make it more responsive to catch price changes in time.
Add more indicators such as MACD, KD for signal confirmation to avoid Volume false signals.
Incorporate more profit taking mechanics like trail stop, percentage stop, volatility stop for dynamic profit taking.
Add stop loss mechanism to control single trade loss amount.
Optimize position sizing adaptable to different market environments.
Conclusion
In conclusion, the core idea of this strategy is using dual MA crossover for trend and Volume filter for signal reliability. It is stable and easy to implement. Further optimizations on parameters, signal filtering, profit taking and stop loss can make it more reliable and intelligent for practical trading.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 0.001 | Decision Threshold |
| v_input_2 | 7 | Double HullMA Cross |
| v_input_3 | 34 | MA 1 |
| v_input_4 | 144 | MA 2 |
| v_input_5 | 377 | MA 3 |
| v_input_6 | 4200 | TP ($) |
Source Pine Script
/*backtest
start: 2022-12-19 00:00:00
end: 2023-12-25 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=2
strategy("ZendicatoR", overlay=true, calc_on_order_fills= true, calc_on_every_tick=true, default_qty_type=strategy.percent_of_equity, default_qty_value=15, pyramiding=0)
dt = input(defval=0.0010, title="Decision Threshold", type=float, step=0.0001)
keh=input(title="Double HullMA Cross",defval=7, minval=1)
che1=input(title="MA 1",defval=34,minval=1)
che2=input(title="MA 2",defval=144,minval=1)
che3=input(title="MA 3",defval=377,minval=1)
amnt=input(title="TP ($)",defval=4200,minval=1)
wma1=wma(close,che1)
wma2=wma(close,che2)
wma3=wma(close,che3)
sma1=sma(close,11)
tms=10000000000000
A=request.security(syminfo.tickerid, 'D', close)*tms
B=request.security(syminfo.tickerid, 'D', close[1])*tms
C=A>B?green:red
D=wma2>wma3?green:red
plot(wma1,style=line,color=C,linewidth=4)
p1=plot(wma2,style=line,color=D)
p2=plot(wma3,style=line,color=D)
fill(p1, p2, color=D, transp=75)
n2ma=2*wma(close,round(keh/2))
nma=wma(close,keh)
diff=n2ma-nma,sqn=round(sqrt(keh))
n2ma1=2*wma(close[2],round(keh/2))
nma1=wma(close[2],keh)
diff1=n2ma1-nma1,sqn1=round(sqrt(keh))
n1=wma(diff,sqn)*tms
n2=wma(diff1,sqn)*tms
Q=n1>n2?blue:yellow
plot(sma1,style=line,color=Q,linewidth=4)
closelong = A*tms<B*tms and n2*tms>n1*tms and strategy.openprofit>amnt
if (closelong)
    strategy.close("Long")
closeshort = A*tms>B*tms and n1*tms>n2*tms and strategy.openprofit>amnt
if (closeshort)
    strategy.close("Short")
longCondition = A*tms>B*tms and n1*tms>n2*tms
if (longCondition)
    strategy.entry("Long",strategy.long)
shortCondition = A*tms<B*tms and n1*tms<n2*tms
if (shortCondition)
    strategy.entry("Short",strategy.short)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-26. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-Moving-Average-Golden-Cross-Quantitative-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Dual Moving Average Convergence Trend Tracking StrategyPine Script · Trend following · 1d
- Dual SMA Crossover StrategyPine Script · Trend following · 5m
- Fixed Range Volume Profile And Anchored VWAP Trend Identification Strategy With Dynamic Stop LossPine Script · Trend following · 1h
- Multi Period Moving Average Ribbon and MACD Crossover Strategy SystemPine Script · Trend following · 1h
- Relative Volume Trend Following Trading StrategyPine Script · Trend following · 1d
- Trend Following Strategy Based on Moving Average 439858Pine Script · Trend following · 1d