Strategy vault / Trend following
Dual Moving Average RSI Multi Signal Trend Trading Strategy
This strategy is a multi-signal trend following system based on dual moving averages and the Relative Strength Index (RSI). Operating on a 1-hour timeframe, it identifies market trends and trading opportunities…
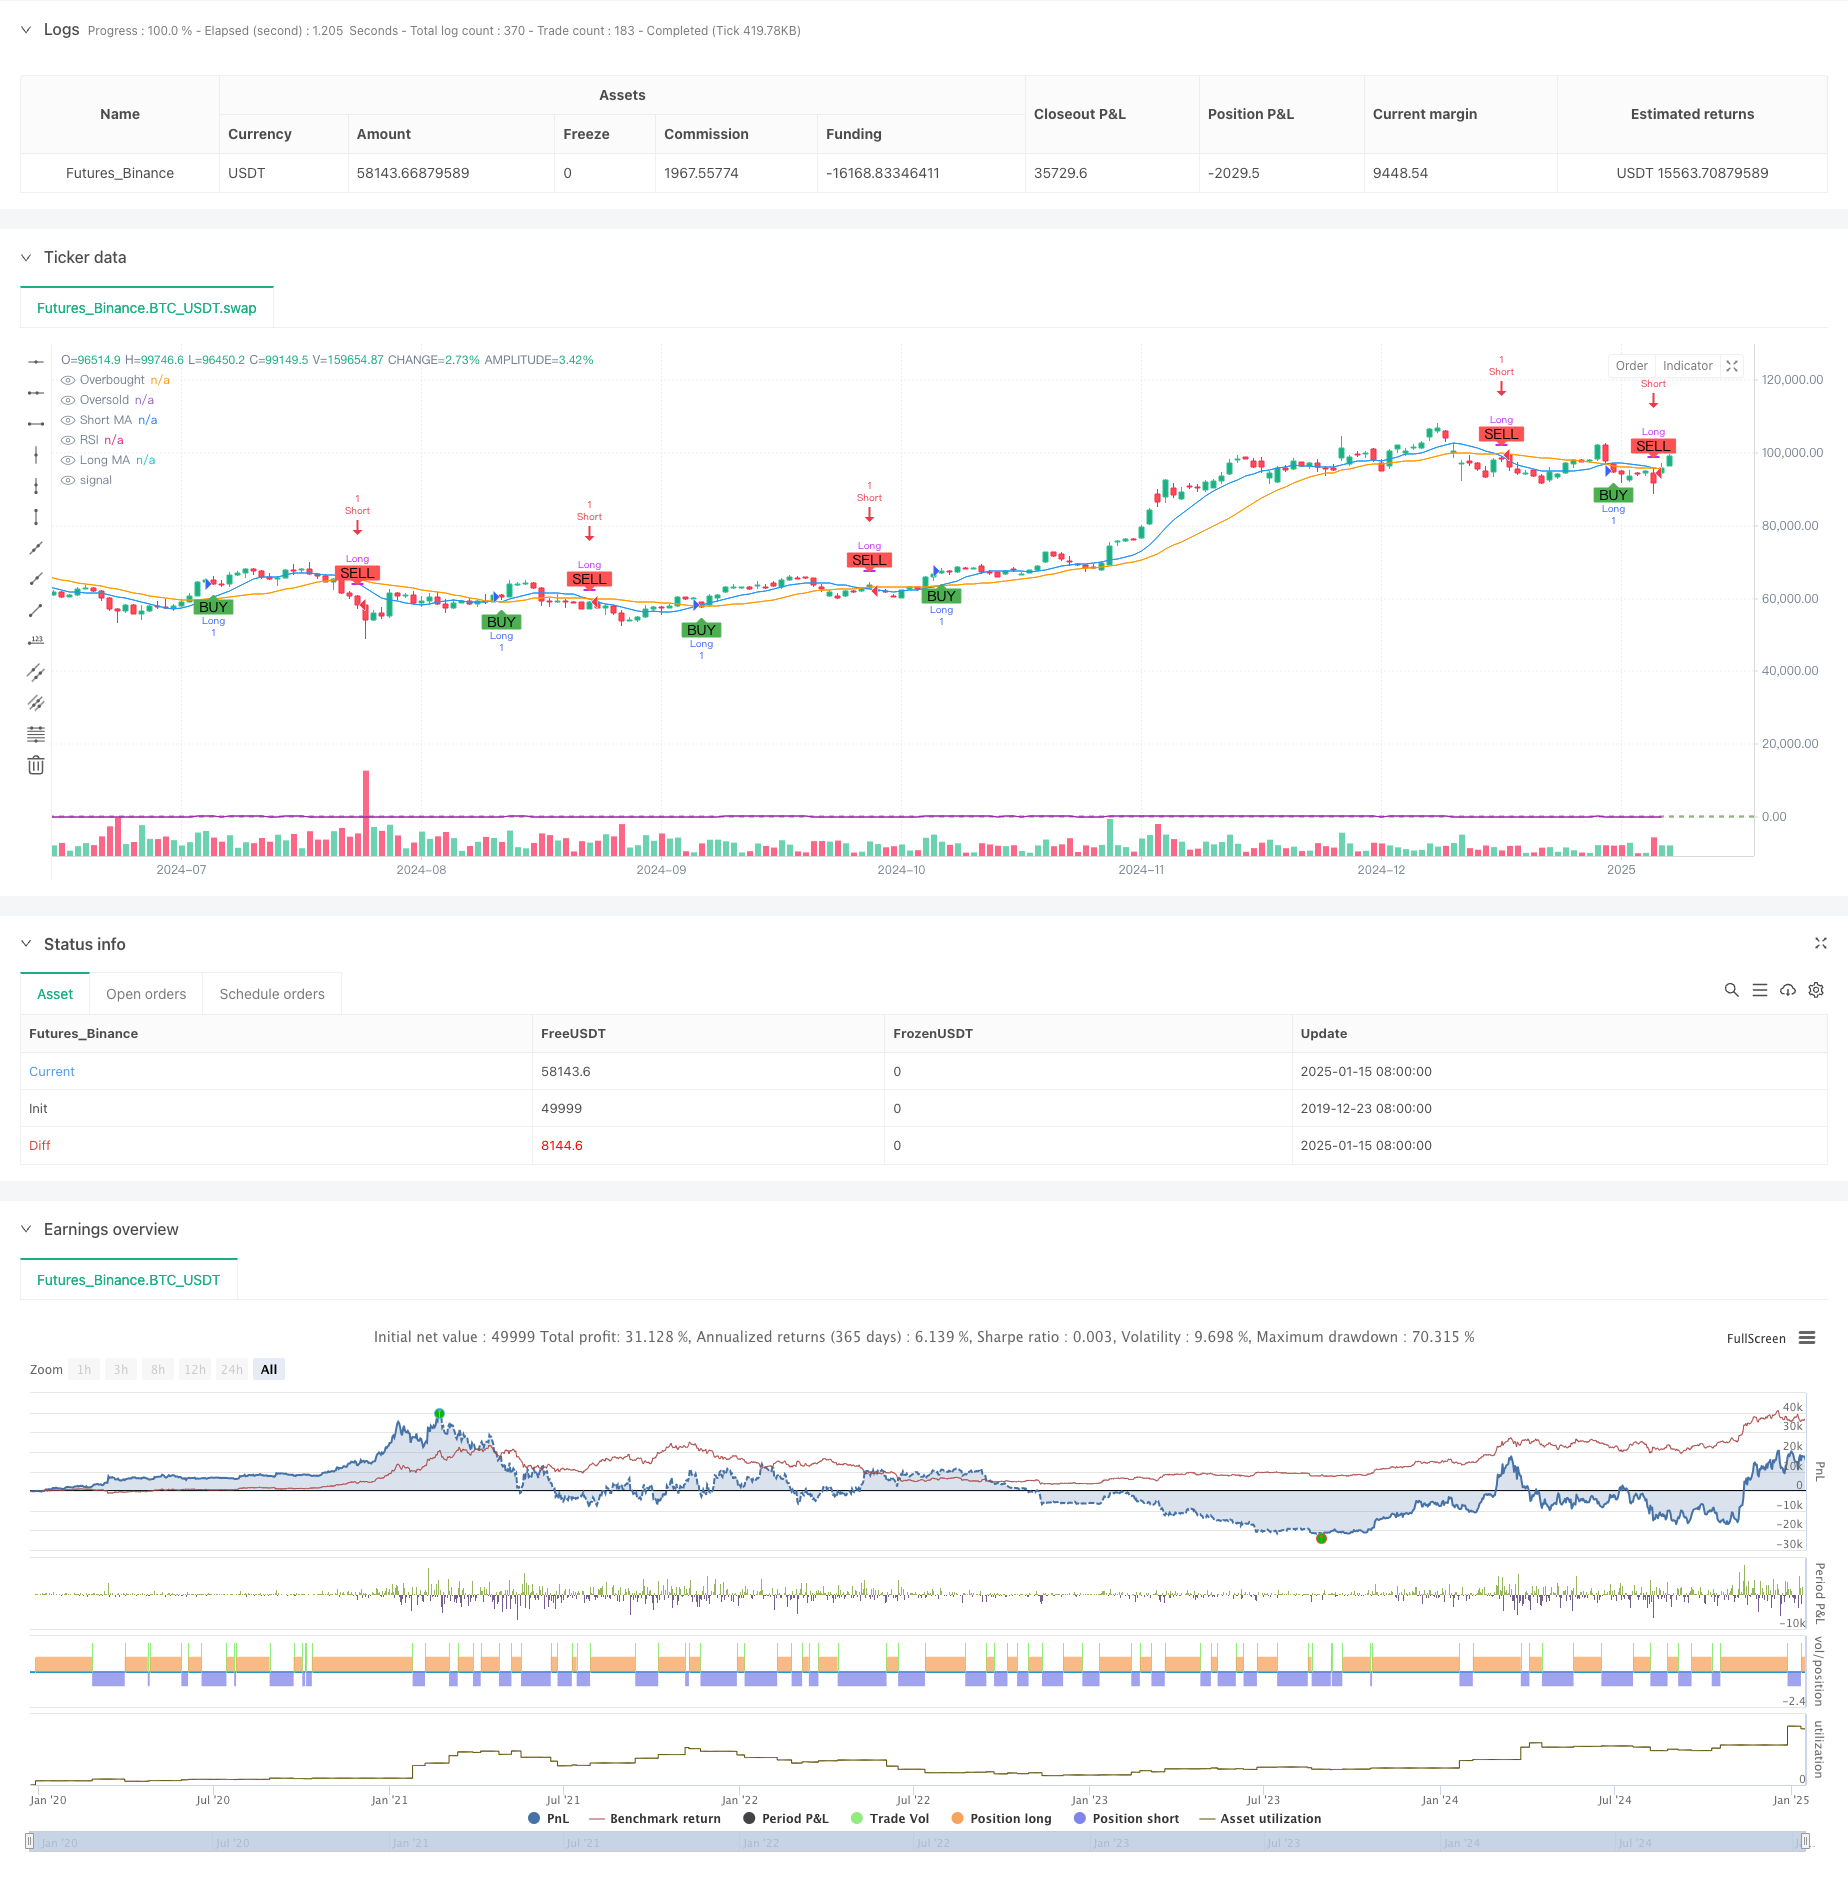
Overview
This strategy is a multi-signal trend following system based on dual moving averages and the Relative Strength Index (RSI). Operating on a 1-hour timeframe, it identifies market trends and trading opportunities through crossovers of short-term and long-term moving averages, combined with RSI overbought and oversold levels. The system employs a combination of 9-period and 21-period Simple Moving Averages (SMA) along with a 14-period RSI to create a comprehensive trend following and momentum confirmation trading system.
Strategy Principle
The core logic of the strategy is based on the following key elements:
- Uses 9-period and 21-period Simple Moving Averages to identify trend direction, with long signals generated when the short MA crosses above the long MA, and short signals when it crosses below.
- Incorporates RSI as a trend confirmation tool, with 70 and 30 set as overbought and oversold thresholds.
- When moving average crossovers occur, the system checks if RSI values meet corresponding conditions: long positions require RSI above oversold level (30), short positions require RSI below overbought level (70).
- Trades are executed only when both moving average crossover and RSI conditions are satisfied simultaneously.
Strategy Advantages
- Multiple signal confirmation mechanism significantly improves trading reliability, avoiding false signals from single indicators.
- Combination of trend and momentum indicators enables both trend capture and avoidance of excessive momentum chasing.
- Reasonable parameter settings, with 9 and 21-period moving average combination effectively balancing sensitivity and stability.
- System automatically displays trading signals on the chart for intuitive judgment.
- Clear code structure, easy to maintain and optimize.
Strategy Risks
- May generate frequent crossover signals in ranging markets, leading to overtrading.
- RSI indicator might miss some opportunities in strong trend markets.
- Fixed overbought and oversold thresholds may not be suitable for all market conditions.
- Moving average system has inherent lag, potentially causing delayed entry or exit timing.
Strategy Optimization Directions
- Introduce adaptive parameter mechanisms to dynamically adjust moving average periods and RSI thresholds based on market volatility.
- Add trend strength filters to reduce trading frequency in ranging markets.
- Consider implementing stop-loss and take-profit mechanisms to improve risk management.
- Incorporate volume indicators as auxiliary confirmation signals.
- Develop market environment recognition modules to use different parameter settings under different market conditions.
Summary
This strategy constructs a relatively complete trend following trading system by combining moving average systems with RSI indicators. The strategy design philosophy emphasizes signal reliability and risk control, suitable for medium to long-term trend trading. While there are some inherent limitations, the overall performance of the strategy can be further improved through the suggested optimization directions. The code implementation is professional and standardized, with good scalability, making it a trading system worthy of in-depth study and practice.
Source Pine Script
/*backtest
start: 2019-12-23 08:00:00
end: 2025-01-16 00:00:00
period: 1d
basePeriod: 1d
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT","balance":49999}]
*/

// This Pine Script™ code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © Vitaliby

//@version=5
strategy("Vitaliby MA and RSI Strategy", overlay=true)

// Входные параметры для настройки
shortMALength = input.int(9, title="Short MA Length")
longMALength = input.int(21, title="Long MA Length")
rsiLength = input.int(14, title="RSI Length")
rsiOverbought = input.int(70, title="RSI Overbought Level")
rsiOversold = input.int(30, title="RSI Oversold Level")

// Расчет скользящих средних и RSI
shortMA = ta.sma(close, shortMALength)
longMA = ta.sma(close, longMALength)
rsi = ta.rsi(close, rsiLength)

// Определение условий для входа и выхода
longCondition = ta.crossover(shortMA, longMA) and rsi > rsiOversold
shortCondition = ta.crossunder(shortMA, longMA) and rsi < rsiOverbought

// Отображение сигналов на графике
plotshape(series=longCondition, location=location.belowbar, color=color.green, style=shape.labelup, text="BUY", size=size.small)
plotshape(series=shortCondition, location=location.abovebar, color=color.red, style=shape.labeldown, text="SELL", size=size.small)

// Отображение скользящих средних на графике
plot(shortMA, color=color.blue, title="Short MA")
plot(longMA, color=color.orange, title="Long MA")

// Отображение RSI на отдельном окне
hline(rsiOverbought, "Overbought", color=color.red)
hline(rsiOversold, "Oversold", color=color.green)
plot(rsi, color=color.purple, title="RSI")

// Управление позициями
if (longCondition)
    strategy.entry("Long", strategy.long)

if (shortCondition)
    strategy.close("Long")

if (shortCondition)
    strategy.entry("Short", strategy.short)

if (longCondition)
    strategy.close("Short")
Published by ChaoZhang on the FMZ strategy square · last modified 2025-01-17. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-Moving-Average-RSI-Multi-Signal-Trend-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive Trading Strategy Based on Stochastic RSI Dual Line CrossoverPine Script · Trend following · 4h
- BB Percentage Index Trend Fading StrategyPine Script · Trend following · 1h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Crypto RSI Mini Sniper Quick Response Trend Following StrategyPine Script · Trend following · 1h
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- Dual Mode Adaptive Trend Trading Strategy EMA Crossover with ATR Volatility Based Risk Management SystemPine Script · Trend following · 1d