Dual Moving Average Strategy 442377
This strategy uses dual moving averages to form a channel and capture trend direction. Trading signals are generated when price breaks through the channel. RSI indicator is also incorporated to filter false…
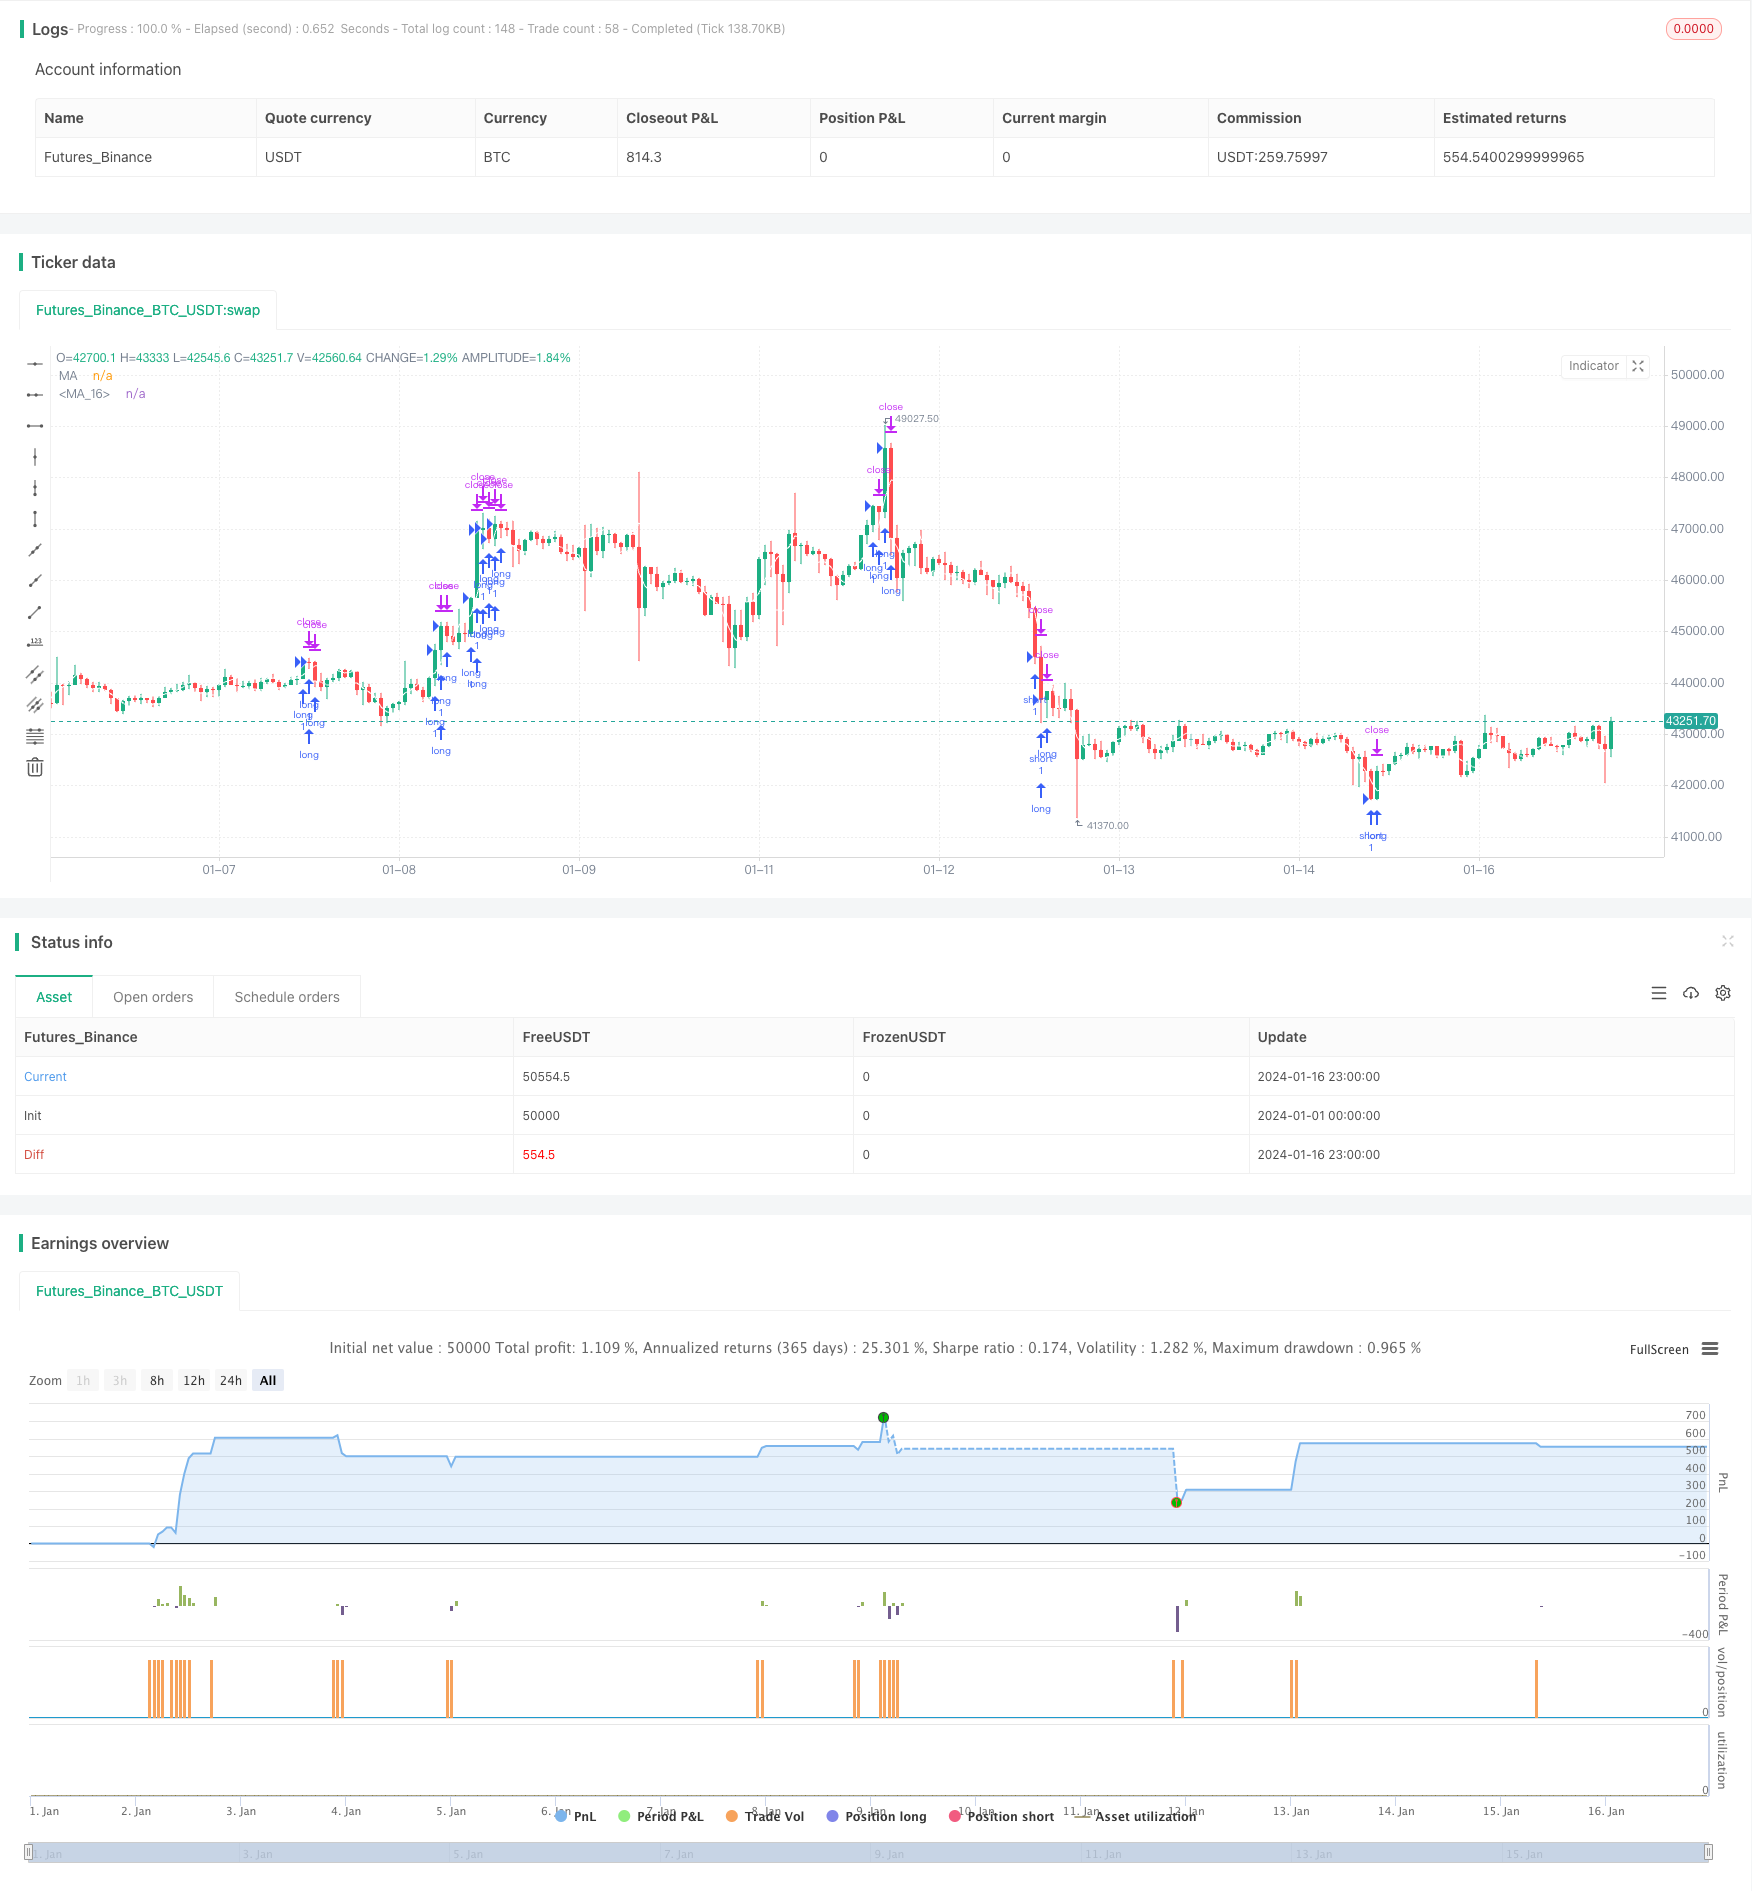
Overview
This strategy uses dual moving averages to form a channel and capture trend direction. Trading signals are generated when price breaks through the channel. RSI indicator is also incorporated to filter false breakouts. It trades only during London session with max 5 trades per day and max 2% daily loss.
Strategy Logic
The strategy employs two moving averages of length 5, one calculated from highest price and the other from lowest price, to form a price channel. Long signal triggers when close price breaks above the upper band, and short signal below the lower band.
To avoid false breakout, RSI indicator is added to gauge overbought/oversold levels. Go long only if RSI is above 80, and go short only if RSI is below 20.
Also, the strategy trades only during London session (3am - 11am), with max 5 orders per day and max 2% loss of equity per day.
Advantage Analysis
Catch the trend
The dual MA channel can effectively detect price trend direction. Breaking upper band catches the upside trend, while breaking lower band catches the downside trend.
Reduce false breakout
Using RSI overbought/oversold filter reduces some false breakout signals caused by price fluctuation.
Effective risk control
Trading only during major session and having max orders per day limit trading frequency. Max 2% daily loss also defines risk tolerance.
Risk Analysis
False breakout with volatility
Significant price swing can cause some false breakout signals, leading to unnecessary losses. Parameters can be optimized and more filters added to reduce such risk.
Fixed SL/TP risk
Using fixed pips for SL/TP risks being stopped out/missing profit in volatile market. Consider percentage-based or dynamic SL/TP instead.
Limited trading session risk
Opening positions only during fixed sessions runs the risk of missing potential trades in other hours. Consider expanding session or adjust dynamically based on real-time situation.
Optimization Directions
Parameter tuning
Optimize parameters like MA length, RSI figures, fixed SL/TP pips etc to find best combination.
Additional filters
Add more indicators or conditions to verify signals, e.g. higher volume, reduced BB width etc, to avoid false breakouts.
Dynamic SL/TP
Use percentage-based or dynamic stop loss/take profit instead of fixed pips to better handle one-sided market moves.
Manual review
Manually review signals, or only enter on confirmed breakout to prevent being trapped.
Conclusion
The strategy is fairly simple and practical overall, using dual MA channel to determine trend and RSI to filter false breakouts. Risk management via trading hours and loss limit also defines risk tolerance. Still large room for improvements, e.g. parameter tuning, better SL/TP mechanism etc.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 5 | Length |
| v_input_2_high | 0 | Source: high | close | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_3 | false | Offset |
| v_input_4 | 5 | Length |
| v_input_5_low | 0 | Source: low | high | close | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_6 | false | Offset |
| v_input_7 | 5 | length |
| v_input_8 | 10 | overSold |
| v_input_9 | 80 | overBought |
| v_input_10_close | 0 | Source RSI: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_11 | 150 | tp |
| v_input_12 | 80 | sl |
Source Pine Script
/*backtest
start: 2024-01-01 00:00:00
end: 2024-01-16 23:59:59
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © SoftKill21
//@version=4
strategy(title="Moving Average", shorttitle="MA", overlay=true)
timeinrange(res, sess) => time(res, sess) != 0
len = input(5, minval=1, title="Length")
src = input(high, title="Source")
offset = input(title="Offset", type=input.integer, defval=0, minval=-500, maxval=500)
out = sma(src, len)
plot(out, color=color.white, title="MA", offset=offset)

len2 = input(5, minval=1, title="Length")
src2 = input(low, title="Source")
offset2 = input(title="Offset", type=input.integer, defval=0, minval=-500, maxval=500)
out2 = sma(src2, len2)
plot(out2, color=color.white, title="MA", offset=offset2)

length = input( 5 )
overSold = input( 10 )
overBought = input( 80 )
price = input(close, title="Source RSI")

vrsi = rsi(price, length)

longcond= close > out and close > out2 and vrsi > overBought
shortcont = close < out and close < out2 and vrsi < overSold
tp=input(150,title="tp")
sl=input(80,title="sl")


strategy.entry("long",1,when=longcond)
//strategy.close("long",when= close < out2)
strategy.exit("long_exit","long",profit=tp,loss=sl)

strategy.entry("short",1,when=shortcont)
//strategy.close("short",when=close >out)
strategy.exit("short_exit","short",profit=tp,loss=sl)

// maxOrder = input(6, title="max trades per day")
// maxRisk = input(2,type=input.float, title="maxrisk per day")
// strategy.risk.max_intraday_filled_orders(maxOrder)

// strategy.risk.max_intraday_loss(maxRisk, strategy.percent_of_equity)


// strategy.close_all(when =not timeinrange(timeframe.period, "0300-1100"))
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-21. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-Moving-Average-Strategy-442377.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Bollinger Band Channel Breakout Trading StrategyPine Script · Breakout · 1d
- Bollinger Bands Dynamic Breakout StrategyPine Script · Breakout · 1h
- Bull Market Tracking SystemPine Script · Breakout · 1h
- Cross boundary Dynamic Range Quantitative Trading Strategy Based on Bollinger BandsPine Script · Breakout · 3h
- Dual MA Momentum Breakout StrategyPine Script · Breakout · 1h
- Dynamic Stop Loss Strategy Adaptive to ATR FluctuationsPine Script · Breakout · 1h