Dual Range Filter Momentum Trading Strategy
This strategy is a momentum trading strategy based on a dual range filter. The strategy calculates smooth ranges for fast and slow periods to obtain a comprehensive range filter, which is used to determine the…
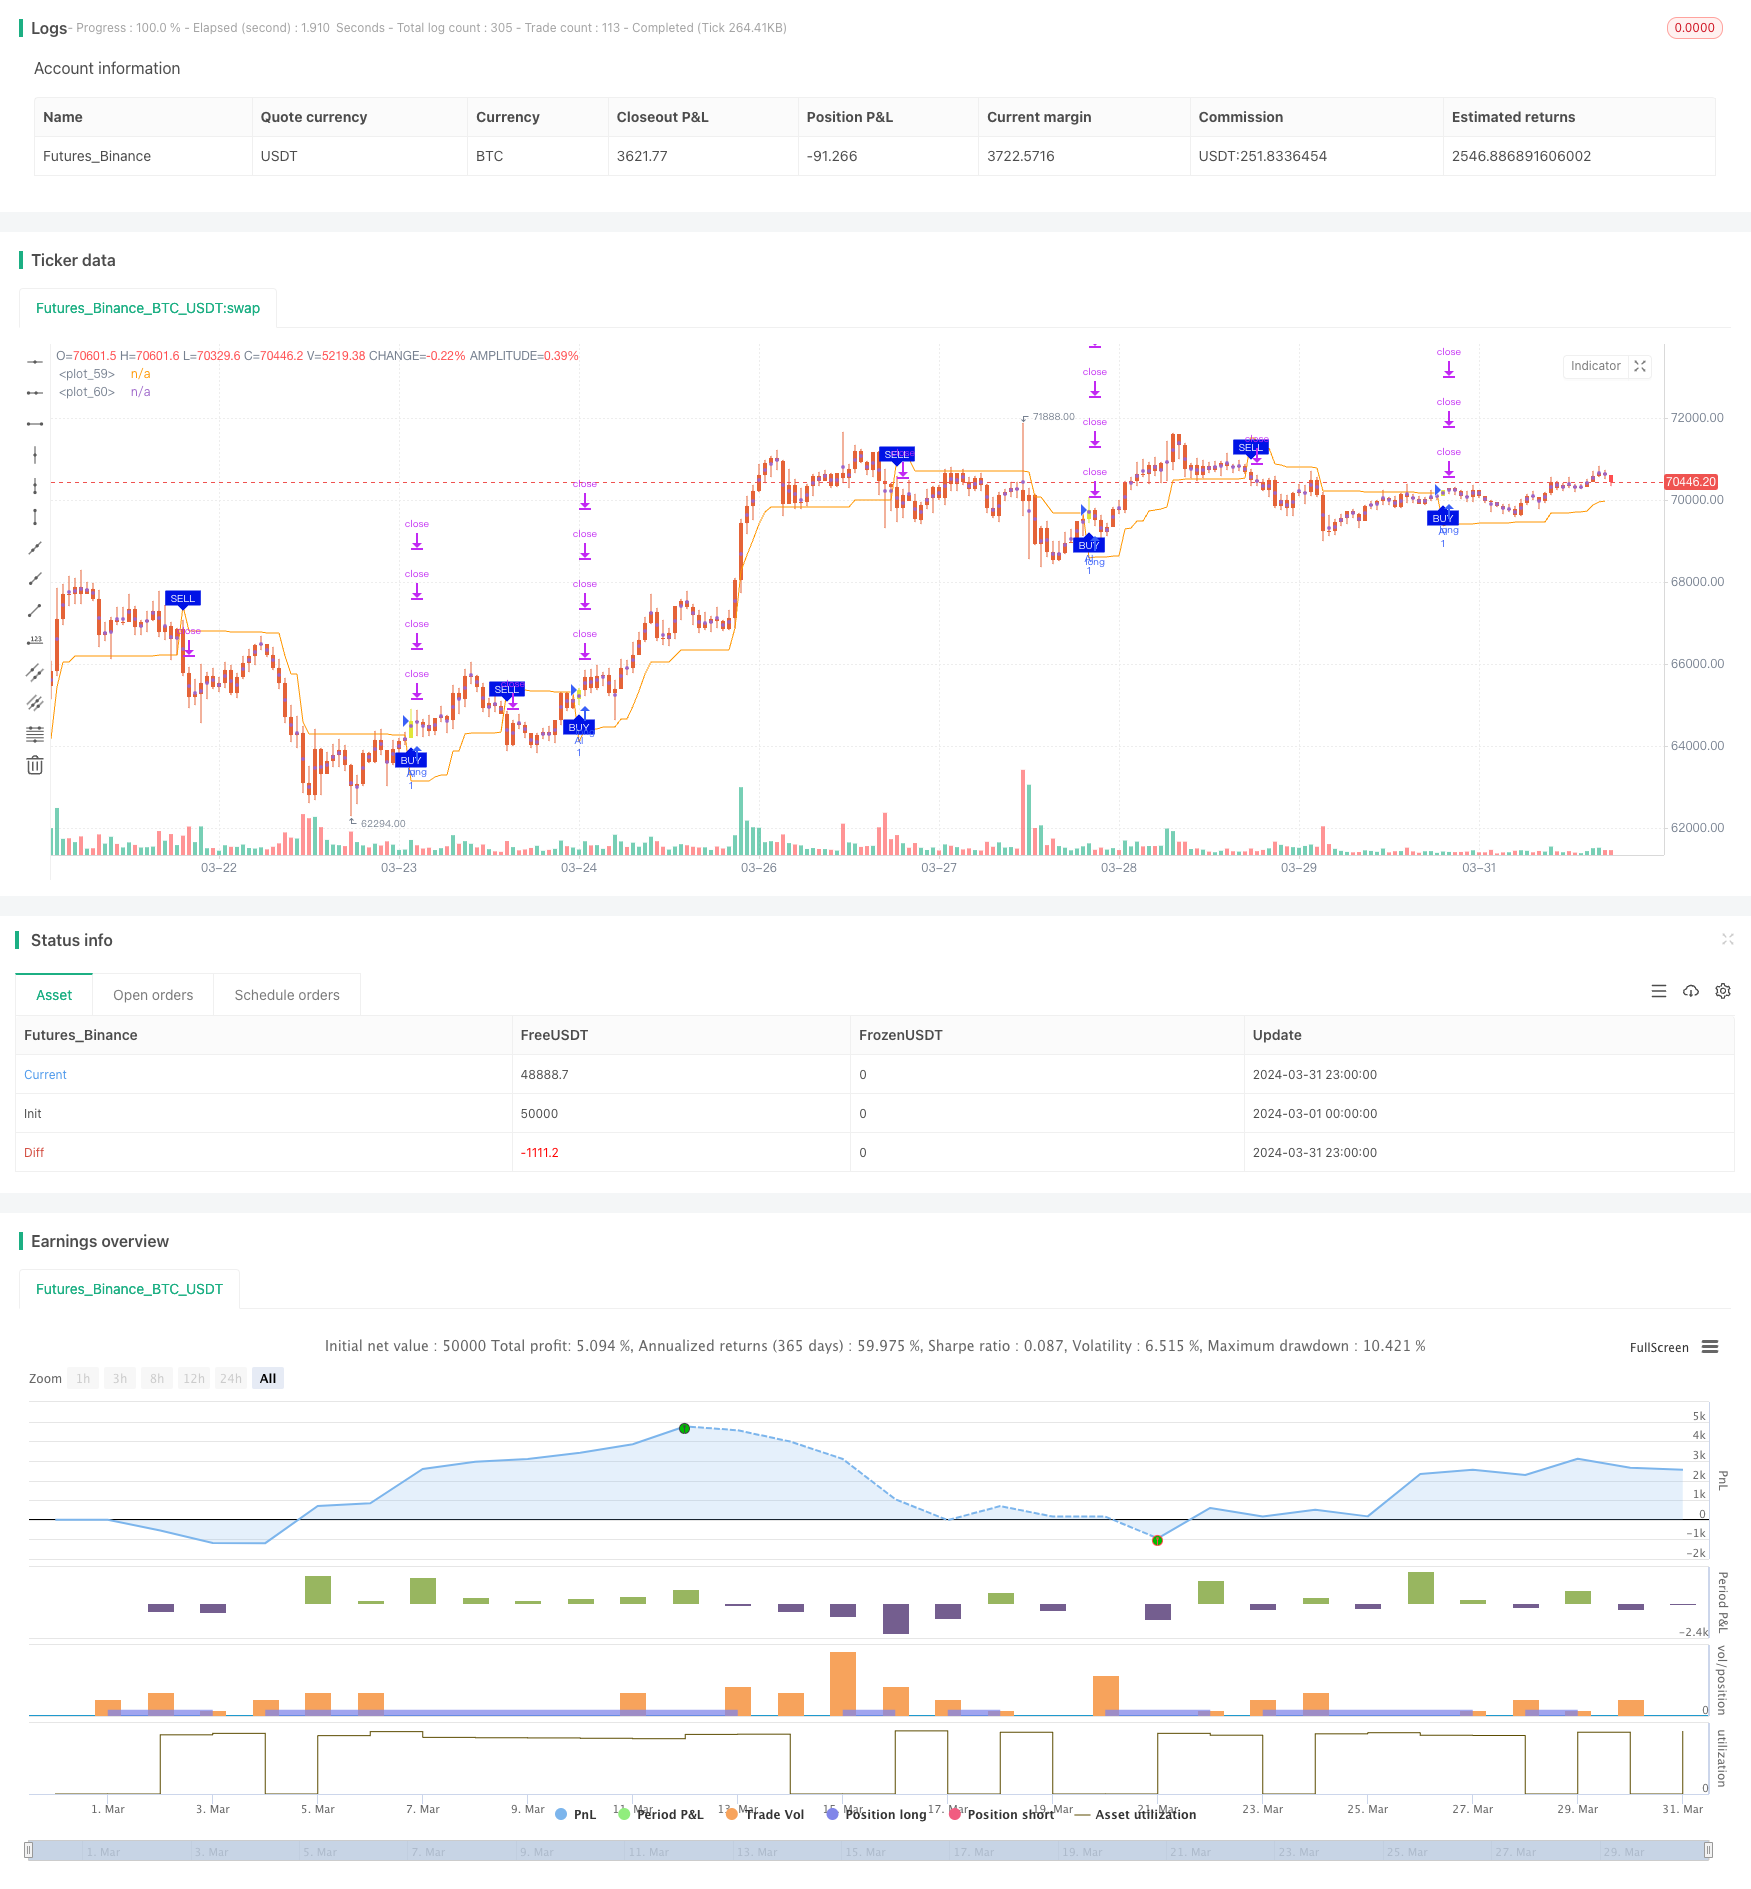
Overview
This strategy is a momentum trading strategy based on a dual range filter. The strategy calculates smooth ranges for fast and slow periods to obtain a comprehensive range filter, which is used to determine the current price trend. When the price crosses above/below this range, the strategy generates buy/sell signals. Additionally, the strategy sets four gradient take-profit levels and one stop-loss level to control risk and lock in profits.
Strategy Principle
- Calculate smooth ranges for fast and slow periods. The fast range uses a shorter period and a smaller multiple, while the slow range uses a longer period and a larger multiple.
- Use the average of the fast and slow ranges as the comprehensive range filter (TRF).
- Determine upward and downward trends by comparing the current price with the previous price.
- Calculate dynamic upper (FUB) and lower (FLB) bands as references for the trend.
- Generate buy and sell signals based on the relationship between the closing price and TRF.
- Set four gradient take-profit levels and one stop-loss level, corresponding to different position percentages and profit/loss percentages.
Advantage Analysis
- The dual range filter combines fast and slow periods, enabling the strategy to adapt to different market paces and capture more trading opportunities.
- The design of dynamic upper and lower bands helps the strategy align with the current trend and reduces false signals.
- The four gradient take-profit levels allow the strategy to secure more profits when the trend continues while locking in partial gains when the trend reverses.
- The stop-loss setting helps control the maximum loss per trade and protects account safety.
Risk Analysis
- During market fluctuations or range-bound conditions, the strategy may generate many false signals, leading to frequent trading and commission losses.
- The gradient take-profit settings may cause some profits to be locked in prematurely, preventing the strategy from fully benefiting from trend movements.
- The stop-loss setting may not completely avoid extreme losses caused by black swan events.
Optimization Direction
- Consider incorporating more technical indicators or market sentiment indicators as auxiliary conditions for trend determination to reduce false signals.
- For take-profit and stop-loss settings, dynamically adjust them according to different market environments and trading instruments to improve the strategy's adaptability.
- Based on backtesting results, further optimize parameter settings, such as the selection of fast and slow range periods, and the percentage settings for take-profit and stop-loss levels, to enhance the strategy's stability and profitability.
Summary
The dual range filter momentum trading strategy constructs a comprehensive filter using smooth ranges from fast and slow periods, combined with dynamic upper and lower bands to determine price trends and generate buy/sell signals. The strategy also sets four gradient take-profit levels and one stop-loss level to control risk and lock in profits. This strategy is suitable for use in trending markets but may generate more false signals in fluctuating markets. In the future, consider introducing more indicators, optimizing take-profit and stop-loss settings, and dynamically adjusting parameters to improve the strategy's adaptability and stability.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_string_1 | 0 | İşlem Yönü: Alis | Satis | Tum |
| v_input_int_1 | true | İlk ay |
| v_input_int_2 | true | İlk Gün |
| v_input_int_3 | 2023 | İlk Yil |
| v_input_int_4 | true | Son Ay |
| v_input_int_5 | true | Son Gün |
| v_input_int_6 | 9999 | Son Yıl |
| v_input_1_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_2 | true | Show Buy/Sell Signals ? |
| v_input_int_7 | 27 | Fast period |
| v_input_float_1 | 1.6 | Fast range |
| v_input_int_8 | 55 | Slow period |
| v_input_float_2 | 2 | Slow range |
| v_input_3 | true | Mum Renk Ayarları? |
| v_input_4 | true | Trend Bazlı Mum Rengi Değişimi? |
| v_input_float_3 | 100 | Zarar Kes Yüzdesi |
| v_input_int_9 | 5 | Satış Lot Sayısı 1.Kısım % |
| v_input_int_10 | 8 | Satış Lot Sayısı 2.Kısım % |
| v_input_int_11 | 13 | Satış Lot Sayısı 3.Kısım % |
| v_input_int_12 | 21 | Satış Lot Sayısı 4.Kısım % |
| v_input_float_4 | 13 | Kar Yüzdesi 1.Kısım |
| v_input_float_5 | 21 | Kar Yüzdesi 2.Kısım |
| v_input_float_6 | 29 | Kar Yüzdesi 3.Kısım |
| v_input_float_7 | 34 | Kar Yüzdesi 4.Kısım |
Source Pine Script
/*backtest
start: 2024-03-01 00:00:00
end: 2024-03-31 23:59:59
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
//@version=5
strategy(title='2"Twin Range Filter', overlay=true)
strat_dir_input = input.string(title='İşlem Yönü', defval='Alis', options=['Alis', 'Satis', 'Tum'])
strat_dir_value = strat_dir_input == 'Alis' ? strategy.direction.long : strat_dir_input == 'Satis' ? strategy.direction.short : strategy.direction.all
strategy.risk.allow_entry_in(strat_dir_value)

////////////////////////////

// Backtest inputs
BaslangicAy = input.int(defval=1, title='İlk ay', minval=1, maxval=12)
BaslangicGun = input.int(defval=1, title='İlk Gün', minval=1, maxval=31)
BaslangicYil = input.int(defval=2023, title='İlk Yil', minval=2000)
SonAy = input.int(defval=1, title='Son Ay', minval=1, maxval=12)
SonGun = input.int(defval=1, title='Son Gün', minval=1, maxval=31)
SonYil = input.int(defval=9999, title='Son Yıl', minval=2000)

start = timestamp(BaslangicYil, BaslangicAy, BaslangicGun, 00, 00)  // backtest start window
finish = timestamp(SonYil, SonAy, SonGun, 23, 59)  // backtest finish window
window() => true

source = input(defval=close, title='Source')
showsignals = input(title='Show Buy/Sell Signals ?', defval=true)
per1 = input.int(defval=27, minval=1, title='Fast period')
mult1 = input.float(defval=1.6, minval=0.1, title='Fast range')
per2 = input.int(defval=55, minval=1, title='Slow period')
mult2 = input.float(defval=2, minval=0.1, title='Slow range')
smoothrng(x, t, m) =>
    wper = t * 2 - 1
    avrng = ta.ema(math.abs(x - x[1]), t)
    smoothrng = ta.ema(avrng, wper) * m
    smoothrng
smrng1 = smoothrng(source, per1, mult1)
smrng2 = smoothrng(source, per2, mult2)
smrng = (smrng1 + smrng2) / 2
rngfilt(x, r) =>
    rngfilt = x
    rngfilt := x > nz(rngfilt[1]) ? x - r < nz(rngfilt[1]) ? nz(rngfilt[1]) : x - r : x + r > nz(rngfilt[1]) ? nz(rngfilt[1]) : x + r
    rngfilt
filt = rngfilt(source, smrng)
upward = 0.0
upward := filt > filt[1] ? nz(upward[1]) + 1 : filt < filt[1] ? 0 : nz(upward[1])
downward = 0.0
downward := filt < filt[1] ? nz(downward[1]) + 1 : filt > filt[1] ? 0 : nz(downward[1])
STR = filt + smrng
STS = filt - smrng
FUB = 0.0
FUB := STR < nz(FUB[1]) or close[1] > nz(FUB[1]) ? STR : nz(FUB[1])
FLB = 0.0
FLB := STS > nz(FLB[1]) or close[1] < nz(FLB[1]) ? STS : nz(FLB[1])
TRF = 0.0
TRF := nz(TRF[1]) == FUB[1] and close <= FUB ? FUB : nz(TRF[1]) == FUB[1] and close >= FUB ? FLB : nz(TRF[1]) == FLB[1] and close >= FLB ? FLB : nz(TRF[1]) == FLB[1] and close <= FLB ? FUB : FUB
al = ta.crossover(close, TRF)
sat = ta.crossunder(close, TRF)
plotshape(showsignals and al, title='Long', text='BUY', style=shape.labelup, textcolor=color.white, size=size.tiny, location=location.belowbar, color=color.rgb(0, 19, 230))
plotshape(showsignals and sat, title='Short', text='SELL', style=shape.labeldown, textcolor=color.white, size=size.tiny, location=location.abovebar, color=color.rgb(0, 19, 230))
alertcondition(al, title='Long', message='Long')
alertcondition(sat, title='Short', message='Short')
Trfff = plot(TRF)
mPlot = plot(ohlc4, title='', style=plot.style_circles, linewidth=0)
longFillColor = close > TRF ? color.green : na
shortFillColor = close < TRF ? color.red : na
fill(mPlot, Trfff, title='UpTrend Highligter', color=longFillColor, transp=90)
fill(mPlot, Trfff, title='DownTrend Highligter', color=shortFillColor, transp=90)

//////////////////////


renk1 = input(true, "Mum Renk Ayarları?")
mumrenk = input(true,title="Trend Bazlı Mum Rengi Değişimi?")
htaColor = renk1 ? (al ? color.rgb(224, 230, 57) : #E56337) : #c92626
barcolor(color = mumrenk ? (renk1 ? htaColor : na) : na)
if (al) and window()
    strategy.entry("Al", strategy.long)
if (sat) and window()
    strategy.entry("Sat", strategy.short)


per1(pcnt) =>
    strategy.position_size != 0 ? math.round(pcnt / 100 * strategy.position_avg_price / syminfo.mintick) : float(na)
zarkesmgb = input.float(title='Zarar Kes Yüzdesi', defval=100, minval=0.01)
zarkeslos = per1(zarkesmgb)
q1 = input.int(title='Satış Lot Sayısı 1.Kısım %', defval=5, minval=1)
q2 = input.int(title='Satış Lot Sayısı 2.Kısım %', defval=8, minval=1)
q3 = input.int(title='Satış Lot Sayısı 3.Kısım %', defval=13, minval=1)
q4 = input.int(title='Satış Lot Sayısı 4.Kısım %', defval=21, minval=1)
tp1 = input.float(title='Kar Yüzdesi 1.Kısım', defval=13, minval=0.01)
tp2 = input.float(title='Kar Yüzdesi 2.Kısım', defval=21, minval=0.01)
tp3 = input.float(title='Kar Yüzdesi 3.Kısım', defval=29, minval=0.01)
tp4 = input.float(title='Kar Yüzdesi 4.Kısım', defval=34, minval=0.01)
strategy.exit('✨KS1', qty_percent=q1, profit=per1(tp1), loss=zarkeslos)
strategy.exit('✨KS2', qty_percent=q2, profit=per1(tp2), loss=zarkeslos)
strategy.exit('✨KS3', qty_percent=q3, profit=per1(tp3), loss=zarkeslos)
strategy.exit('✨KS4', qty_percent=q4, profit=per1(tp4), loss=zarkeslos)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-04-01. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-Range-Filter-Momentum-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ADX Momentum Trend StrategyPine Script · Momentum · 10m
- Advanced Multi Indicator Trend Following and Momentum Quantitative Trading StrategyPine Script · Momentum · 1h
- Bollinger Bands Momentum Trend Following Quantitative StrategyPine Script · Momentum · 1d
- Cross Period Momentum EMA Strategy with RSI and Dynamic ATR Stop LossPine Script · Momentum · 1d
- Dual EMA Crossover with RSI Momentum Enhanced Trading StrategyPine Script · Momentum · 1d
- Dual EMA Momentum Trend Trading Strategy with Full Body Candle Signal SystemPine Script · Momentum · 2h