Strategy vault / Mean reversion
Dual Reversion RSI HistoAlert Strategy
The Dual Reversion RSI HistoAlert strategy generates more accurate trading signals by combining the 123 Reversion strategy and RSI HistoAlert strategy. The 123 Reversion strategy judges price reversal points and the…
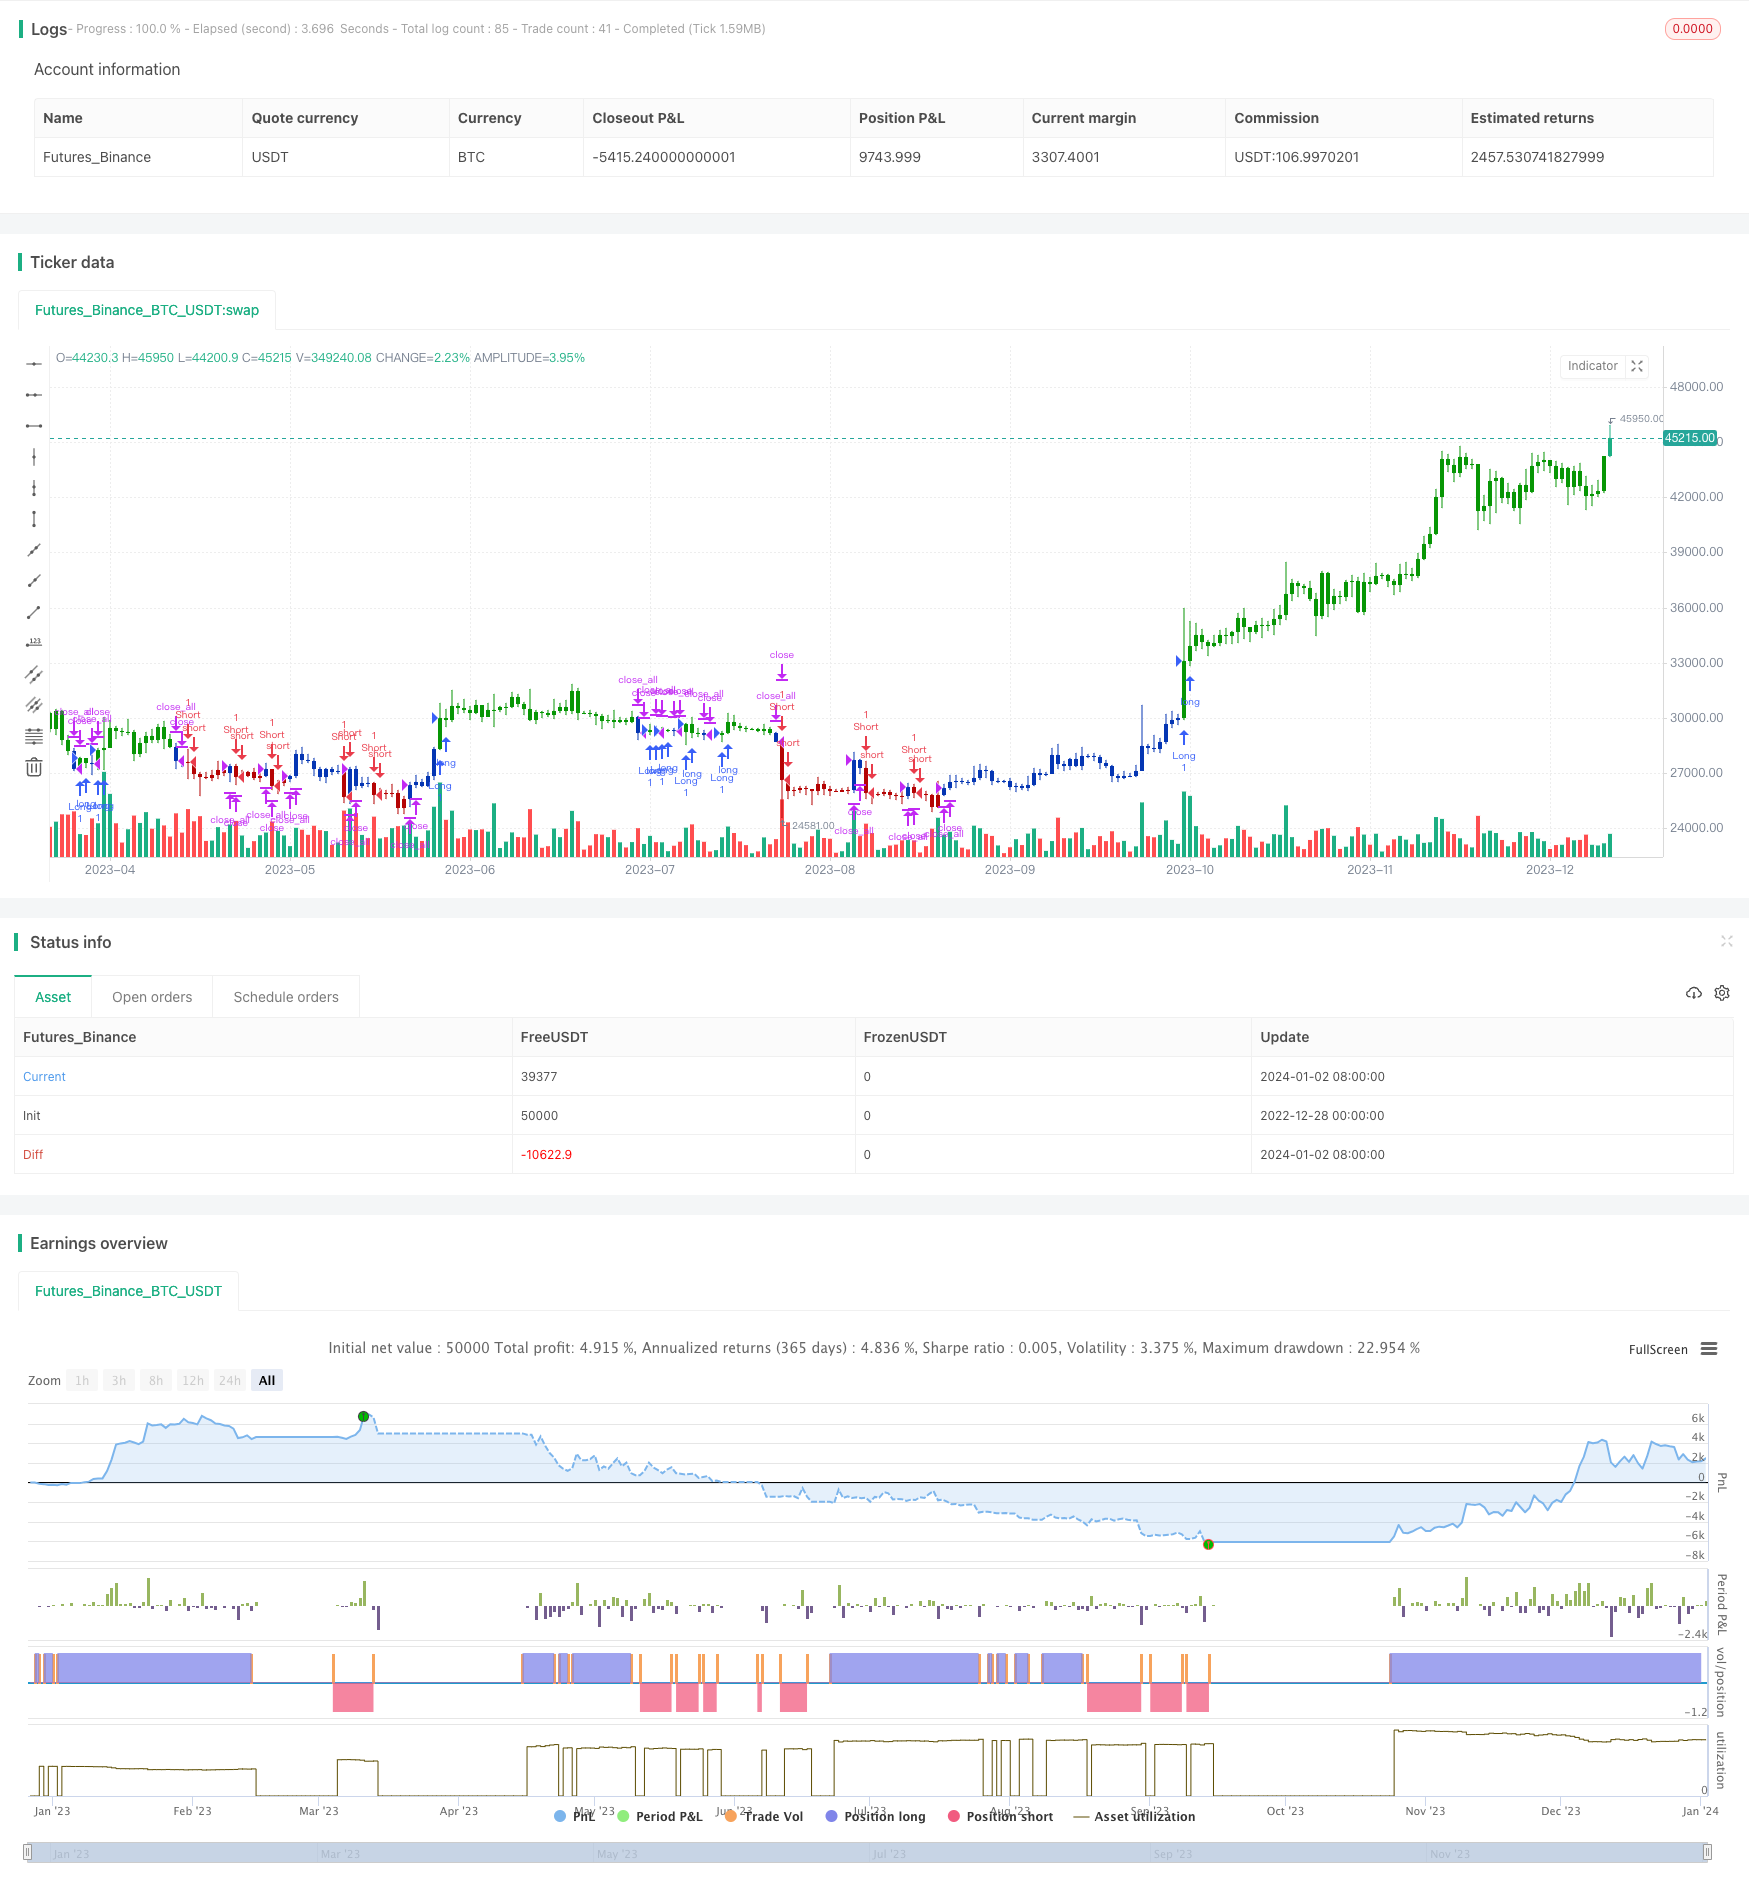
Overview
The Dual Reversion RSI HistoAlert strategy generates more accurate trading signals by combining the 123 Reversion strategy and RSI HistoAlert strategy. The 123 Reversion strategy judges price reversal points and the RSI HistoAlert strategy judges overbought and oversold points. The integrated signals from both strategies can produce more reliable trading signals.
Strategy Logic
123 Reversion Strategy
The 123 Reversion strategy is based on the hypothesis that: price reversal signals often appear 2 days before the actual price reversal.
The specific rules are:
- Buy signal: Previous close < 2-day ago close AND Current close > Previous close AND 9-day slow K-line below 50
- Sell signal: Previous close > 2-day ago close AND Current close < Previous close AND 9-day fast K-line above 50
It uses the price relationship 2 days before reversal to judge potential reversal points. The K-line indicators filter some noise signals.
RSI HistoAlert Strategy
The RSI HistoAlert strategy modifies the RSI indicator:
- Scale RSI values to -100 to 100
- Generate trading signals when RSI exceeds preset buy/sell alert lines
It uses the absolute RSI value to indicate overbought/oversold states and triggers signals.
Advantages
This strategy combines two different strategy ideas to complement strengths and generate more reliable signals:
- 123 Reversion strategy is good at catching price reversal points. RSI HistoAlert strategy is good at catching overbought/oversold points. The combination leads to more comprehensive judgements of trading chances.
- The two strategies use different input indicators. This decreases the probability of false signals and improves reliability.
- Both strategies have optimization space themselves. Further performance improvement can be achieved by parameter tuning.
Risks
The main risks are:
- Price reversal is not guaranteed. Prices may continue the trend even if 123 Reversion signal rules are met.
- RSI indicator can have a high rate of false signals. Exceeding the alert line does not always truly represent overbought/oversold status.
- Both strategies may give out wrong signals simultaneously. This doubles the wrong direction risks.
The solutions are:
- Fine tune 123 Reversion parameters to ensure signals only on high probability reversal points.
- Adjust RSI HistoAlert alert line positions to decrease false signal rates.
- Add other indicator confirmations to avoid excessive wrong direction risks.
Optimization Directions
The strategy can be optimized in aspects:
- Test different parameter combinations of both strategies to find optimum values.
- Introduce more factors like MA, volatility indicators for multifactor verification to filter out more false signals.
- Test different holding period schemes. The current strategy uses momentum holding. Trend following holding may be evaluated.
- Separate parameter sets for long term and short term.
Conclusion
The Dual Reversion RSI HistoAlert strategy combines price reversal and overbought/oversold judgment strategies for more reliable trading signals compared to single strategy usage. It has lower false signal probability and more comprehensive judgement. There is also large room for optimization via parameter tuning, multifactor verification, position holding scheme etc. for further enhancing stability and profitability.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | ---- 123 Reversal ---- |
| v_input_2 | 14 | Length |
| v_input_3 | true | KSmoothing |
| v_input_4 | 3 | DLength |
| v_input_5 | 50 | Level |
| v_input_6 | true | ---- RSI HistoAlert ---- |
| v_input_7 | 13 | RSIPeriod |
| v_input_8 | -10 | BuyAlertLevel |
| v_input_9 | 10 | SellAlertLevel |
| v_input_10 | 1.5 | RSIHistoModify |
| v_input_11 | false | Trade reverse |
Source Pine Script
/*backtest
start: 2022-12-28 00:00:00
end: 2024-01-03 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
////////////////////////////////////////////////////////////
//  Copyright by HPotter v1.0 28/06/2021
// This is combo strategies for get a cumulative signal.
//
// First strategy
// This System was created from the Book "How I Tripled My Money In The
// Futures Market" by Ulf Jensen, Page 183. This is reverse type of strategies.
// The strategy buys at market, if close price is higher than the previous close
// during 2 days and the meaning of 9-days Stochastic Slow Oscillator is lower than 50.
// The strategy sells at market, if close price is lower than the previous close price
// during 2 days and the meaning of 9-days Stochastic Fast Oscillator is higher than 50.
//
// Second strategy
// This simple indicator modified RSI
//
// WARNING:
// - For purpose educate only
// - This script to change bars colors.
////////////////////////////////////////////////////////////
Reversal123(Length, KSmoothing, DLength, Level) =>
    vFast = sma(stoch(close, high, low, Length), KSmoothing)
    vSlow = sma(vFast, DLength)
    pos = 0.0
    pos := iff(close[2] < close[1] and close > close[1] and vFast < vSlow and vFast > Level, 1,
	         iff(close[2] > close[1] and close < close[1] and vFast > vSlow and vFast < Level, -1, nz(pos[1], 0)))
	pos


RSI_Hist(RSIPeriod,BuyAlertLevel,SellAlertLevel,RSIHistoModify) =>
    pos = 0.0
    xPrice = close
    RSIMain = (rsi(xPrice, RSIPeriod) - 50) * RSIHistoModify
    pos:= iff(RSIMain > BuyAlertLevel, 1,
    	     iff(RSIMain < SellAlertLevel, -1, nz(pos[1], 0)))
    pos

strategy(title="Combo Backtest 123 Reversal & RSI HistoAlert", shorttitle="Combo", overlay = true)
line1 = input(true, "---- 123 Reversal ----")
Length = input(14, minval=1)
KSmoothing = input(1, minval=1)
DLength = input(3, minval=1)
Level = input(50, minval=1)
//-------------------------
line2 = input(true, "---- RSI HistoAlert ----")
RSIPeriod = input(13, minval=1)
BuyAlertLevel = input(-10)
SellAlertLevel = input(10)
RSIHistoModify = input(1.5)
reverse = input(false, title="Trade reverse")
posReversal123 = Reversal123(Length, KSmoothing, DLength, Level)
posRSI_Hist = RSI_Hist(RSIPeriod,BuyAlertLevel,SellAlertLevel,RSIHistoModify)
pos = iff(posReversal123 == 1 and posRSI_Hist == 1 , 1,
	   iff(posReversal123 == -1 and posRSI_Hist == -1, -1, 0))
possig = iff(reverse and pos == 1, -1,
          iff(reverse and pos == -1 , 1, pos))
if (possig == 1 )
    strategy.entry("Long", strategy.long)
if (possig == -1 )
    strategy.entry("Short", strategy.short)
if (possig == 0)
    strategy.close_all()
barcolor(possig == -1 ? #b50404: possig == 1 ? #079605 : #0536b3 )Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-04. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dual-Reversion-RSI-HistoAlert-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- Bollinger Bands Stochastic RSI Extreme Strategy BBSR Extreme StrategyPine Script · Mean reversion · 1h
- BuySell Strategy depends on AOStochRSIATRPine Script · Mean reversion · 30m
- Byron Serpent Cloud Quant StrategyPine Script · Mean reversion · 1h
- Dual Momentum Trend Reversal Strategy Based on RSI and Stochastic RSIPine Script · Mean reversion · 1h
- Dynamic Adaptive Multi Timeframe Trend Following and Range Reversal Hybrid StrategyPine Script · Mean reversion · 2d