Dynamic ATR Stop Loss Center Line Strategy
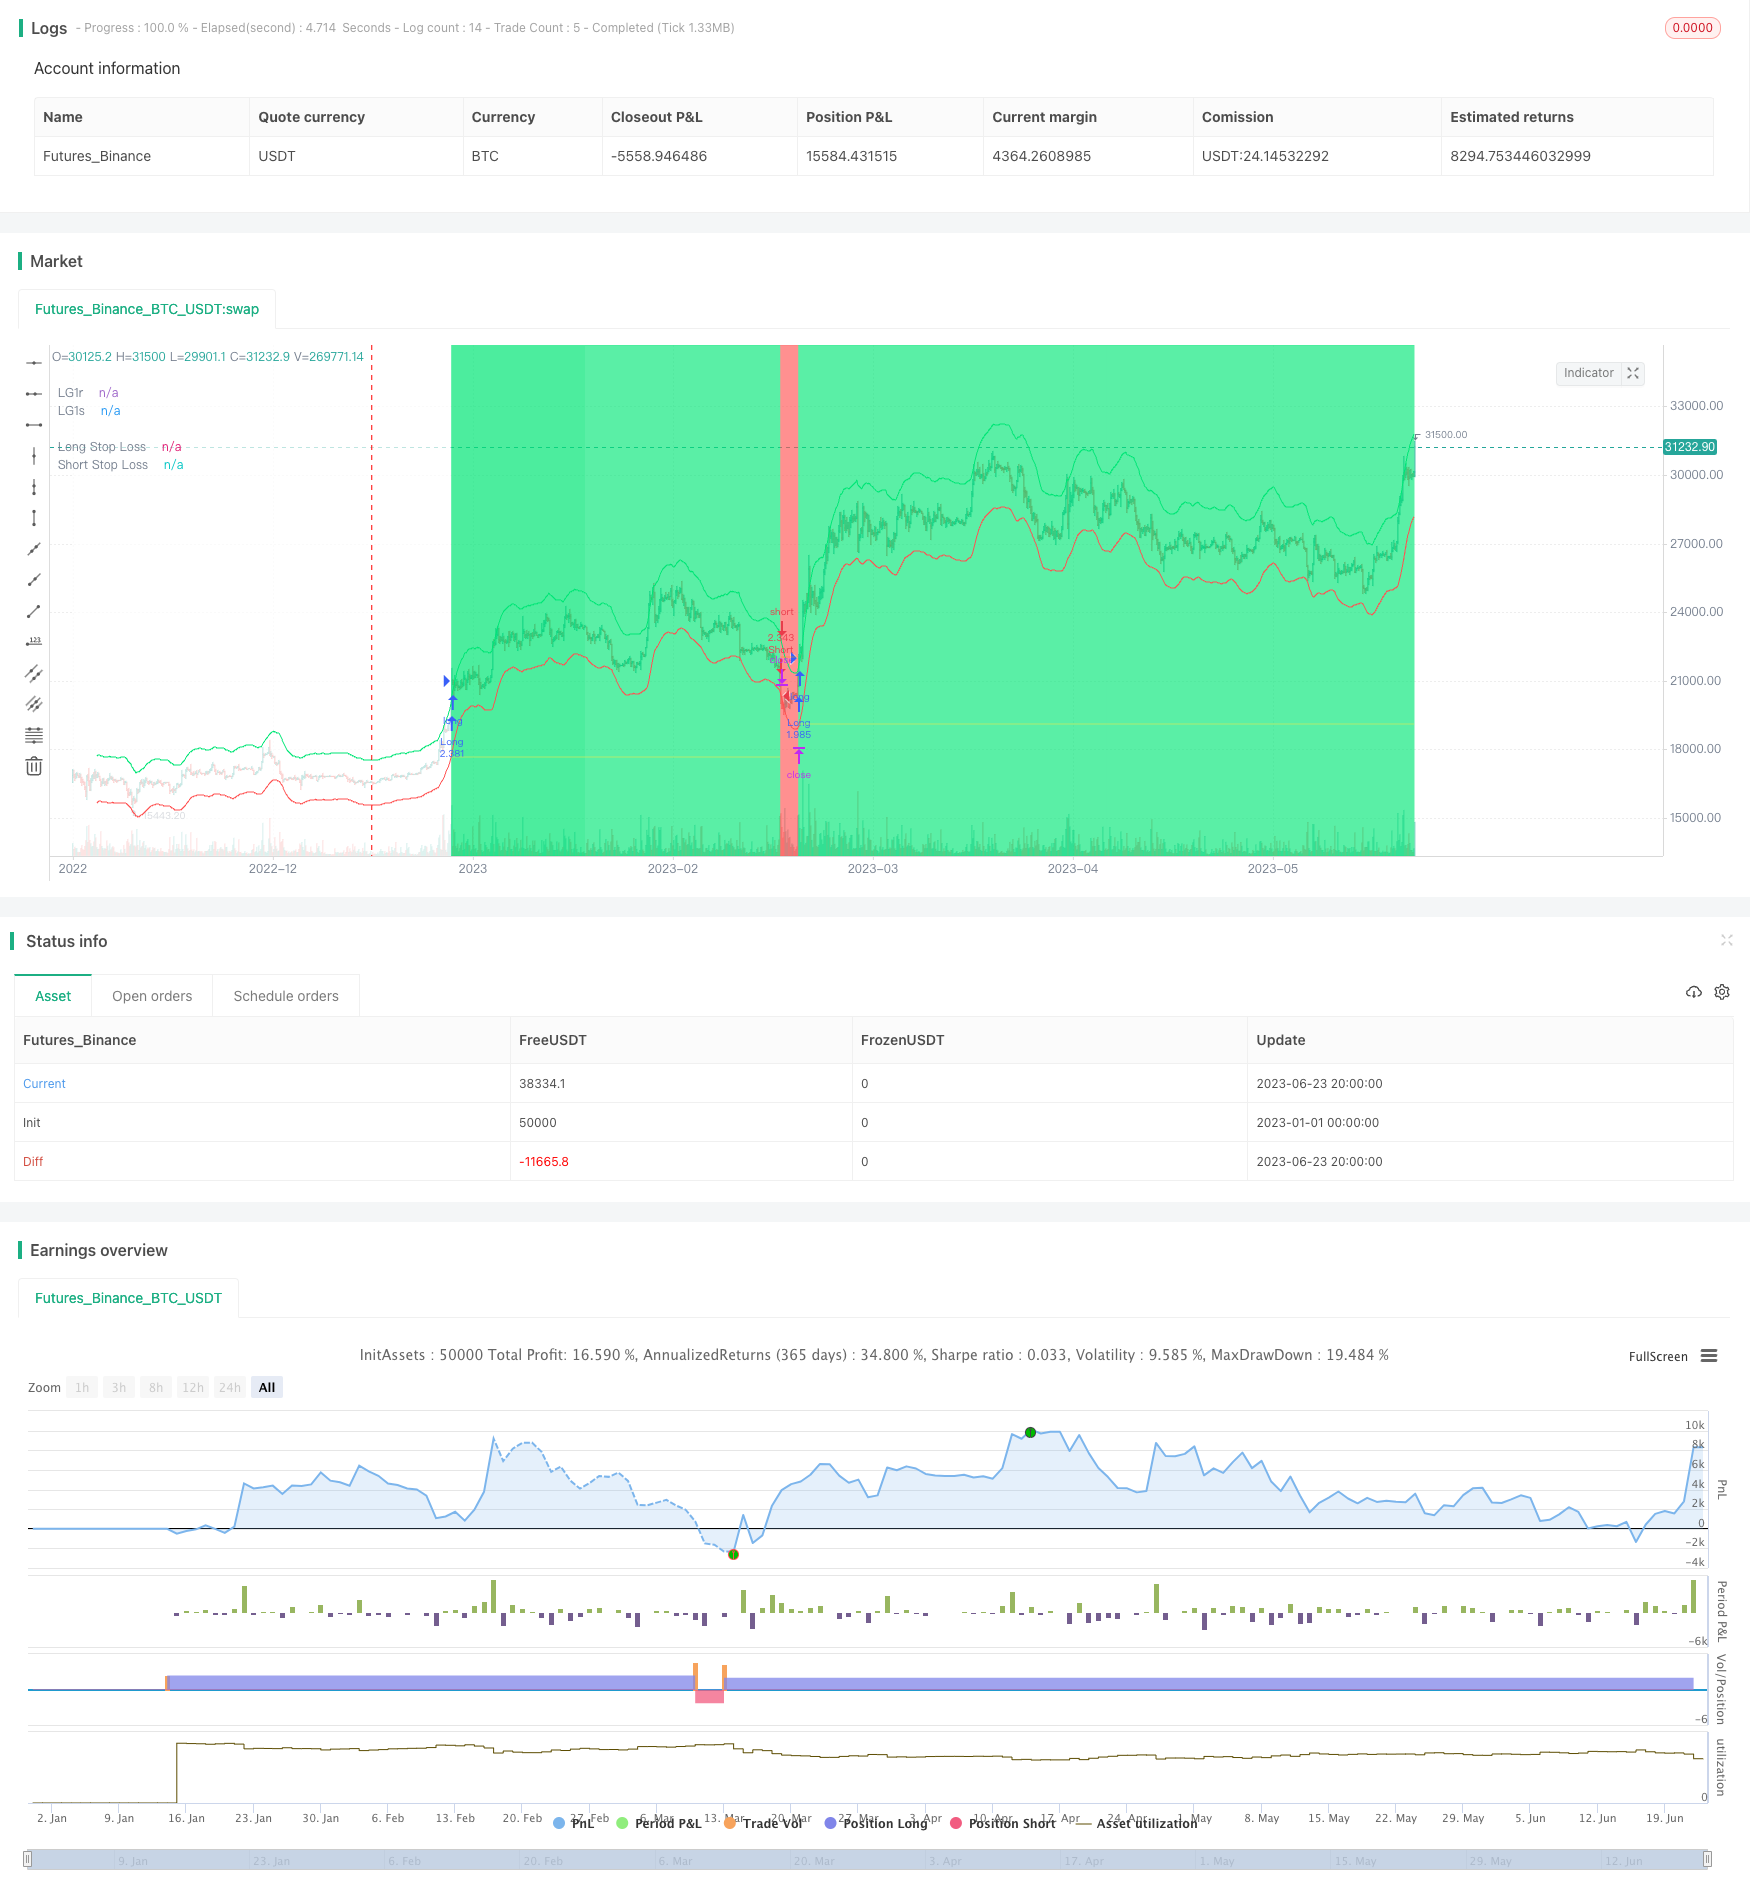
This strategy uses a linear regression function and least squares method to calculate a price channel, consisting of two green and red lines. It employs a dynamic stop loss based on recent ATR.
Overview
This strategy uses a linear regression function and least squares method to calculate a price channel, consisting of two green and red lines. It employs a dynamic stop loss based on recent ATR.
Strategy Logic
The strategy calculates the center line xLG using linear regression with length 25 and shift 5. Then it takes 6% above and below the center line as channel range, with xLG1r as the upper line and xLG1s as the lower line.
When price is above xLG1r, it goes long. When price is below xLG1s, it goes short. It records the last long and short time. A long signal is generated when the last long time is greater than the last short time. A short signal is generated when the last short time is greater than the last long time.
The dynamic ATR stop loss uses ATR period of 1 and multiplier of 2. For long trades, the stop loss is closing price minus ATR value times multiplier. For short trades, the stop loss is closing price plus ATR value times multiplier.
Advantage Analysis
- Uses linear regression channel to track long term trends
- ATR-based stop loss adjusts dynamically to avoid stops being too wide or too tight
- Price breakout signals help avoid false signals
Risks and Improvements
- Regression channel parameters need optimization, current range may be too narrow
- ATR multiplier also needs testing to find optimal parameter
- Consider adding confirmation on breakout to avoid false breakouts
Optimization Directions
- Test different regression period lengths to find better parameters
- Try different ATR periods and stop loss multipliers
- Add additional confirmation on breakout signals, like volume breakout
Conclusion
This strategy combines multiple techniques like trend following, dynamic stops and breakout signals to create an adaptive trend tracking system. Further enhancements in parameter optimization and signal filtering can improve robustness and profitability. It provides a valuable approach for quant traders.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 2017 | Backtest Start Year |
| v_input_2 | true | Backtest Start Month |
| v_input_3 | true | Backtest Start Day |
| v_input_4 | 2019 | Backtest Stop Year |
| v_input_5 | 12 | Backtest Stop Month |
| v_input_6 | 31 | Backtest Stop Day |
| v_input_7 | 25 | Length |
| v_input_8 | 5 | m |
| v_input_9 | 6 | COG % |
| v_input_10 | true | ATR Stop Period |
| v_input_11 | 2 | ATR Stop Multiplier |
Source Pine Script
/*backtest
start: 2023-01-01 00:00:00
end: 2023-06-24 00:00:00
period: 4h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
// Thanks to HPotter for the original code for Center of Gravity Backtest
strategy("Center of Gravity BF ?", overlay=true, initial_capital=10000, default_qty_type=strategy.percent_of_equity, default_qty_value=100, commission_type=strategy.commission.percent, commission_value=0.15)

/////////////// Time Frame ///////////////
testStartYear = input(2017, "Backtest Start Year")
testStartMonth = input(1, "Backtest Start Month")
testStartDay = input(1, "Backtest Start Day")
testPeriodStart = timestamp(testStartYear,testStartMonth,testStartDay, 0, 0)

testStopYear = input(2019, "Backtest Stop Year")
testStopMonth = input(12, "Backtest Stop Month")
testStopDay = input(31, "Backtest Stop Day")
testPeriodStop = timestamp(testStopYear,testStopMonth,testStopDay, 0, 0)

testPeriod() => true

///////////// Center of Gravity /////////////
Length = input(25, minval=1)
m = input(5, minval=0)
Percent = input(6, minval=0, title="COG %")

xLG = linreg(close, Length, m)
xLG1r = xLG + ((close * Percent) / 100)
xLG1s = xLG - ((close * Percent) / 100)

pos = 0.0
pos := iff(close > xLG1r, 1, iff(close < xLG1s, -1, nz(pos[1], 0)))
possig = iff(pos == 1, 1, iff(pos == -1, -1, pos))

/////////////// Srategy ///////////////
long = possig == 1
short = possig == -1

last_long = 0.0
last_short = 0.0
last_long := long ? time : nz(last_long[1])
last_short := short ? time : nz(last_short[1])

long_signal = crossover(last_long, last_short)
short_signal = crossover(last_short, last_long)

last_open_long_signal = 0.0
last_open_short_signal = 0.0
last_open_long_signal := long_signal ? open : nz(last_open_long_signal[1])
last_open_short_signal := short_signal ? open : nz(last_open_short_signal[1])

last_long_signal = 0.0
last_short_signal = 0.0
last_long_signal := long_signal ? time : nz(last_long_signal[1])
last_short_signal := short_signal ? time : nz(last_short_signal[1])

in_long_signal = last_long_signal > last_short_signal
in_short_signal = last_short_signal > last_long_signal

last_high = 0.0
last_low = 0.0
last_high := not in_long_signal ? na : in_long_signal and (na(last_high[1]) or high > nz(last_high[1])) ? high : nz(last_high[1])
last_low := not in_short_signal ? na : in_short_signal and (na(last_low[1]) or low < nz(last_low[1])) ? low : nz(last_low[1])

since_longEntry = barssince(last_open_long_signal != last_open_long_signal[1])
since_shortEntry = barssince(last_open_short_signal != last_open_short_signal[1])

/////////////// Dynamic ATR Stop Losses ///////////////
atrLkb = input(1, minval=1, title='ATR Stop Period')
atrMult = input(2, step=0.25, title='ATR Stop Multiplier')
atr1 = atr(atrLkb)

longStop = 0.0
longStop :=  short_signal ? na : long_signal ? close - (atr1 * atrMult) : longStop[1]
shortStop = 0.0
shortStop := long_signal ? na : short_signal ? close + (atr1 * atrMult) : shortStop[1]

/////////////// Execution ///////////////
if testPeriod()
    strategy.entry("Long",  strategy.long, when=long)
    strategy.entry("Short", strategy.short, when=short)
    strategy.exit("Long SL", "Long", stop=longStop, when=since_longEntry > 0)
    strategy.exit("Short SL", "Short", stop=shortStop, when=since_shortEntry > 0)

/////////////// Plotting ///////////////
plot(xLG1r, color=color.lime, title="LG1r")
plot(xLG1s, color=color.red, title="LG1s")
plot(strategy.position_size <= 0 ? na : longStop, title="Long Stop Loss", color=color.yellow, style=plot.style_circles, linewidth=1)
plot(strategy.position_size >= 0 ? na : shortStop, title="Short Stop Loss", color=color.orange, style=plot.style_circles, linewidth=1)
bgcolor(strategy.position_size > 0 ? color.lime : strategy.position_size < 0 ? color.red : color.white, transp=90)
bgcolor(long_signal ? color.lime : short_signal ? color.red : na, transp=60)Published by ChaoZhang on the FMZ strategy square · last modified 2023-10-16. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dynamic-ATR-Stop-Loss-Center-Line-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ATR Trailing Stops StrategyPine Script · Breakout · 1h
- ATR Trend Breakout StrategyPine Script · Breakout · 1d
- Advanced Multi Pattern Breakout Trading StrategyPine Script · Breakout · 1d
- BB Breakout StrategyPine Script · Breakout · 1d
- Bollinger Band Breakout Trend Following StrategyPine Script · Breakout · 1d
- Breakout Strategy Based on Turtle TradingPine Script · Breakout · 1d