Dynamic Price Channel with Stop Loss Tracking Strategy
This strategy is developed based on the Donchian price channel indicator. The indicator forms a price channel by calculating the highest and lowest prices over a certain period. The strategy utilizes the price…
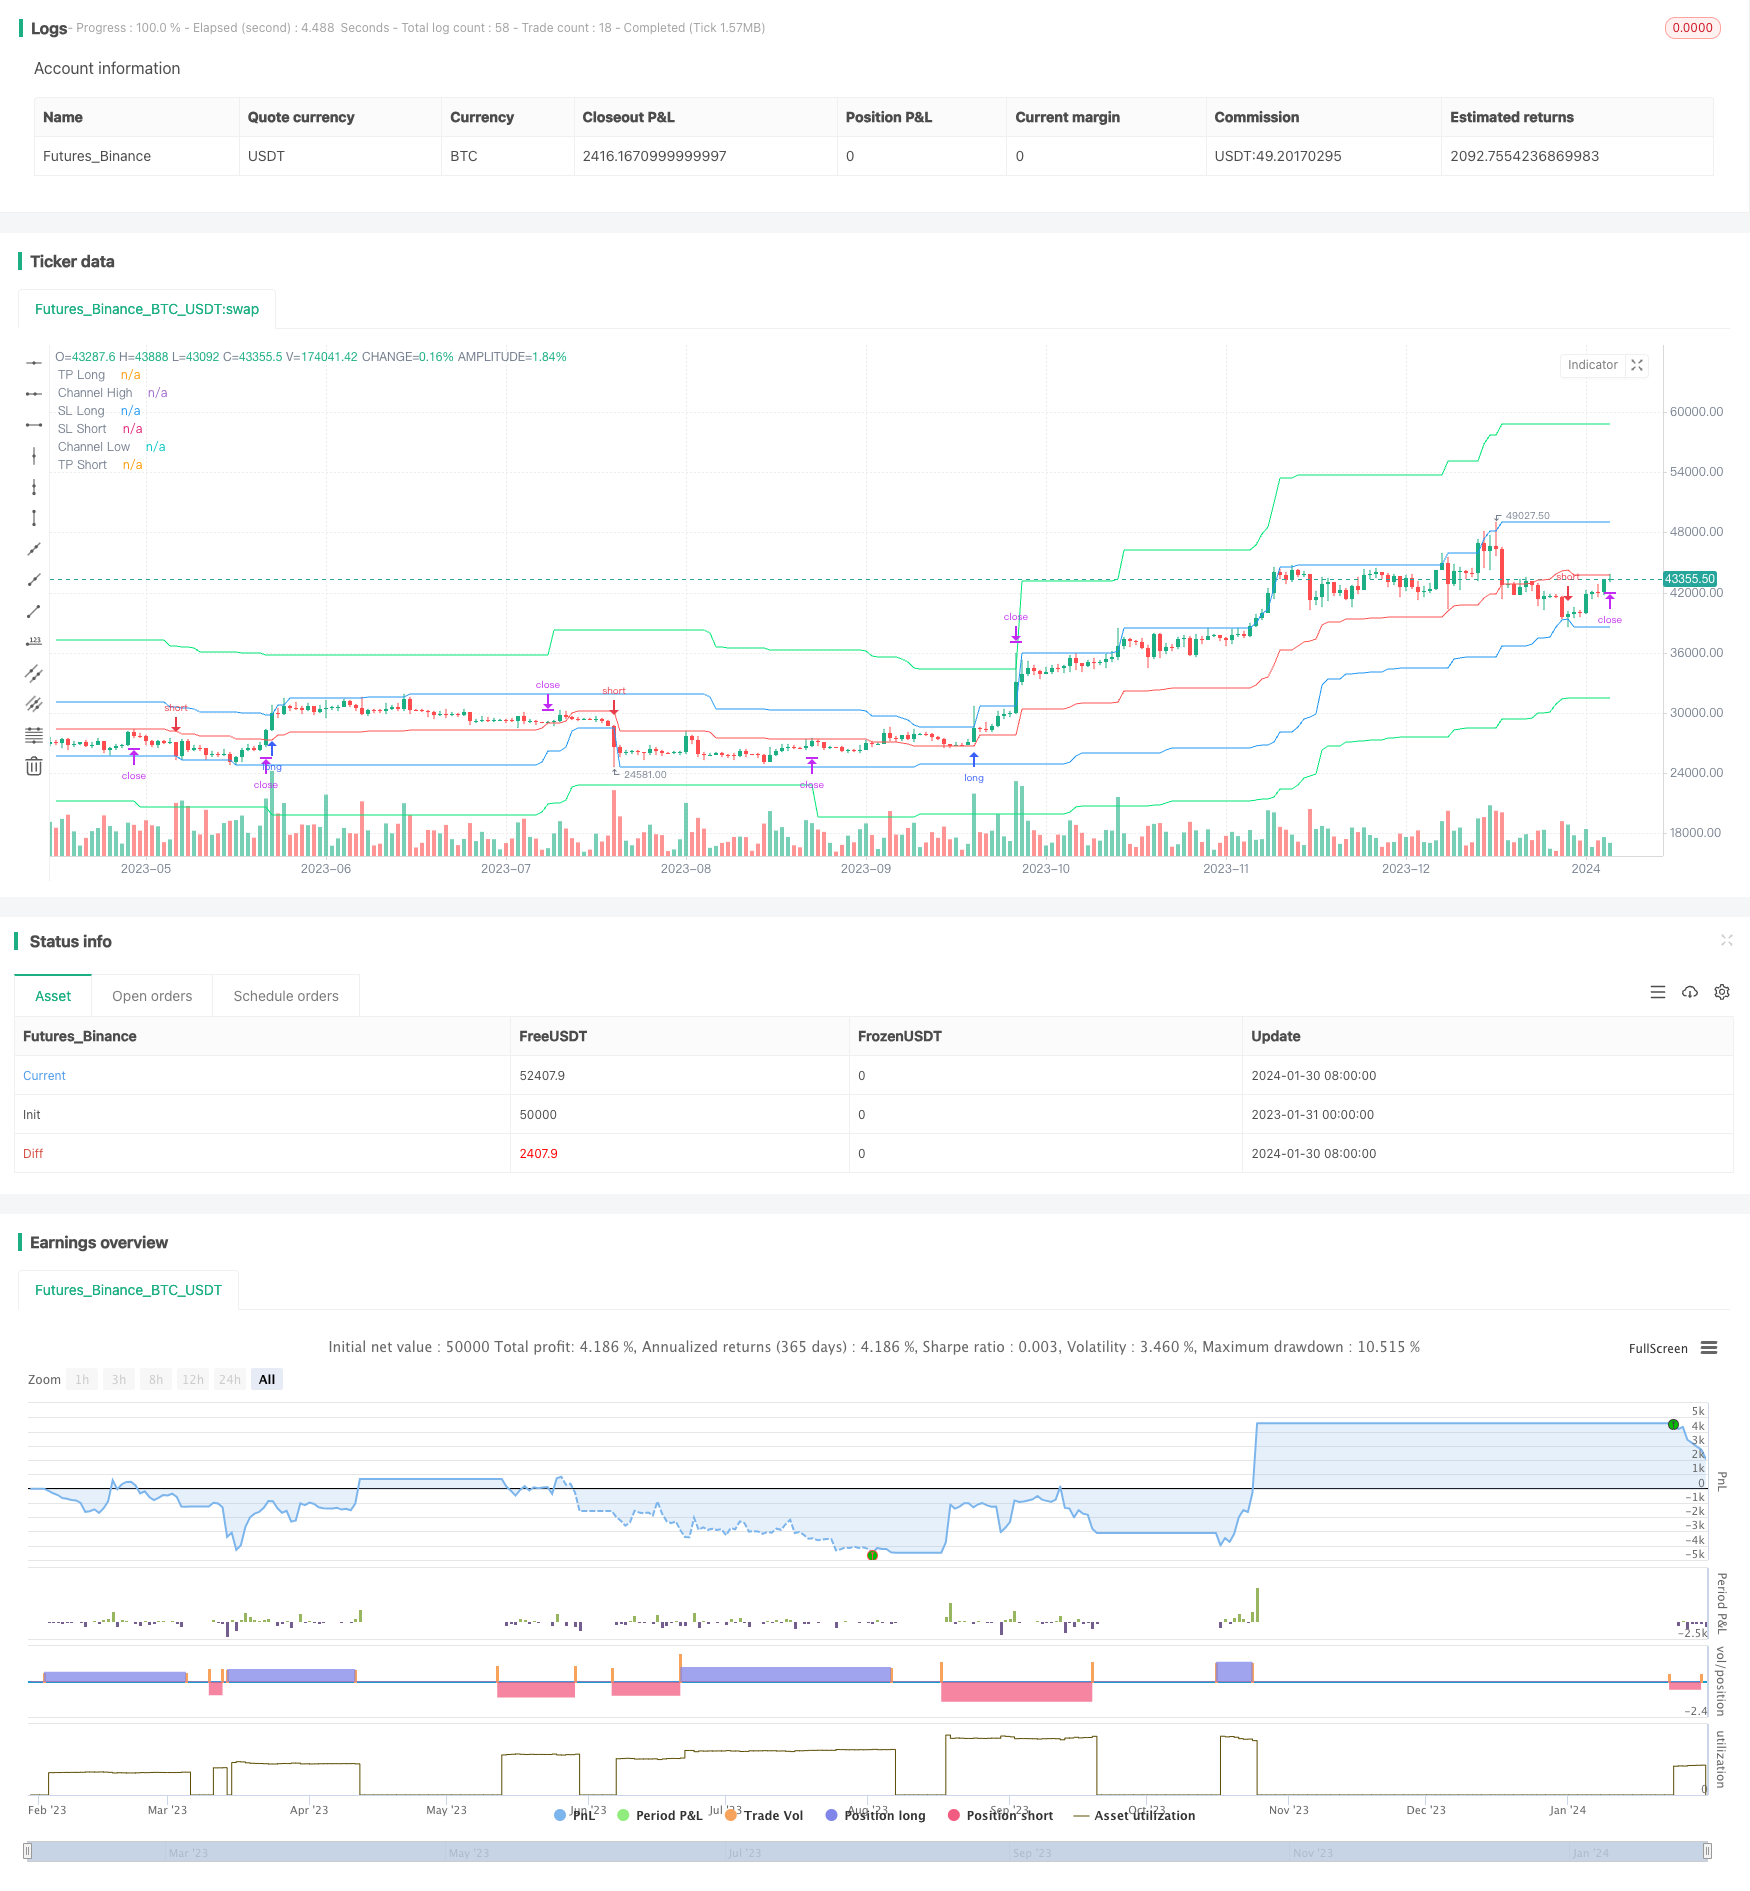
Overview
This strategy is developed based on the Donchian price channel indicator. The indicator forms a price channel by calculating the highest and lowest prices over a certain period. The strategy utilizes the price channel to implement two-way trading and sets stop loss and take profit prices. The stop loss price is fixed to the middle line of the price channel, and the take profit price is set to a certain percentage beyond the upper and lower limits of the price channel. The strategy also implements tracking of stop loss and take profit.
Strategy Principle
Firstly, the strategy calculates the upper limit h and lower limit l of the price channel based on the parameter pclen. The middle line center is the average of the upper and lower limits of the price channel. Then, take profit prices tpl and tps are calculated according to the take profit parameters tp for long and short positions. The stop loss price is fixed to the middle line center of the price channel. When the price breaks through the price channel, trading positions of different directions are calculated according to the risk sizes risklong and riskshort. The strategy will close positions when the price re-enters the channel. In addition, time filtering is set to only trade within the specified date range.
The specific trading logic is:
Long entry signal: open long when price is greater than the channel upper limit h and falls back into the channel
Long exit signal: close long when price is lower than the channel middle line center (stop loss) or higher than take profit price tpl (take profit)
Short entry signal: open short when price is less than the channel lower limit l and falls back into the channel
Short exit signal: close short when price is higher than the channel middle line center (stop loss) or lower than take profit price tps (take profit)
Advantage Analysis
The advantages of this strategy are:
- Two-way trading can capture reversals of price trends
- Use price channel to determine trend direction and avoid false breakouts
- Set stop loss and take profit to control risks
- Calculate position size associated with risk size to achieve controllable risks
- Implement tracking of stop loss and take profit to lock in more profits
Risk Analysis
There are also some risks in this strategy:
- Improper parameter settings of price channel may lead to too high trading frequency or missing trading opportunities
- Stop loss price set too wide may increase risk exposure
- Tracking take profit may trigger prematurely in high volatility periods
These risks can be reduced and controlled by adjusting parameters and manual monitoring.
Optimization Directions
This strategy can also be optimized in the following aspects:
- Add more indicator filters to avoid frequent opening and closing in range-bound markets
- Different stop loss and take profit algorithms can be tested, such as ATR stop loss
- Expand to a cross-timeframe trading system using higher timeframe to determine trend direction
- Add position sizing module to adjust positions based on capital utilization ratio
- Incorporate machine learning models to judge the success rate of price breakouts to avoid false breakouts
Conclusion
In conclusion, this is an effective strategy to implement two-way trading using price channel indicators. With proper stop loss, take profit, and position sizing control modules, risks can be well controlled. With some optimizations and adjustments, it can become a powerful quantitative trading strategy.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | Long |
| v_input_2 | true | Short |
| v_input_3 | 20 | Take-profit, % |
| v_input_4 | 0 | Take-profit type: 2. Fix | 1. None | 3. Trailing |
| v_input_5 | 0 | Take-profit type: 2. Center | 1. None |
| v_input_6 | 5 | Risk size for long, % |
| v_input_7 | 5 | Risk size for short, % |
| v_input_8 | 50 | Price Channel Length |
| v_input_9 | true | Show lines |
| v_input_10 | false | Show Background |
| v_input_11 | true | Show Offset |
| v_input_12 | true | Show label |
| v_input_13 | 1900 | From Year |
| v_input_14 | 2100 | To Year |
| v_input_15 | true | From Month |
| v_input_16 | 12 | To Month |
| v_input_17 | true | From day |
| v_input_18 | 31 | To day |
Source Pine Script
/*backtest
start: 2023-01-31 00:00:00
end: 2024-01-31 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//Noro
//2020

//@version=4
strategy(title = "Noro's RiskDonchian Strategy", shorttitle = "RiskDonchian str", overlay = true, default_qty_type = strategy.percent_of_equity, initial_capital = 100, default_qty_value = 100, commission_value = 0.1)

//Settings
needlong = input(true, defval = true, title = "Long")
needshort = input(true, defval = true, title = "Short")
tp = input(defval = 20.0, minval = 1, title = "Take-profit, %")
tptype = input(defval = "2. Fix", options = ["1. None", "2. Fix", "3. Trailing"], title = "Take-profit type")
sltype = input(defval = "2. Center", options = ["1. None", "2. Center"], title = "Take-profit type")
risklong  = input(5.0, minval = 0.0, maxval = 99.9, title = "Risk size for long, %")
riskshort = input(5.0, minval = 0.0, maxval = 99.9, title = "Risk size for short, %")
pclen = input(50, minval = 1, title = "Price Channel Length")
showll = input(true, defval = true, title = "Show lines")
showbg = input(false, defval = false, title = "Show Background")
showof = input(true, defval = true, title = "Show Offset")
showlabel = input(true, defval = true, title = "Show label")
fromyear = input(1900, defval = 1900, minval = 1900, maxval = 2100, title = "From Year")
toyear = input(2100, defval = 2100, minval = 1900, maxval = 2100, title = "To Year")
frommonth = input(01, defval = 01, minval = 01, maxval = 12, title = "From Month")
tomonth = input(12, defval = 12, minval = 01, maxval = 12, title = "To Month")
fromday = input(01, defval = 01, minval = 01, maxval = 31, title = "From day")
today = input(31, defval = 31, minval = 01, maxval = 31, title = "To day")

//Price Channel
h = highest(high, pclen)
l = lowest(low, pclen)
center = (h + l) / 2

//Take-profit
tpl = 0.0
tpl := tptype == "2. Fix" and strategy.position_size > 0 ? tpl[1] : h * (100 + tp) / 100

//Stop-loss
tps = 0.0
tps := tptype == "2. Fix" and strategy.position_size < 0 ? tps[1] : l * (100 - tp) / 100

//Lines
tplcol = showll and needlong and tptype != "1. None" ? color.lime : na
pclcol = showll and needlong ? color.blue : na
sllcol = showll and needlong and sltype != "1. None" ? color.red : na
tpscol = showll and needshort and tptype != "1. None" ? color.lime : na
pcscol = showll and needshort ? color.blue : na
slscol = showll and needshort and sltype != "1. None" ? color.red : na
offset = showof ? 1 : 0
plot(tpl, offset = offset, color = tplcol, title = "TP Long")
plot(h, offset = offset, color = pclcol, title = "Channel High")
plot(center, offset = offset, color = sllcol, title = "SL Long")
plot(center, offset = offset, color = slscol, title = "SL Short")
plot(l, offset = offset, color = pcscol, title = "Channel Low")
plot(tps, offset = offset, color = tpscol, title = "TP Short")

//Background
size = strategy.position_size
bgcol = showbg == false ? na : size > 0 ? color.lime : size < 0 ? color.red : na
bgcolor(bgcol, transp = 70)

//Lot size
risksizelong = -1 * risklong
risklonga = ((center / h) - 1) * 100
coeflong = abs(risksizelong / risklonga)
lotlong = (strategy.equity / close) * coeflong
risksizeshort = -1 * riskshort
riskshorta = ((center / l) - 1) * 100
coefshort = abs(risksizeshort / riskshorta)
lotshort = (strategy.equity / close) * coefshort

//Trading
truetime = time > timestamp(fromyear, frommonth, fromday, 00, 00) and time < timestamp(toyear, tomonth, today, 23, 59)
mo = 0
mo := strategy.position_size != 0 ? 0 : high >= center[1] and low <= center[1] ? 1 : mo[1]

if h > 0
    longlimit = tptype == "1. None" ? na : tpl
    longstop = sltype == "1. None" ? na : center
    strategy.entry("Long", strategy.long, lotlong, stop = h, when = strategy.position_size <= 0 and needlong and truetime and mo)
    strategy.exit("TP Long", "Long", limit = longlimit, stop = longstop)
    shortlimit = tptype == "1. None" ? na : tps
    shortstop = sltype == "1. None" ? na : center
    strategy.entry("Short", strategy.short, lotshort, stop = l, when = strategy.position_size >= 0 and needshort and truetime and mo)
    strategy.exit("Exit Short", "Short", limit = shortlimit, stop = shortstop)
if time > timestamp(toyear, tomonth, today, 23, 59)
    strategy.close_all()
    strategy.cancel("Long")
    strategy.cancel("Short")

if showlabel

    //Drawdown
    max = 0.0
    max := max(strategy.equity, nz(max[1]))
    dd = (strategy.equity / max - 1) * 100
    min = 100.0
    min := min(dd, nz(min[1]))

    //Label
    min := round(min * 100) / 100
    labeltext = "Drawdown: " + tostring(min) + "%"
    var label la = na
    label.delete(la)
    tc = min > -100 ? color.white : color.red
    osx = timenow + round(change(time)*10)
osy = highest(100)Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-01. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dynamic-Price-Channel-with-Stop-Loss-Tracking-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Breakout Strategy Based on Turtle TradingPine Script · Breakout · 1d
- Contrarian Donchian Channel Touch Entry Strategy with Post Stop Loss Pause and Trailing Stop LossPine Script · Breakout · 1d
- Donchian Breakout Trading StrategyPine Script · Breakout · 1d
- Donchian Channel Breakout Strategy 426772Pine Script · Breakout · 2h
- Donchian Channel Breakout Strategy 427308Pine Script · Breakout · 3m
- Donchian Channel Breakout Strategy 440321Pine Script · Breakout · 4h