Strategy vault / Trend following
Dynamic Rising ADX Trend Following Strategy
This strategy tracks the dynamic changes of the ADX indicator to capture the early shifts in market trends for timely trend following. When ADX rises quickly from low levels, it signals a trend is forming which…
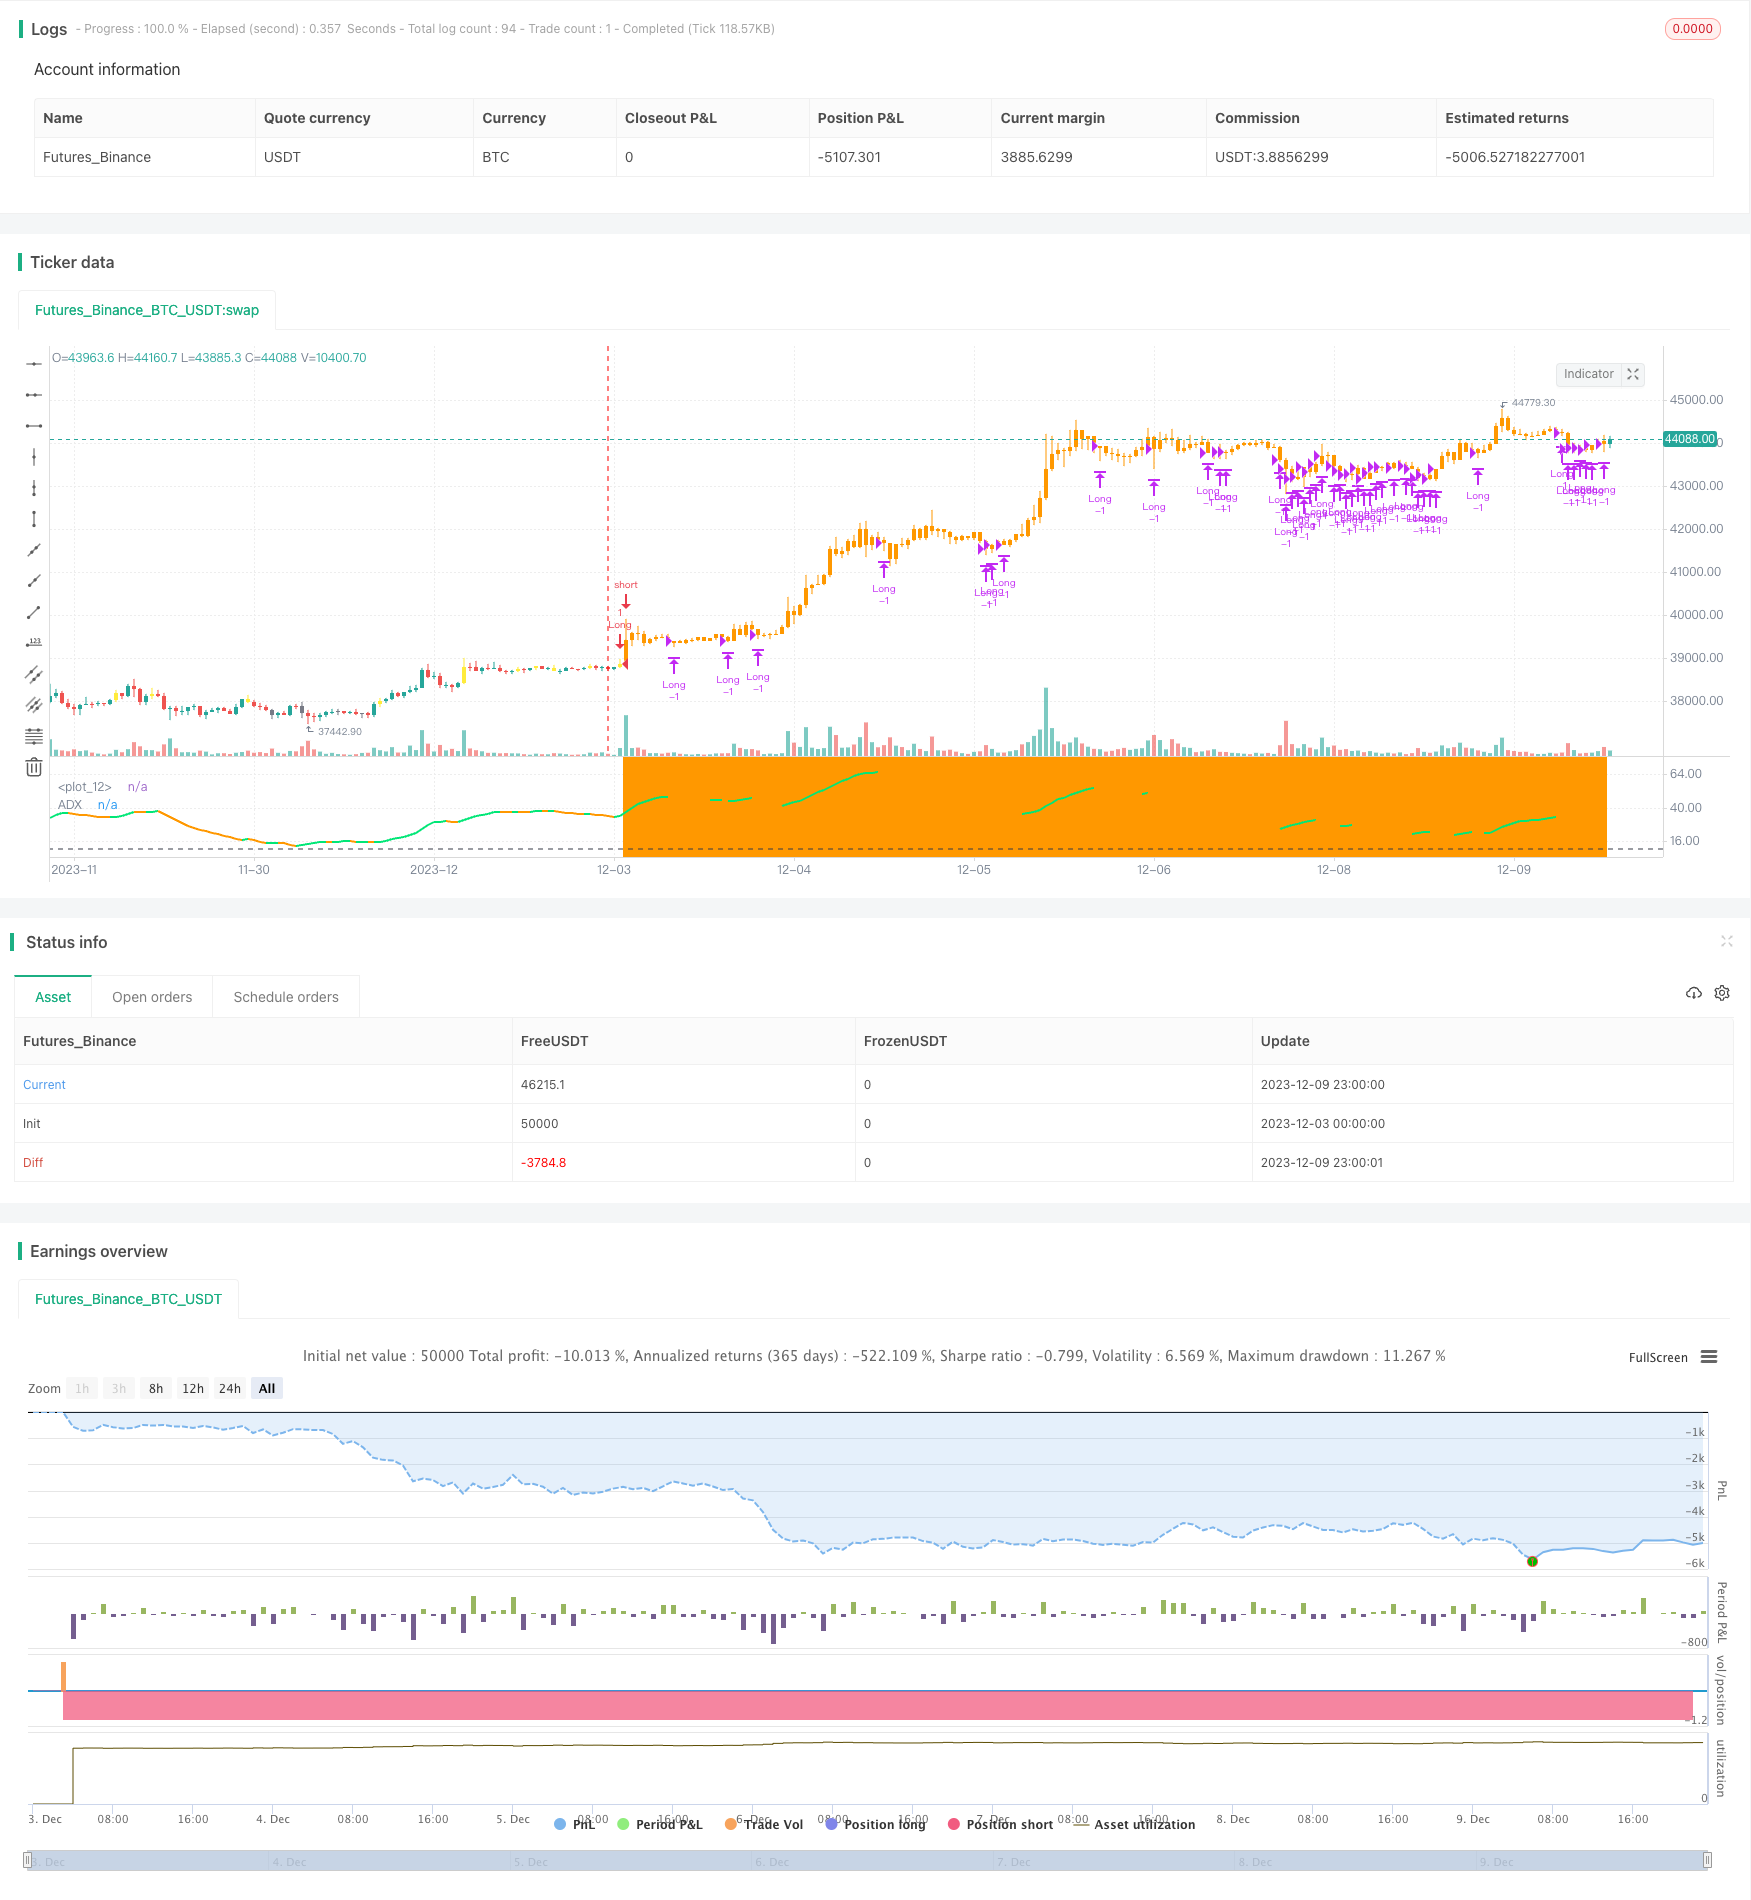
Overview
This strategy tracks the dynamic changes of the ADX indicator to capture the early shifts in market trends for timely trend following. When ADX rises quickly from low levels, it signals a trend is forming which presents a great opportunity to enter. With the assistance of moving averages, it can filter out false signals effectively.
Strategy Logic
The core of this strategy lies in judging trend development based on the dynamic changes of the ADX indicator. Low ADX signifies small fluctuations in trends. When ADX rises swiftly from low levels, it signals a trend is forming. The strategy captures trend emergence by monitoring the sharp increase of ADX.
Specifically, the entry signal consists of the following factors:
- ADX crosses above a threshold (e.g. 10)
- ADX rises swiftly upwards
- Price crosses above Simple or Exponential Moving Average
When all conditions above are met, it signals an uptrend is forming to go long. When price falls below moving averages, close positions. Two moving averages are used to judge trends more precisely.
The stop loss logic is similar. Go short when ADX drops swiftly, and close positions when price rises above moving averages.
Advantage Analysis
The biggest edge here is the timely capturing of emerging trends. The conventional way of looking at absolute ADX values often requires confirmation above 20 or 25 to call a trend, thus missing the optimal entry timing. This strategy grasps the trend's early development by tracking the swift rise of ADX.
Moreover, the moving averages help filter out false signals effectively, enhancing the stability of the strategy.
Risk and Optimization Analysis
The biggest risk comes from the lagging nature of the ADX itself. Despite catching the swift rise to reduce the lag, there is still some delay. This causes missing out on some rapidly reversing markets.
Also, ADX does not perfectly judge trends and inevitably misdiagnoses them from time to time. The moving averages filter out some noise but need further optimization.
There is still large room for optimizing this strategy, mainly enhancing ADX's accuracy in capturing trends. Methods like machine learning can be explored, training models to forecast probability distribution based on ADX changes. Other aspects like parameter tuning, additional indicators etc. can also be tested.
Conclusion
This dynamic rising ADX trend following strategy captures trend shifts swiftly by identifying sharp ADX rises, thus following trends in a timely manner. The biggest advantage is its agility in time, effectively seizing early trend developments. Meanwhile, certain risks of misjudgment remain that call for continuous optimization and testing.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 14 | ADX Length |
| v_input_2 | 10 | threshold |
| v_input_3 | 2 | 1=SMA, 2=EMA, 3=WMA, 4=HullMA |
| v_input_4 | 20 | Moving average 1 |
| v_input_5 | 2 | 1=SMA, 2=EMA, 3=WMA, 4=HullMA |
| v_input_6 | 20 | Moving average 2 |
| v_input_7 | true | Long side |
| v_input_8 | true | Short side |
Source Pine Script
/*backtest
start: 2023-12-03 00:00:00
end: 2023-12-10 00:00:00
period: 1h
basePeriod: 15m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © dhilipthegreat

//@version=4
//Rising ADX strategy

strategy(title="Rising ADX strategy", overlay=false)

adxlen = input(14, title="ADX Length", minval=1)
threshold = input(10, title="threshold", minval=5)

hline(threshold, color=color.black, linestyle=hline.style_dashed)

atype = input(2,minval=1,maxval=7,title="1=SMA, 2=EMA, 3=WMA, 4=HullMA")
malen=input(20, title="Moving average 1 ",minval=1, maxval=50)
avg = atype == 1 ? sma(close,malen) : atype == 2 ? ema(close,malen) : atype == 3 ? wma(close,malen) : atype == 4 ? hma(close,malen) : na

atype2 = input(2,minval=1,maxval=7,title="1=SMA, 2=EMA, 3=WMA, 4=HullMA")
malen2=input(20, title="Moving average 2",minval=1, maxval=200)
avg2 = atype2 == 1 ? sma(close,malen2) : atype2 == 2 ? ema(close,malen2) : atype2 == 3 ? wma(close,malen2) : atype2 == 4 ? hma(close,malen2) : na

//ADX&DI
dilen = 14
dirmov(len,_high,_low,_tr) =>
	up = change(_high)
	down = -change(_low)
	plusDM = na(up) ? na : (up > down and up > 0 ? up : 0)
    minusDM = na(down) ? na : (down > up and down > 0 ? down : 0)
	truerange = rma(_tr, len)

	plus = fixnan(100 * rma(plusDM, len) / truerange)
	minus = fixnan(100 * rma(minusDM, len) / truerange)

	[plus, minus]

adx(dilen, adxlen,_high,_low,_tr) =>
	[plus, minus] = dirmov(dilen,_high,_low,_tr)
	sum = plus + minus
	adx = 100 * rma(abs(plus - minus) / (sum == 0 ? 1 : sum), adxlen)

[plus, minus] = dirmov(dilen,high,low,tr)
sig = adx(dilen, adxlen,high,low,tr)
prev_sig = adx(dilen, adxlen,high[1],low[1],tr)
plot(sig ? sig : na, color = rising(sig, 1) ? color.lime : falling(sig, 1) ? color.orange : color.purple, title="ADX",linewidth=2)

//////
longCondition=  sig > threshold  and rising(sig, 1) and falling(prev_sig, 1) and close > avg and close > avg2
barcolor(longCondition ? color.yellow: na)
Long_side = input(true, "Long side")
if Long_side
    strategy.entry(id="Long", long=true,  when= longCondition  and strategy.position_size<1)
    exitCondition=  (rising(prev_sig, 1) and falling(sig, 1)) or close < avg and close < avg2
    strategy.close(id="Long",comment="L exit",    qty=strategy.position_size ,   when= exitCondition)   //close all

shortCondition=  sig > threshold  and rising(sig, 1) and falling(prev_sig, 1) and close < avg and close < avg2
barcolor(shortCondition ? color.gray: na)
Short_side = input(true, "Short side")
if Short_side
    strategy.entry(id="Short", long=false,  when= shortCondition  and strategy.position_size<1)
    sell_exitCondition=  (rising(prev_sig, 1) and falling(sig, 1)) or close > avg and close > avg2
    strategy.close(id="Short",comment="S exit",    qty=strategy.position_size ,   when= sell_exitCondition)   //close all

barcolor(strategy.position_size>1 ? color.lime: na)
bgcolor(strategy.position_size>1 ? color.lime: na)

barcolor(strategy.position_size<0 ? color.orange: na)
bgcolor(strategy.position_size<0 ? color.orange: na)Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-11. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dynamic-Rising-ADX-Trend-Following-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- EMA AROON ASHPine Script · Trend following · 3m
- EMA SMA Multi Indicator Comprehensive Trend Following StrategyPine Script · Trend following · 1h
- Multi Factor Trend Price Action Strategy with Dynamic Risk Management SystemPine Script · Trend following · 2h
- Multi Indicator Dynamic Trend Following Strategy Based on EMA and SMAPine Script · Trend following · 1d
- Multi Trend StrategyPine Script · Trend following · 1m