Strategy vault / Mean reversion
Dynamic RSI and CCI Combined Multi factor Quantitative Trading Strategy
This strategy combines dynamic RSI, CCI and multiple MA moving averages to implement a multi-factor driven quantitative trading strategy. The strategy takes into account multiple dimensions such as trend, overbought…
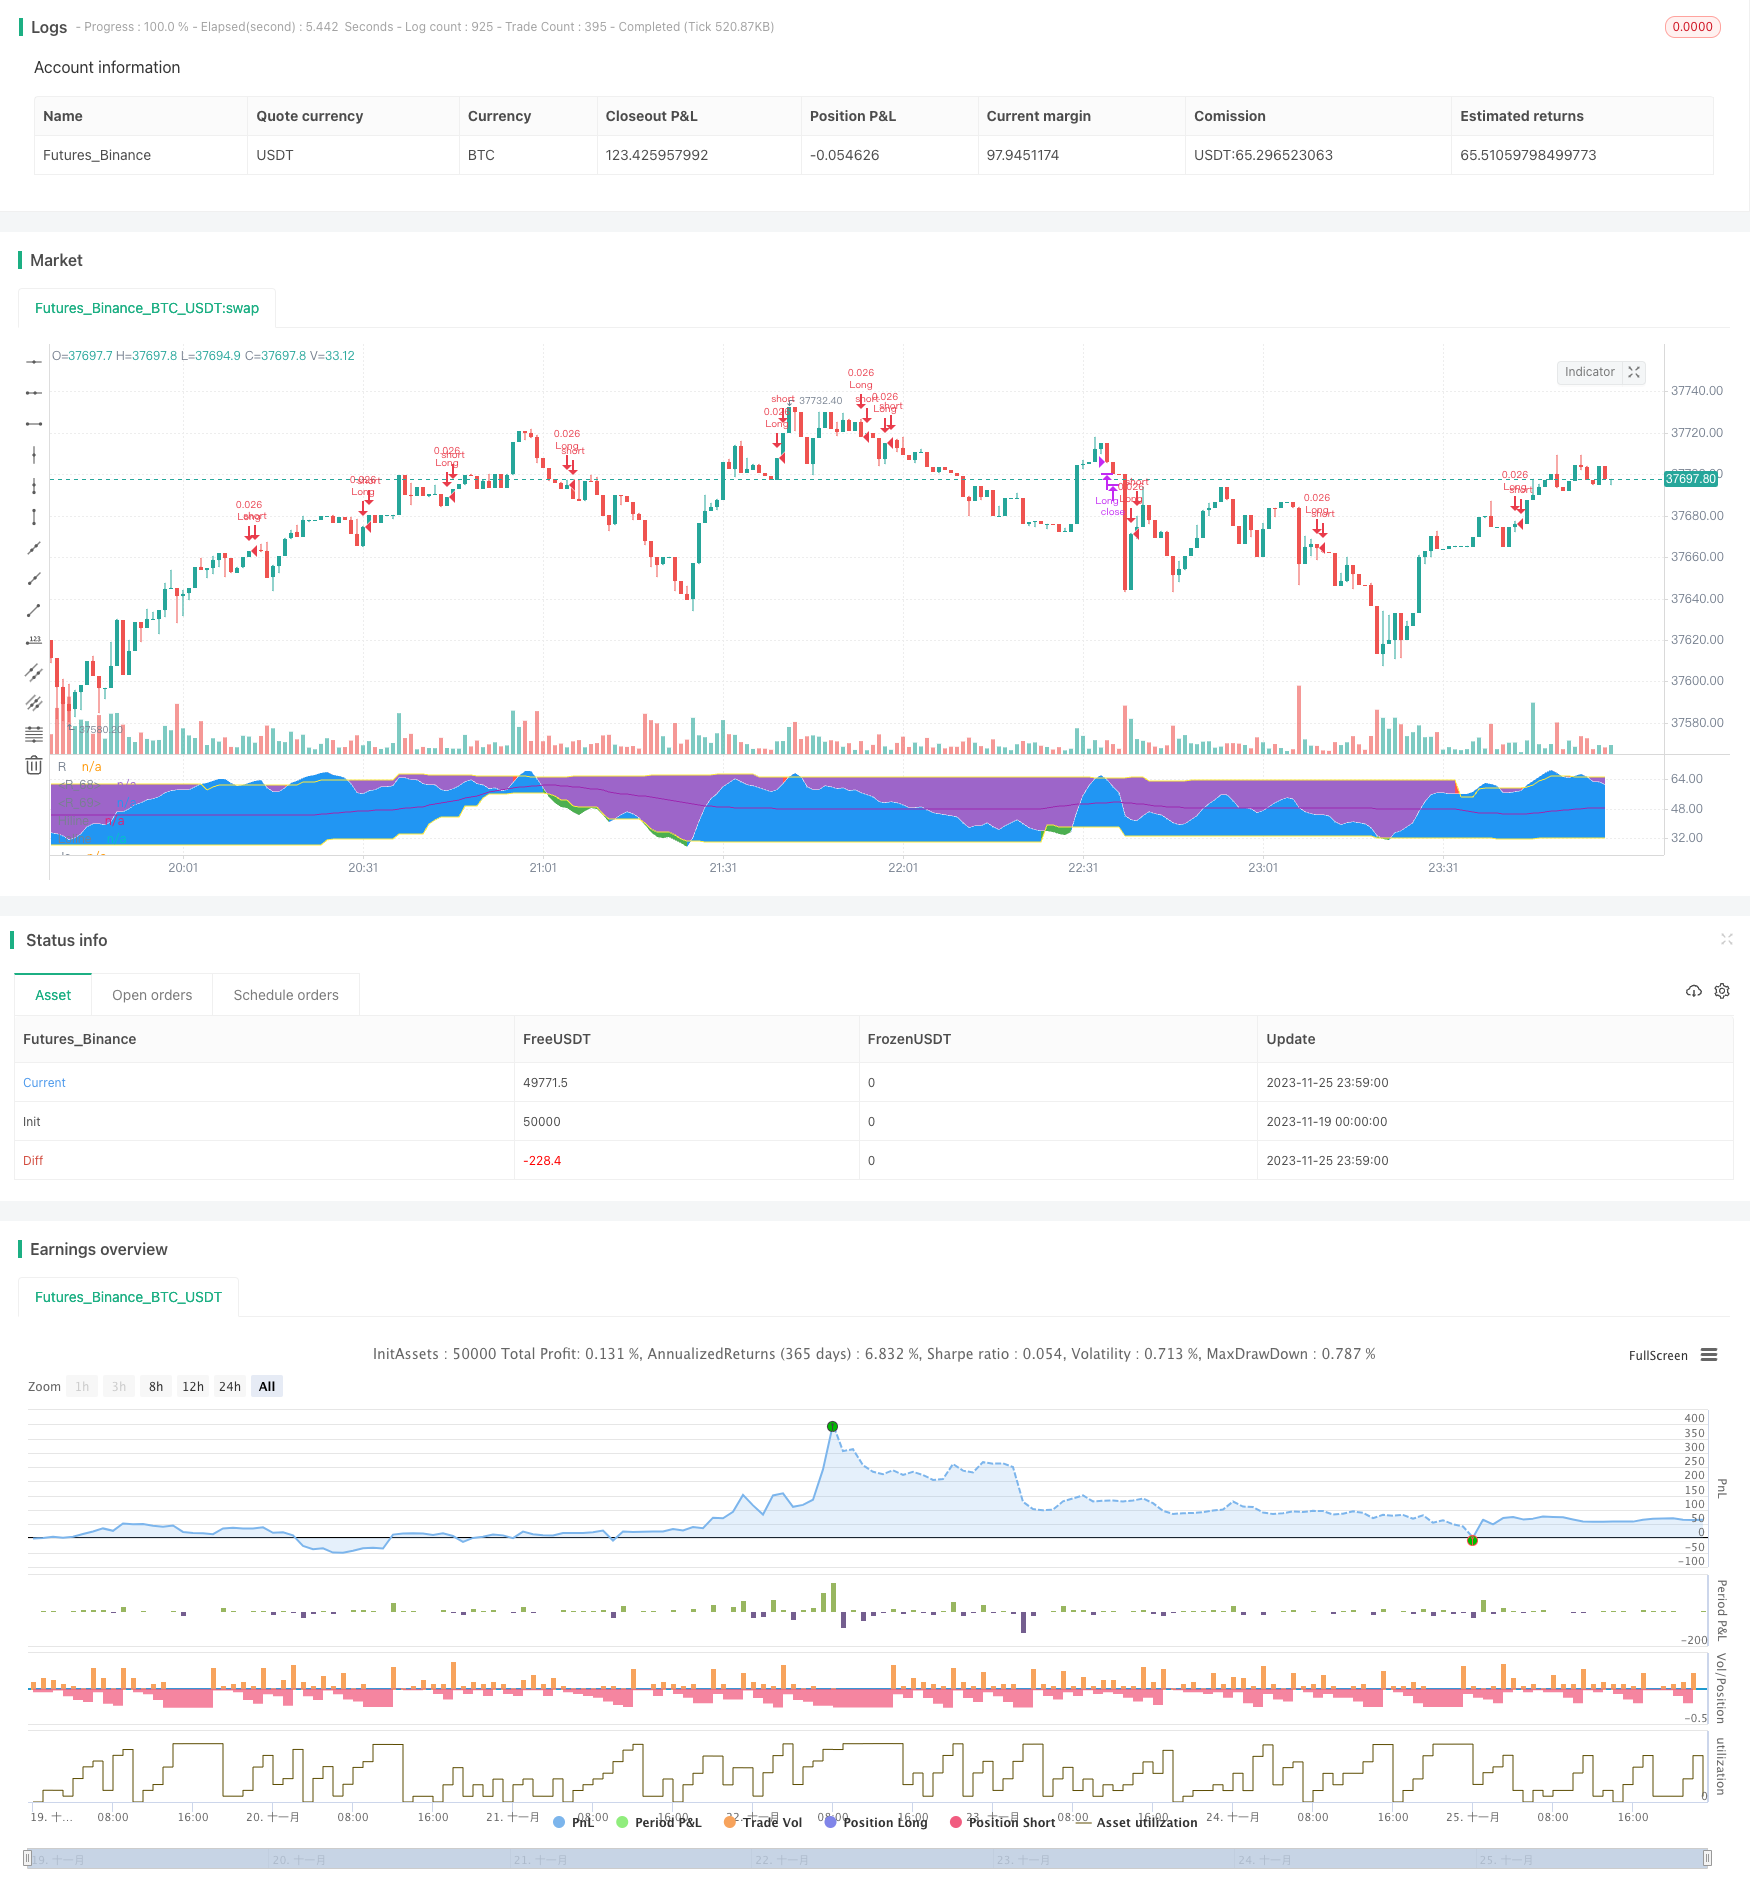
Overview
This strategy combines dynamic RSI, CCI and multiple MA moving averages to implement a multi-factor driven quantitative trading strategy. The strategy takes into account multiple dimensions such as trend, overbought and oversold to make judgments and generate trading signals.
Strategy Principle
Technical Indicators
- MA: Calculates average closing price over a period to determine price trend
- RSI: Judges overbought and oversold levels
- CCI: Judges overbought and oversold status
- Stoch KDJ: Judges deviation of stochastic from main trend
Trading Signals
Buy signal: MA12 crosses over MA26, CCI below 100 (oversold), Stoch KDJ below 80 (oversold)
Sell signal: RSI crosses below dynamic threshold, Stoch KDJ above 80 (overbought)
Advantages
- Multi-factor driven, comprehensive judgment, lower false signals
- Dynamic threshold for sellable, real-time overbought and oversold detection
- Combines trend, stochastic, mainstream technical indicators
- Adopts multiple parameter tuning, high flexibility
Risks
- Overly complex multi-factor combination, difficult parameter tuning
- Performance highly related to parameter selection
- Requires strict quantitative process for parameter optimization
- High curve fitting risk
Optimization
- More dataset testing for strategy robustness
- Multiple parameter combination testing to find optimum
- Add stop loss to reduce maximum drawdown
- Add position sizing to avoid chasing and killing
- Test adaptability across different products
Conclusion
This strategy combines multiple technical indicators and multi-factor driven judgments with parameter tuning and statistical validation to achieve good results. But higher complexity, need to prevent overfitting, and control position sizing and stop loss to reduce maximum drawdown. Can further expand strategy across products and timeframes.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 12 | Length |
| v_input_2_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_3 | 26 | Length |
| v_input_4_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_5 | 3 | smoothK_1 |
| v_input_6 | 3 | smoothD_1 |
| v_input_7 | 14 | lengthRSI |
| v_input_8 | 14 | lengthStoch |
| v_input_9_close | 0 | RSI Source_1: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_10 | 4 | smoothK_2 |
| v_input_11 | 3 | smoothD_2 |
| v_input_12 | 5 | lengthRSI_2 |
| v_input_13 | 5 | lengthStoch_2 |
| v_input_14_close | 0 | RSI Source_2: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_15 | true | buyCondition |
Source Pine Script
/*backtest
start: 2023-11-19 00:00:00
end: 2023-11-26 00:00:00
period: 1m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy(title="ATOM2.0", shorttitle="ATOM V2.0", overlay=false, default_qty_type=strategy.cash, currency=currency.USD, initial_capital=200, default_qty_type=strategy.cash, default_qty_value=100, pyramiding=10)

// Set Parameter MA12
len12 = input(12, minval=1, title="Length")
src12 = input(close, title="Source")
ma12 = sma(src12, len12)
//plot(ma12, color=color.blue, title="MA12")

// Set Parameter MA26
len26 = input(26, minval=1, title="Length")
src26 = input(close, title="Source")
ma26 = sma(src26, len26)
//plot(ma26, color=color.orange, title="MA12")

//Stochastic RSI 14,3,3
smoothK_1 = input(3, minval=1)
smoothD_1 = input(3, minval=1)
lengthRSI = input(14, minval=1)
lengthStoch = input(14, minval=1)
src_1 = input(close, title="RSI Source_1")

rsi1 = rsi(src_1, lengthRSI)
k = sma(stoch(rsi1, rsi1, rsi1, lengthStoch), smoothK_1)
d = sma(k, smoothD_1)
//plot(k, color=color.red)
//plot(d, color=color.yellow)

//Stochastic RSI 5,4,3
smoothK_2 = input(4, minval=1)
smoothD_2 = input(3, minval=1)
lengthRSI_2 = input(5, minval=1)
lengthStoch_2 = input(5, minval=1)
src_2 = input(close, title="RSI Source_2")

rsi2 = rsi(src_2, lengthRSI_2)
k_2 = sma(stoch(rsi2, rsi2, rsi2, lengthStoch_2), smoothK_2)
d_2 = sma(k_2, smoothD_2)
//plot(k_2, color=color.white)
//plot(d_2, color=color.green)

// CCI
cci = cci(close,26)
//plot(cci,color=color.blue)

// Dynamic RSI
DZbuy = 0.1
DZsell = 0.1
Period = 14
Lb = 60

RSILine = rsi(close,Period)
jh = highest(RSILine, Lb)
jl = lowest(RSILine, Lb)
jc = (wma((jh-jl)*0.5,Period) + wma(jl,Period))
Hiline = jh - jc * DZbuy
Loline = jl + jc * DZsell
R = (4 * RSILine + 3 * RSILine[1] + 2 * RSILine[2] + RSILine[3] ) / 10

plot(R, title='R', color=color.white, linewidth=1, transp=0)
plot(Hiline, title='Hiline', color=color.yellow,  linewidth=1, transp=0)
plot(Loline, title='Loline', color=color.yellow, linewidth=1, transp=0)
plot(jc, title='Jc', color=color.purple,  linewidth=1, transp=50)

col_1 = R > Hiline ? color.red:na
col_2 = R < Loline ? color.green:na

fill(plot(R, title='R', color=color.white, linewidth=1, transp=0), plot(Hiline, title='Hiline', color=color.yellow,  linewidth=1, transp=0), color=col_1,transp=0)
fill(plot(R, title='R', color=color.white, linewidth=1, transp=0), plot(Loline, title='Loline', color=color.yellow, linewidth=1, transp=0), color=col_2,transp=0)
//------------------------------------------------------------------------------
// Calculate qty
// Parameter
fund = 10           // Fund per Contract in USD
leverage = 100     // Leverage
// Buy Condition
buyCondition = (ma12>ma26 and cci<100 and k<80 and d<80 and k_2<80 and d_2<80 and crossover(k_2, d_2))
buy = (buyCondition == input(1))
alertcondition(buy, title='time to Long', message='Long!!!')
//closeBuy = (cci>100 and cci<cci[1] and cci<cci[2])
closeBuy = (crossunder(R, Hiline) and k>80)
alertcondition(closeBuy, title='Time to Close', message='Close Long')

// Submit Orders
strategy.entry(id="Long", qty=(fund*leverage)/close, long=true, when=buyCondition)
strategy.close(id="Long", when=closeBuy)Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-27. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dynamic-RSI-and-CCI-Combined-Multi-factor-Quantitative-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Multi Indicator Scoring Trading StrategyPine Script · Mean reversion · 1d
- Rainbow OscillatorPine Script · Mean reversion · 1h
- A Momentum Tracking Mean Reversion StrategyPine Script · Mean reversion · 1h
- Advanced 15 Minute Chart Trading Signal StrategyPine Script · Mean reversion · 3h
- Bollinger Bands Stochastic RSI Extreme Strategy BBSR Extreme StrategyPine Script · Mean reversion · 1h
- BuySell Strategy depends on AOStochRSIATRPine Script · Mean reversion · 30m