Strategy vault / Trend following
Dynamic Trailing Stop Optimization Strategy Based on Ichimoku Cloud
The core idea of this strategy is to combine the Ichimoku Cloud strategy and dynamic trailing stop mechanism to achieve more efficient stop loss exits. The Ichimoku Cloud strategy judges market trends and timing…
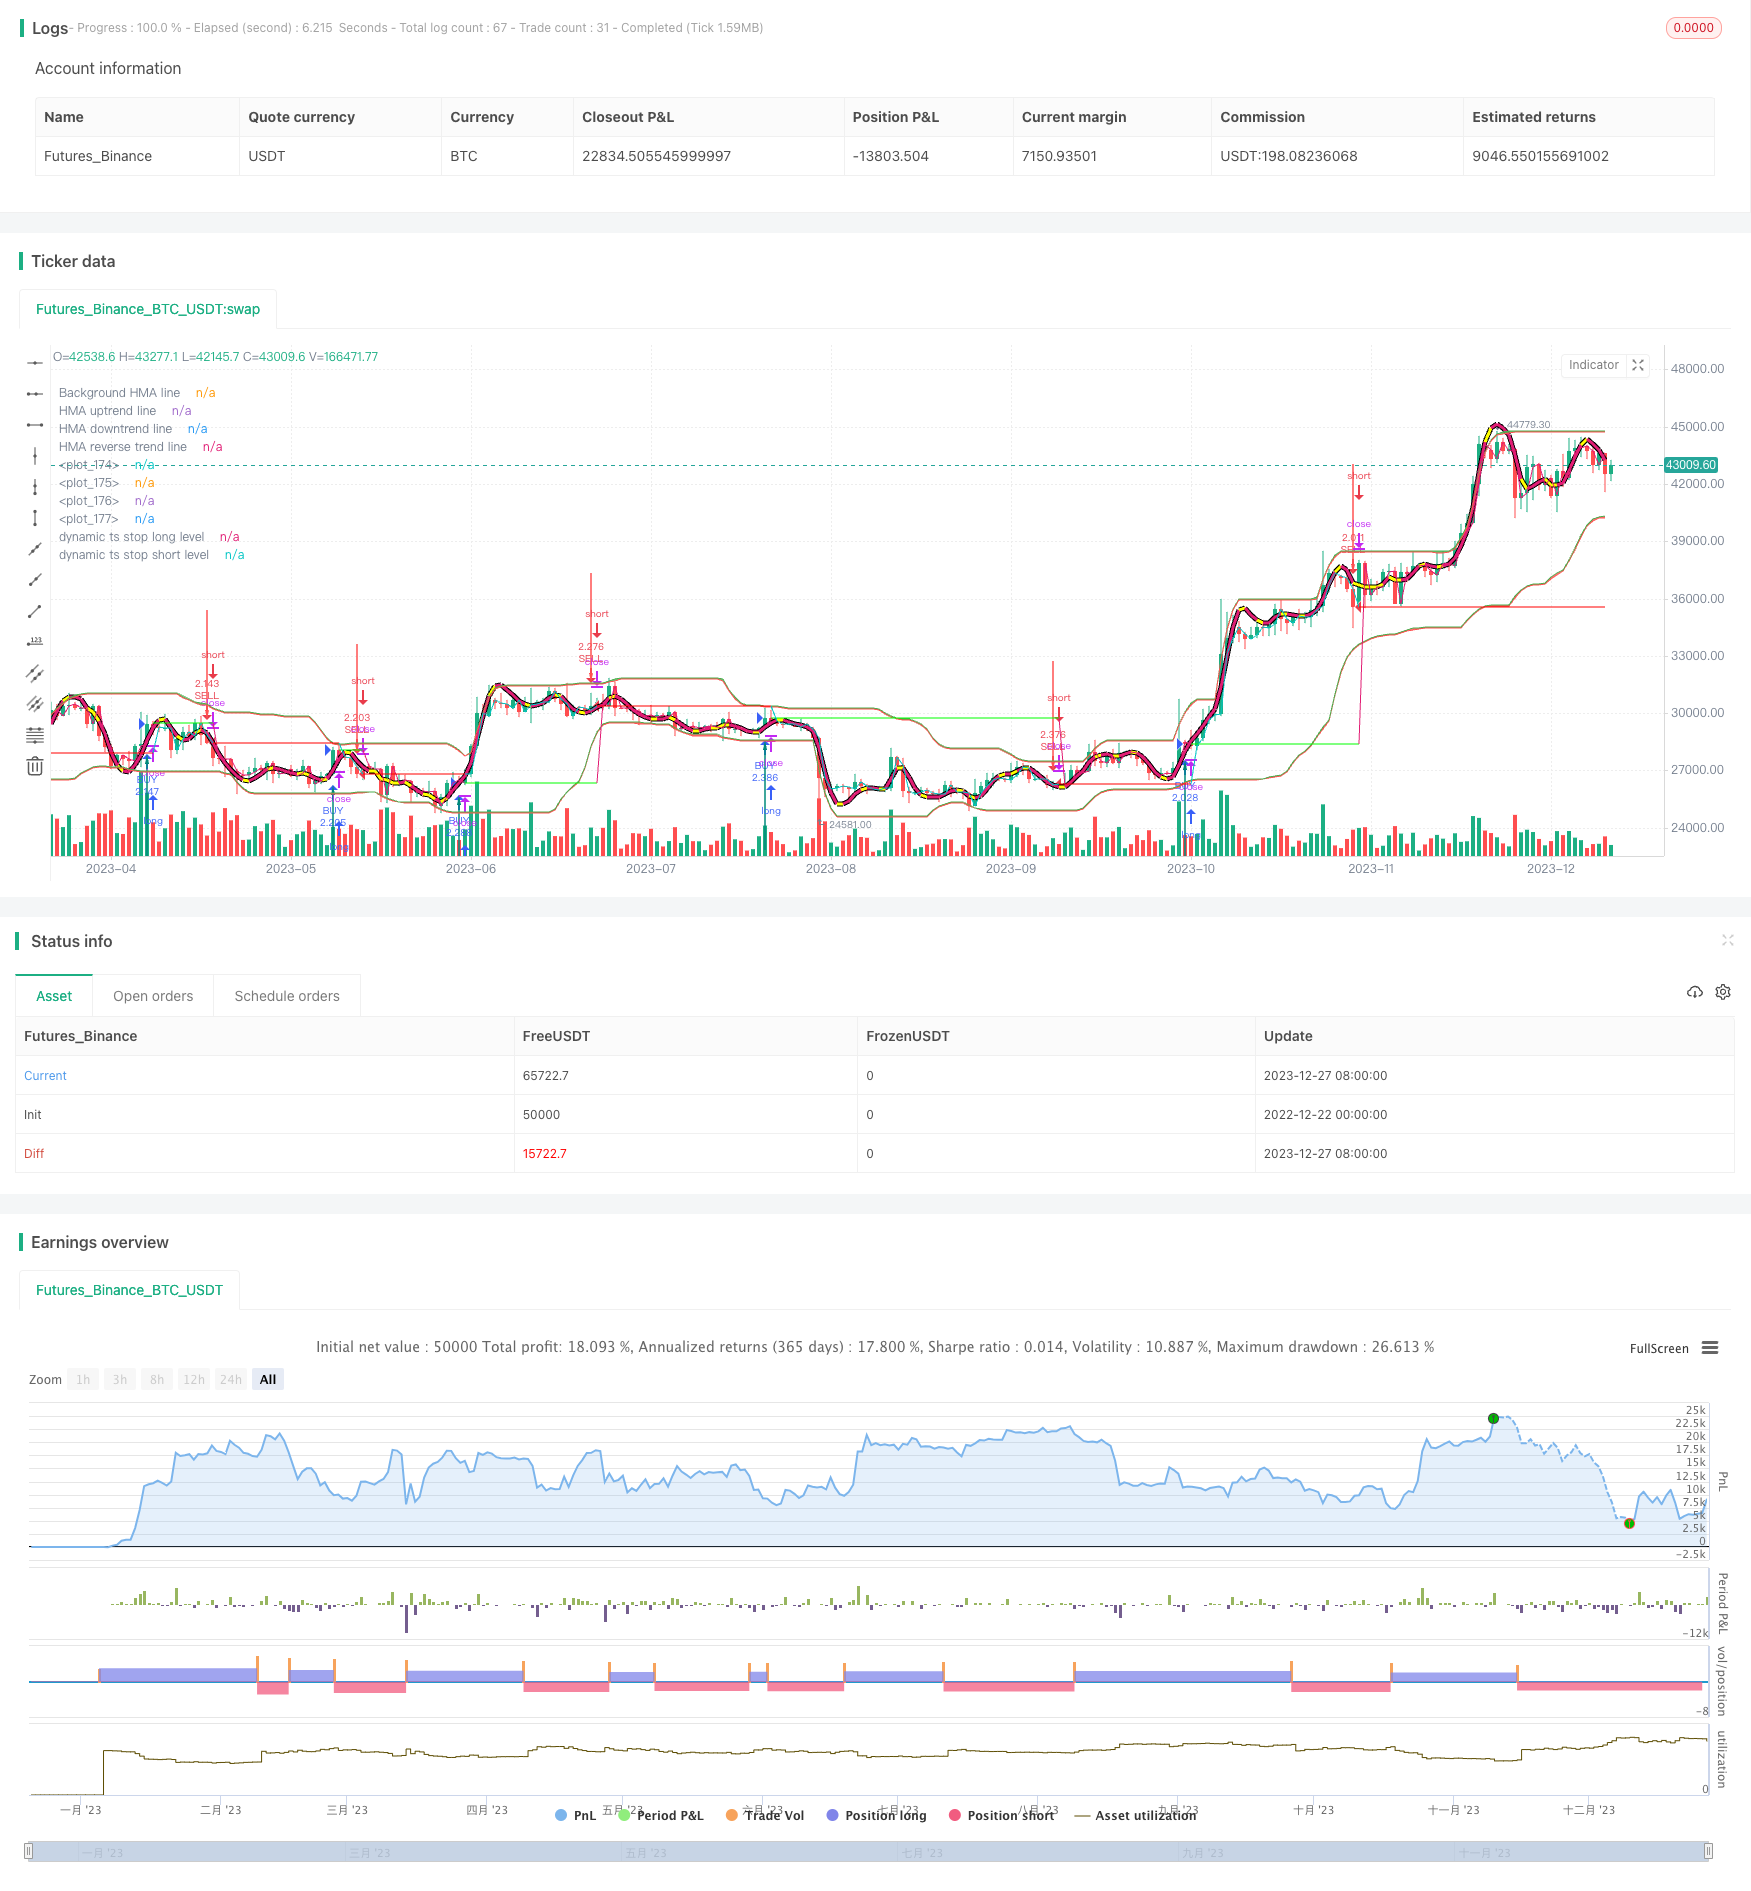
Overview
The core idea of this strategy is to combine the Ichimoku Cloud strategy and dynamic trailing stop mechanism to achieve more efficient stop loss exits. The Ichimoku Cloud strategy judges market trends and timing through K-line indicators. While the dynamic stop loss mechanism can set stop loss points based on market volatility amplitude to effectively control risks.
Principles
The main modules of this strategy include:
Ichimoku Cloud Indicator Module
Calculate the Ichimoku Cloud indicator through Fisher Transform and Stoch to determine market trends and trading signals.
Dynamic Stop Loss Module
Dynamically calculate stop loss points based on ATR and RSI to achieve dynamic trailing stop loss.
Trailing Stop Tracking Module
Set fixed trailing stop loss points. Exit positions when price reaches stop loss points.
Advantage Analysis
The biggest advantage of this strategy is the excellent risk control capability. The dynamic stop loss mechanism can set appropriate stop loss range based on market volatility to effectively avoid losses caused by excessive slippage and better track trends than fixed stop loss. In addition, the Ichimoku Cloud indicator can filter out some noisy trades and determine entry and exit points reliably.
Risk Analysis
The main risks of this strategy are improper stop loss point setting may cause excessively aggressive exits. Also, using over aggressive parameters may cause over frequent whipsaw trades. To mitigate these risks, parameters should be set reasonably to avoid excessive moving magnitude.
Optimization Directions
The optimization space of this strategy mainly focuses on:
Ichimoku Cloud parameter optimization to find better parameter combinations to determine trends.
Dynamic stop loss parameter optimization to find more balanced stop loss range.
Add volatility-based position sizing module to adjust positions based on market volatility.
Through parameter search and rules optimization, higher risk adjusted returns can be obtained from this strategy.
Conclusion
This strategy combines Ichimoku Cloud and dynamic trailing stop techniques, which can accurately determine market trends for timing decisions, and also dynamically adjusts stop loss range to effectively control risks. With continuous module expansion and parameter optimization, this strategy can become an effective long-term strategy framework.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 19 | Stoch & ATR Length |
| v_input_2 | 4 | Smooth |
| v_input_3 | 82.05 | UP line |
| v_input_4 | 19 | DOWN line |
| v_input_5 | true | Use trailing stop |
| v_input_6 | false | Re-enter after trailing stop |
| v_input_7 | 245 | trailing stop actiation pips |
| v_input_8 | 20 | trailing stop offset pips |
| v_input_9 | true | Use dynamic trailing stop start |
| v_input_10 | 68.3 | Multiplier for Dynamic TS start X*ATR |
| v_input_11 | true | Use dynamic trailing stop offset |
| v_input_12 | true | Multiplier for Dynamic TS offset X*ATR |
| v_input_13 | true | Occurancy for dynamic TS |
| v_input_14 | true | Use Current Chart Resolution? |
| v_input_15 | 30 | Timeframe |
| v_input_16 | true | Plot Hull MA |
| v_input_17 | true | Plot all |
Source Pine Script
/*backtest
start: 2022-12-22 00:00:00
end: 2023-12-28 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4
strategy("IFTS+TS Strategy Overlay ", overlay=true, pyramiding = 0, calc_on_order_fills = false, commission_type =  strategy.commission.percent, commission_value = 0.0454, default_qty_type = strategy.percent_of_equity, default_qty_value = 100)

//INPUTS
stochlength=input(19, "Stoch & ATR Length")
wmalength=input(4, title="Smooth")
ul = input(82.05,step=0.01, title="UP line")
dl = input(19,step=0.01, title="DOWN line")
uts = input(true, title="Use trailing stop")
rts = input(false, title="Re-enter after trailing stop")
tsi = input(title="trailing stop actiation pips",defval=245)
tso = input(title="trailing stop offset pips",defval=20)
udts = input(true, title="Use dynamic trailing stop start")
mpl2 = input(68.3,step=0.05, title="Multiplier for Dynamic TS start X*ATR")
udto = input(true, title="Use dynamic trailing stop offset")
mpl = input(1,step=0.01, title="Multiplier for Dynamic TS offset X*ATR")
occ = input(1, title="Occurancy for dynamic TS")
useCurrentRes = input(true, title="Use Current Chart Resolution?")
resCustom = input(title="Timeframe",defval="30")
hma = input(title="Plot Hull MA", defval=true)
pl = input(title="Plot all", defval=true)

//CALCULATIONS
v1=0.1*(stoch(close, high, low, stochlength)-50)
v2=wma(v1, wmalength)
k1=(exp(2*v2)-1)/(exp(2*v2)+1)*50+50
res = useCurrentRes ? timeframe.period : resCustom
k=security(syminfo.tickerid, res, k1, barmerge.lookahead_off)

//CALCULATIONS HULL MA
n=stochlength/2
n2ma=2*wma(close,round(n/2))
nma=wma(close,n)
diff=n2ma-nma
sqn=round(sqrt(n))
n2ma1=2*wma(close[1],round(n/2))
nma1=wma(close[1],n)
diff1=n2ma1-nma1
sqn1=round(sqrt(n))
n1=wma(diff,sqn)
n2=wma(diff1,sqn)
n3=n1-(n1*-1)
n4=n1+(n1)

//CALCULATIONS FOR BUY/SELL LEVELS
//stc=(stoch(close, high, low, stochlength))

//v3=0.1*(stoch(low, low, low, stochlength)-50)
//v4=wma(v3, wmalength)
//k3=(exp(2*v4)-1)/(exp(2*v4)+1)*50+50
//k2=security(syminfo.tickerid, res, k3, barmerge.lookahead_off)
//stl=(stoch(low, low, low, stochlength))

//v5=0.1*(stoch(high, high, high, stochlength)-50)
//v6=wma(v5, wmalength)
//k5=(exp(2*v6)-1)/(exp(2*v6)+1)*50+50
//k4=security(syminfo.tickerid, res, k5, barmerge.lookahead_off)
//sth=(stoch(high, high, high, stochlength))

//difc=k-stc
//difl=k2-stl+difc
//difh=k4-sth+difc

hg1=wma(highest(stochlength),wmalength)//-highest(stochlength)*(difh/10000)
hg=security(syminfo.tickerid, res, hg1, barmerge.lookahead_off)
hgob=hg-hg*((100-ul)/10000)
lw1=wma(lowest(stochlength),wmalength)//-lowest(stochlength)*(difl/10000)
lw=security(syminfo.tickerid, res, lw1, barmerge.lookahead_off)
lwos=lw+lw*(dl/10000)

////CONDITIONS CROSS
sell = crossunder(k,ul)? 1 : 0
buy = crossover(k,dl)? 1 : 0

////COUNT BARCOLORS
var countred = 0
if sell == 1
    countred := 1
if buy == 1
    countred := 0

var countgreen = 0
if buy == 1
    countgreen := 1
if sell == 1
    countgreen := 0

////CONDITIONS COUNT BARCOLORS
long=countgreen[1]==0 and countgreen==1 ? 1 : 0
short=countred[1]==0 and countred==1 ? 1 : 0

////COLORS
//STOCH
col = k>=k[1] ? color.aqua : color.red
col1 = countred[2]==1 ? na : #00FF00
col2 = countgreen[2]==1 ? na : #FF0000
col3 = countred[2]==1 ? na : color.yellow
col4 = countgreen[2]==1 ? na : color.yellow
//HMA
dif = n1[1]-n3
dif1 = dif>dif[1] and dif[1]>dif[2] ? na: #00FF00 //uptrend - green
dif3 = n4-n1[1]
dif2 = dif3>dif3[1] and dif3[1]>dif3[2] ? na: #FF0000  //downtrend - red
dif4 = (dif>dif[1] and dif[1]>dif[2]) == (dif3>dif3[1] and dif3[1]>dif3[2]) ? #FFFF00: na //trend change - yellow

////PLOTS CALCULATIONS DYNAMIC TS
dtso1 = sma(atr(stochlength),2)*100
dtso=security(syminfo.tickerid, "1", dtso1,barmerge.lookahead_on)*mpl
dtsi = rsi(atr(stochlength),stochlength)/mpl2*tsi
dtsiv = valuewhen(long or short, dtsi, occ)
dtsov = valuewhen(long or short, dtso, occ)
//DYNAMIC TS START
dtsil1 = countred[2]==1 and pl and uts and udts? open+(dtsiv/100) : na
dtsis1 = countgreen[2]==1 and pl and uts and udts? open-(dtsiv/100) : na
dtsil = countred[2]==1 and pl and uts and udts? open+(dtsiv/100) : fixnan(dtsil1[1])
dtsis = countgreen[2]==1 and pl and uts and udts? open-(dtsiv/100) : fixnan(dtsis1[1])
//DYNAMIC TS OFFSET+START
dtsol1 = countred[2]==1 and pl and uts and udto? dtsil-(dtsov/100) : na
dtsos1 = countgreen[2]==1 and pl and uts and udto? dtsis+(dtsov/100) : na
dtsol = countred[2]==1 and pl and uts and udto? dtsil-(dtsov/100) : fixnan(dtsol1[1])
dtsos = countgreen[2]==1 and pl and uts and udto? dtsis+(dtsov/100) : fixnan(dtsos1[1])
//CONST TS START
tsil1 = countred[2]==1 and pl and uts and not udts? open+(tsi/100) : na
tsis1 = countgreen[2]==1 and pl and uts and not udts? open-(tsi/100) : na
tsil = countred[2]==1 and pl and uts and not udts? open+(tsi/100) : fixnan(tsil1[1])
tsis = countgreen[2]==1 and pl and uts and not udts? open-(tsi/100) : fixnan(tsis1[1])
//CONST TS START + DYNAMIC TS OFFSET
tsol21 = countred[2]==1 and pl and uts and not udts and udto? open+(tsi/100)-(dtsov/100) : na
tsos21 = countgreen[2]==1 and pl and uts and not udts and udto? open-(tsi/100)+(dtsov/100) : na
tsol2 = countred[2]==1 and pl and uts and not udts and udto? open+(tsi/100)-(dtsov/100) : fixnan(tsol21[1])
tsos2 = countgreen[2]==1 and pl and uts and not udts and udto? open-(tsi/100)+(dtsov/100) : fixnan(tsos21[1])
//CONST TS OFFSET
tsol1 = countred[2]==1 and pl and uts and not udto? tsil-(tso/100) : na
tsos1 = countgreen[2]==1 and pl and uts and not udto? tsis+(tso/100) : na
tsol = countred[2]==1 and pl and uts and not udto? tsil-(tso/100) : fixnan(tsol1[1])
tsos = countgreen[2]==1 and pl and uts and not udto? tsis+(tso/100) : fixnan(tsos1[1])

//////PLOTS
////LABELS
//TS LABELS
// ltsos = (short==1) and udto and pl? label.new(bar_index, high[1]+close*0.006,  text="os "+tostring(round(dtsov)), color=color.white, size=size.small) : na
// ltsol = (long==1) and udto and pl? label.new(bar_index, low[1]-close*0.006,  text="os "+tostring(round(dtsov)), color=color.white, size=size.small, style=label.style_labelup) : na
// ltsis = (short==1) and udts and pl? label.new(bar_index, high[1]+close*0.008, text="st "+tostring(round(dtsiv)), color=color.white, size=size.small) : na
// ltsil = (long==1) and udts and pl? label.new(bar_index, low[1]-close*0.008,  text="st "+tostring(round(dtsiv)), color=color.white, size=size.small, style=label.style_labelup) : na
//STOCH LABEL
//lk = k>ul and pl? label.new(bar_index, high, text=tostring(round(k)), color=col, size=size.small) :na
//lk2 = k<dl and pl? label.new(bar_index, high, text=tostring(round(k)), color=col, size=size.small) :na
//lk3 = k>dl and k<ul and pl? label.new(bar_index, high, text=tostring(round(k)), color=color.white, size=size.small) :na
//label.delete(lk[1])
//label.delete(lk2[1])
//label.delete(lk3[1])

//ltson = udto==true and pl? label.new(bar_index, 75, text="os "+tostring(round(dtso)), color=color.yellow, size=size.small) :na
//label.delete(ltson[1])
//ltsin = udts==true and pl? label.new(bar_index, 0, text="st "+tostring(round(dtsi)), color=color.yellow, size=size.small) :na
//label.delete(ltsin[1])

//DYNAMIC TS LINES
plot(dtsil, color=col1, transp = 0, title = "dynamic ts stop long level")
plot(dtsis, color=col2, transp = 0, title = "dynamic ts stop short level")
plot(dtsol, color=col3, transp = 30, title = "dynamic ts offset long level")
plot(dtsos, color=col4, transp = 30, title = "dynamic ts offset short level")
plot(tsol2, color=col3, transp = 30, title = "const start + dynamic ts offset long level")
plot(tsos2, color=col4, transp = 30, title = "const start + dynamic ts offset short level")
//TS LINES
plot(tsil, color=col1, transp = 0, title = "const ts stop long level")
plot(tsis, color=col2, transp = 0, title = "const ts stop short level")
plot(tsol, color=col3, transp = 30, title = "const ts stop offset long level")
plot(tsos, color=col4, transp = 30, title = "const ts stop offset short level")
//ARROWS
plotarrow(pl==true? long : na, colorup = color.teal, transp=0, title = "buy arrow")
plotarrow(pl==true? -short : na, colordown = color.red, transp=0, title = "sell arrow")
//HIGH/LOW
p1 = plot(pl==true?hg : na, color=color.green, transp=100, editable=false)
p2 = plot(pl==true?lw : na, color=color.red, transp=100, editable=false)
p3 = plot(pl==true?lwos : na, color=color.green, linewidth=1, transp=100, editable=false)
p4 = plot(pl==true?hgob : na, color=color.red, linewidth=1, transp=100, editable=false)
fill(p1,p4, color=color.green, transp=75, title = "highest price levels")
fill(p2,p3, color=color.red, transp=75, title = "lowest price levels")
//HMA
mab=plot(hma and pl ? n1 : na,color=#000000, linewidth=5, transp=0, title = "Background HMA line") //black
ma=plot(hma and pl ? n1 : na,color=dif1, linewidth=3, transp=10, title = "HMA uptrend line") //green
ma2=plot(hma and pl ? n1 : na,color=dif2, linewidth=3, transp=20, title = "HMA downtrend line")//red
ma3=plot(hma and pl ? n1 : na,color=dif4, linewidth=3, transp=10, title = "HMA reverse trend line") //yellow
//LINES
// ldl = long[1]==1 and uts and udts? line.new(bar_index, high, bar_index, dtsil, color=#00FF00, width = 1) : na
// lds = short[1]==1 and uts and udts? line.new(bar_index, high, bar_index, dtsis, color=#FF0000, width = 1) : na
// ll = long[1]==1 and uts and not udts? line.new(bar_index, high, bar_index, tsil, color=#00FF00, width = 1) : na
// ls = short[1]==1 and uts and not udts? line.new(bar_index, high, bar_index, tsis, color=#FF0000, width = 1) : na

////STRATEGY
strategy.entry("BUY", strategy.long, when = buy)
strategy.entry("SELL", strategy.short, when = sell)

if (rts)
    strategy.entry("BUY", strategy.long, when = countgreen==1 and dif1==#00FF00)
    strategy.entry("SELL", strategy.short, when = countred==1 and dif2==#FF0000)

if  (uts)
    strategy.exit("Close BUY with TS","BUY", trail_points = tsi, trail_offset = tso)
    strategy.exit("Close SELL with TS","SELL", trail_points = tsi, trail_offset = tso)

    if  (udto)
        strategy.exit("Close BUY with TS","BUY", trail_points = tsi, trail_offset = dtsov)
        strategy.exit("Close SELL with TS","SELL", trail_points = tsi, trail_offset = dtsov)

    if  (udts)
        strategy.exit("Close BUY with TS","BUY", trail_points = dtsiv, trail_offset = tso)
        strategy.exit("Close SELL with TS","SELL", trail_points = dtsiv, trail_offset = tso)

    if  (udto and udts)
        strategy.exit("Close BUY with TS","BUY", trail_points = dtsiv, trail_offset = dtsov)
        strategy.exit("Close SELL with TS","SELL", trail_points = dtsiv, trail_offset = dtsov)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-29. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Dynamic-Trailing-Stop-Optimization-Strategy-Based-on-Ichimoku-Cloud.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Dual ATR Channel Trend Following StrategyPine Script · Trend following · 15m
- EMA200 and Stochastic RSI StrategyPine Script · Trend following · 1h
- Gaussian Channel Trend Following with Stochastic RSI Trading StrategyPine Script · Trend following · 1d
- Multi Dimensional Short Term Trend Predictor Technical Analysis and Volatility Adaptive Trading StrategyPine Script · Trend following · 1h
- Multi Indicator Trend Following with Oscillator Alert StrategyPine Script · Trend following · 2h
- Mini Pullback Supertrend StrategyPine Script · Trend following · 1h