End of Month Breakout on 200 Day Moving Average Strategy
This strategy is based on the price breakout of the 200-day moving average at month end to capture the trend direction of stock prices. A long position will be established when the price breaks through the 200-day…
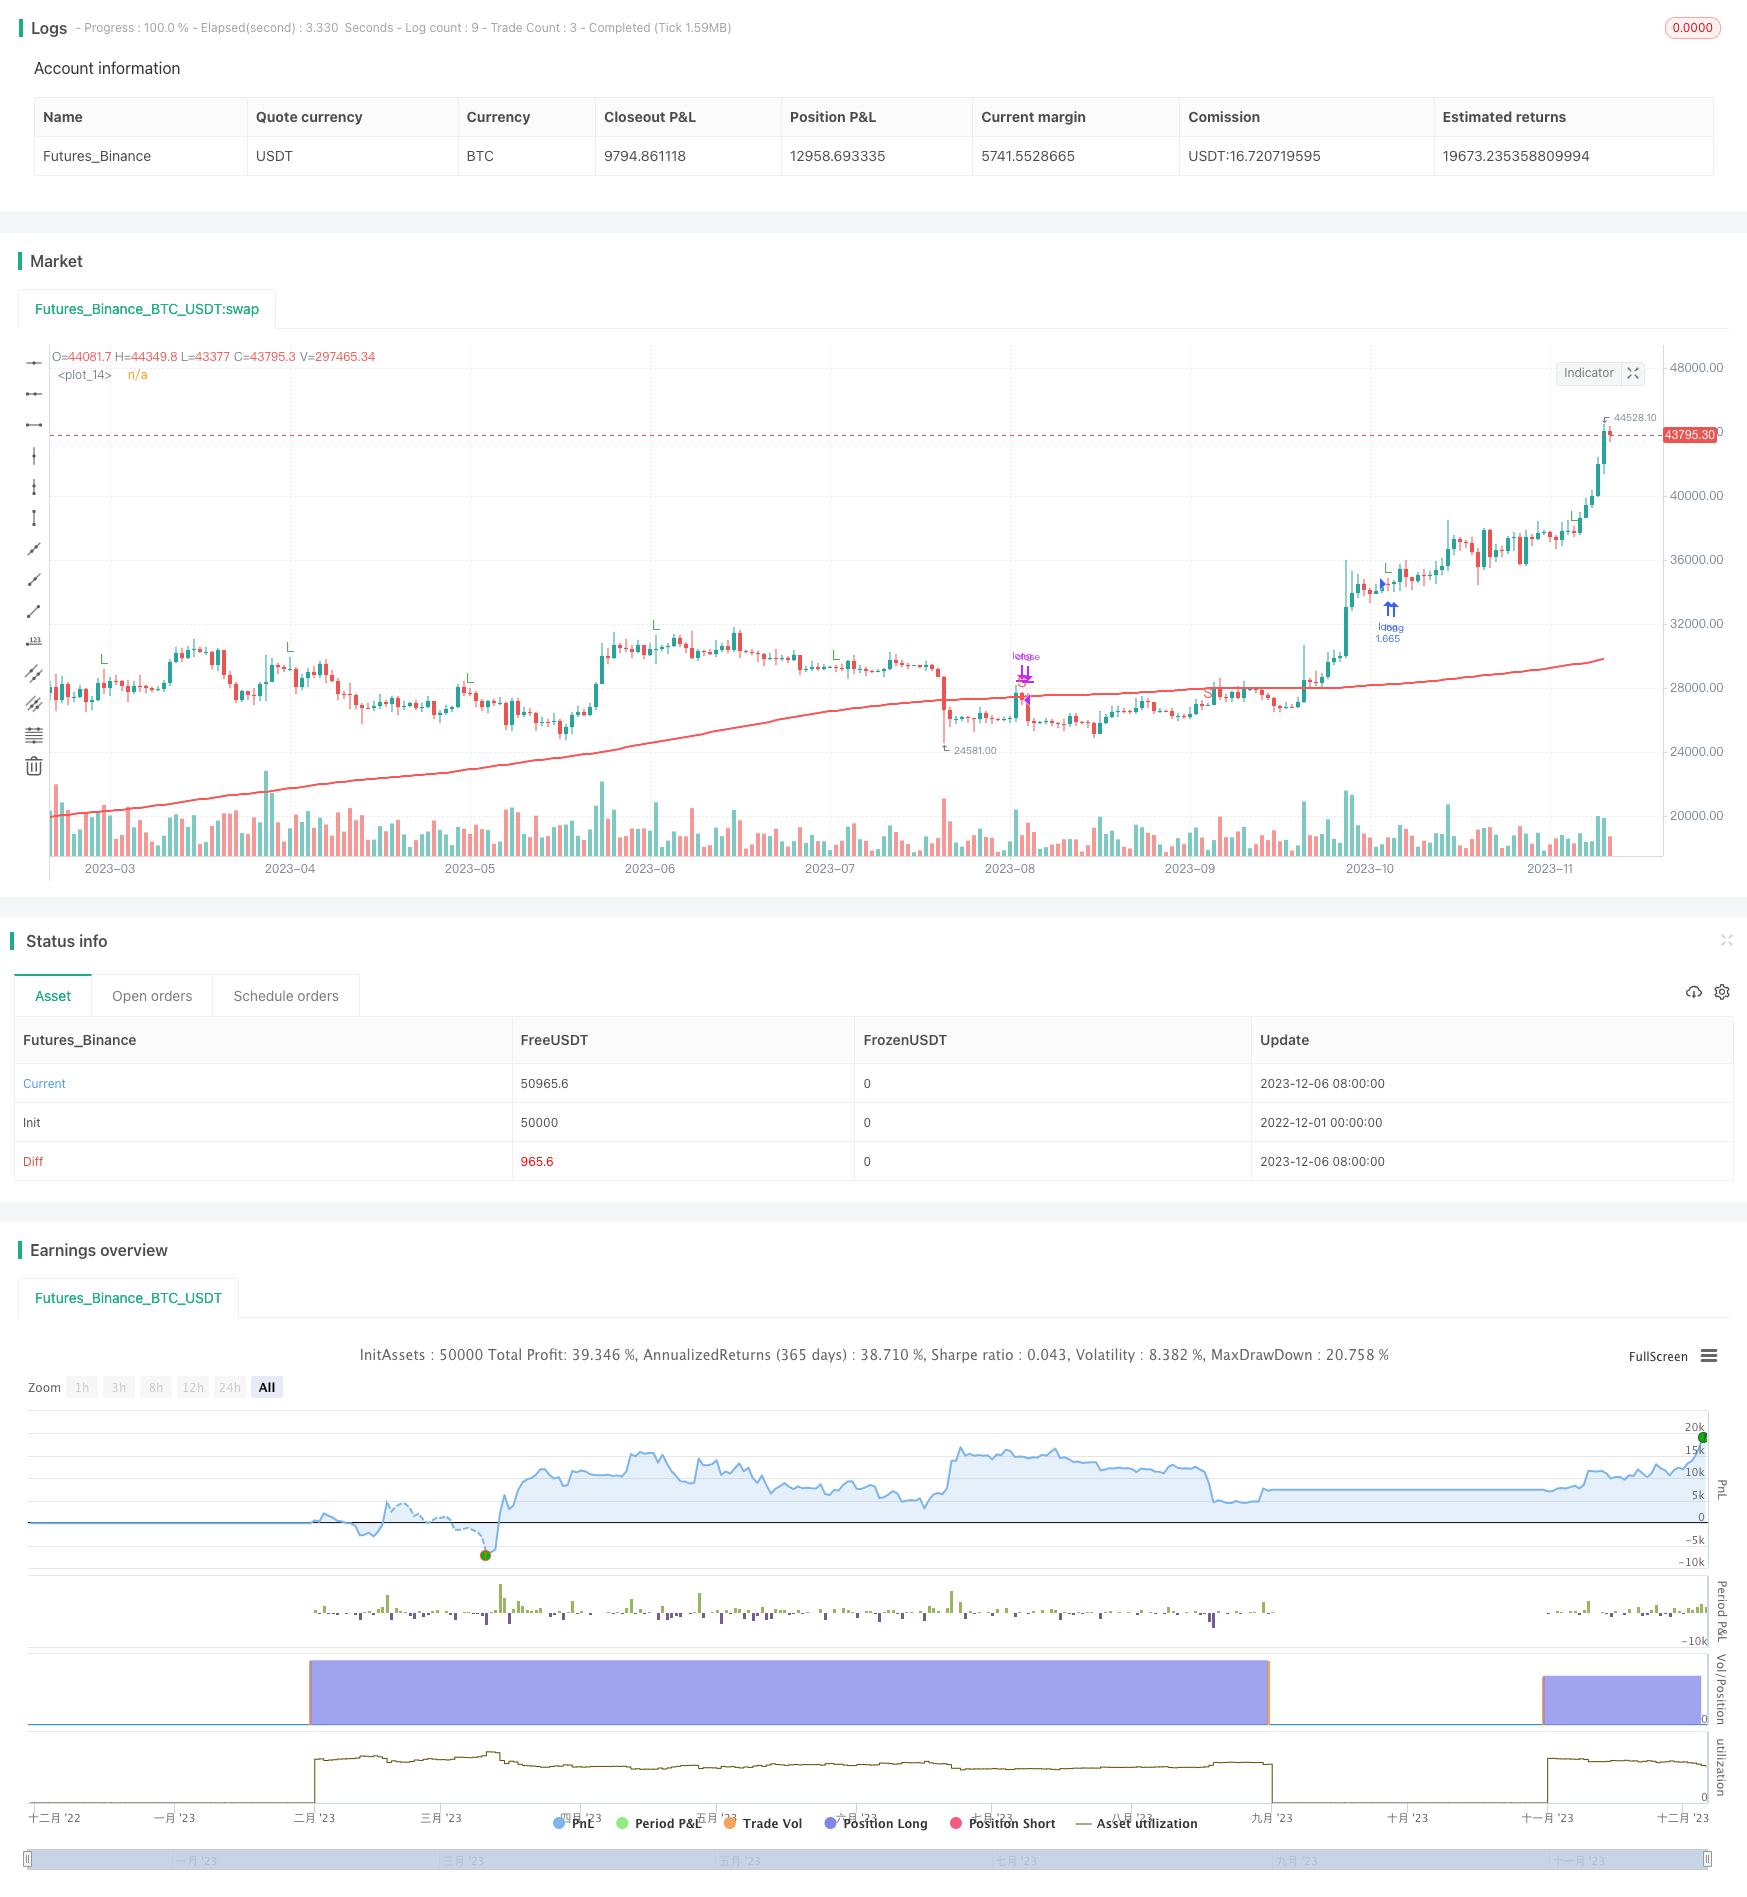
Overview
This strategy is based on the price breakout of the 200-day moving average at month end to capture the trend direction of stock prices. A long position will be established when the price breaks through the 200-day MA, otherwise the position will be cleared.
Strategy Principle
- Use the 200-day simple moving average dma200 as an indicator to judge the price trend
- On the last trading day of each month, judge whether the closing price close is higher than dma200
- If the closing price breaks through the 200-day MA, establish a full long position at the opening of next trading day
- If the closing price breaks below the 200-day MA, clear all positions at the opening of next trading day
- This can achieve the effect of trend following, establishing positions when stock prices enter an upward trend and avoiding downward trends
Advantage Analysis
- The advantage of the strategy is that it is simple and effective, easy to understand and implement
- Taking positions at month end can reduce trading frequency and minimize trading costs and slippage impacts
- The 200-day MA is a very commonly used medium and long term trend judgment indicator, effective for most stocks
- The strategy has relatively small drawdown and maximum decline, with controllable risks
Risk Analysis
- The 200-day MA may not be sensitive enough for some stocks to capture price reversals in time
- There is only 1 trading point per month for taking positions, which may miss upside/downside opportunities
- The strategy may fail to judge correctly when the overall market trend is uncertain
- Other indicators should be combined to reduce these risks
Optimization Directions
- Consider increasing trading points at beginning or middle of month to improve strategy frequency
- Add indicators like Bollinger Bands to judge price fluctuation and avoid wrong trades
- Evaluate fitting effects of different MA parameters on different stocks to find optimal parameter combinations
- Establish dynamic position sizing mechanisms to stop loss actively when drawdown gets too high
Summary
The strategy is relatively simple and practical overall, effectively capturing medium and long term price trends of stocks through month end breakout of the 200-day MA, with relatively small drawdown and risks. By combining more indicators and dynamic optimizations, the stability and profitability of the strategy can be further enhanced.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_int_1 | true | From Day |
| v_input_int_2 | true | From Month |
| v_input_int_3 | 2018 | From Year |
| v_input_int_4 | true | To Day |
| v_input_int_5 | true | To Month |
| v_input_int_6 | 9999 | To Year |
Source Pine Script
/*backtest
start: 2022-12-01 00:00:00
end: 2023-12-07 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © muscleriot
//200 dma
//2000-2016 backtested
//1 signal per month only at end of month
//If > 200DMA enter long
//If < 200DMA goto cash
//results: 318% drawdown 17% vs 125% with 55% drawdown for buy and hold
//@version=5
strategy("200DMA last DOM - ajh", overlay =true,default_qty_type=strategy.percent_of_equity, default_qty_value=100)
// Use 100% of  equity always

dma200 = ta.sma(close, 200)
plot(dma200, color=color.red, linewidth = 2)
//e =dayofmonth(time)
// backtesting date range
from_day = input.int(defval=1, title="From Day", minval=1, maxval=31)
from_month = input.int(defval=1, title="From Month", minval=1, maxval=12)
from_year = input.int(defval=2018, title="From Year", minval=1900)

to_day = input.int(defval=1, title="To Day", minval=1, maxval=31)
to_month = input.int(defval=1, title="To Month", minval=1, maxval=12)
to_year = input.int(defval=9999, title="To Year", minval=1900)

time_cond = time > timestamp(from_year, from_month, from_day, 00, 00) and
   time < timestamp(to_year, to_month, to_day, 23, 59)


xLong = dayofmonth(time) == 30 and (close > dma200) ? true : na
xSell = dayofmonth(time) == 30 and (close < dma200) ? true : na
plotchar(xLong, "long","L", color=color.green)
plotchar(xSell, "Sell","S", color=color.red)
if (xLong == true) and time_cond
    strategy.entry("long", strategy.long)
if (xSell == true) and time_cond
    strategy.close("long")
Published by ChaoZhang on the FMZ strategy square · last modified 2023-12-08. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/End-of-Month-Breakout-on-200-Day-Moving-Average-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Adaptive Bollinger Breakout with Moving Average Quantitative Strategy SystemPine Script · Breakout · 1h
- BB Breakout StrategyPine Script · Breakout · 1d
- Bollinger Band Breakout Trend Following StrategyPine Script · Breakout · 1d
- Bollinger Band Channel Breakout Trading StrategyPine Script · Breakout · 1d
- Bollinger Band T3 Moving Average StrategyPine Script · Breakout · 10m
- Bollinger Bands Breakout Trading StrategyPine Script · Breakout · 1h