Ergotic Momentum Direction Convergence Trading Strategy
The name of this strategy is Ergotic Momentum Direction Convergence Trading Strategy. It is a quantitative trading strategy designed based on the technical indicator described in William Blau's book "Momentum…
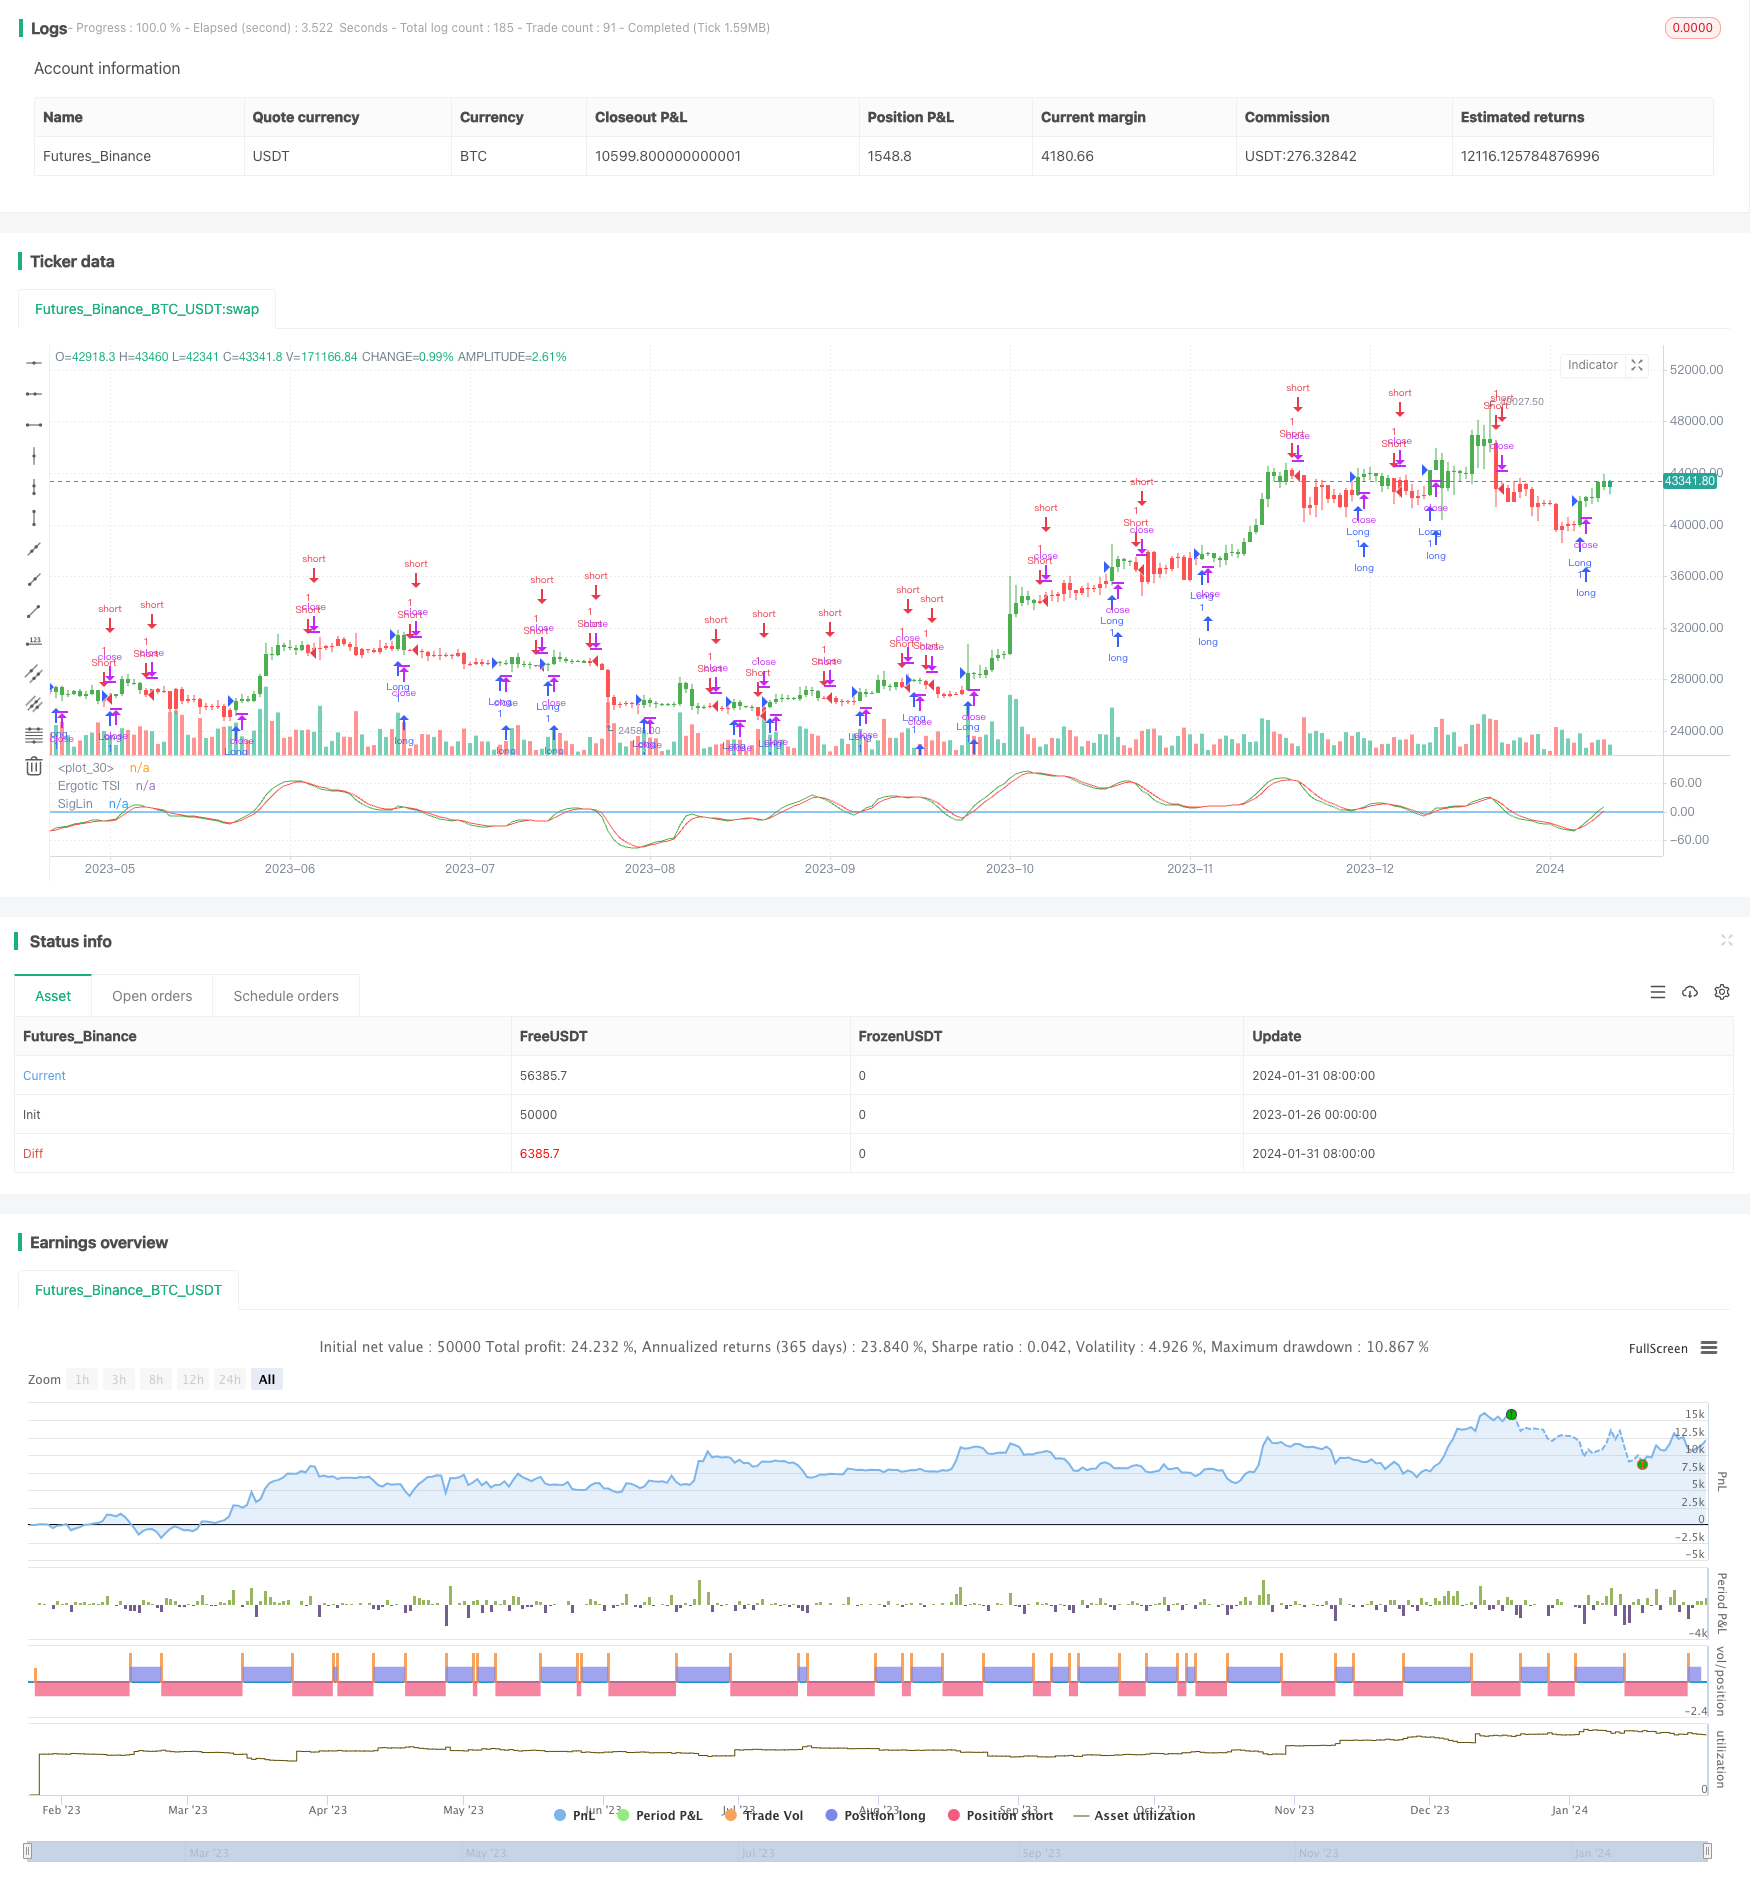
Overview
The name of this strategy is Ergotic Momentum Direction Convergence Trading Strategy. It is a quantitative trading strategy designed based on the technical indicator described in William Blau's book "Momentum, Direction and Divergence". This strategy focuses on three key aspects - momentum, direction and divergence, by calculating price momentum indicators of stocks, determining market trend direction, and finding divergences between price and indicators to spot trading opportunities.
Strategy Logic
The core indicator of this strategy is Ergotic TSI, and its calculation formula is as follows:
Val1 = 100 * EMA(EMA(EMA(price change, r), s), u)

Val2 = EMA(EMA(EMA(absolute value of price change, r), s), u))

Ergotic TSI = If Val2 != 0, Val1/Val2, else 0
where r, s, u are smoothing parameters. This indicator reflects the ratio of price change to the absolute value of price change, which belongs to the momentum oscillator indicator. Then we calculate the EMA moving average of Ergotic TSI as the signal line. Go long when TSI crosses over the signal line, and go short when it crosses below.
Advantage Analysis
The main advantages of this strategy are:
- Strong ability to capture price change trends
- Good filtering of price fluctuations
- Relatively good divergence characteristics
- Flexible parameter settings to adjust smoothing
Risk Analysis
There are also some risks in this strategy:
- Wrong signals may occur at trend reversal points
- Inappropriate parameter settings may miss trading opportunities or increase false signals
- Parameters need proper adjustment to suit different products and trading environments Risks can be controlled by optimizing parameters, combining other indicators for confirmation, and setting stop loss.
Optimization Directions
This strategy can be optimized in the following aspects:
- Test different price inputs, such as open, close, mid price, etc.
- Adjust r, s, u parameter values to find optimal parameter combinations
- Add other indicators or filters to further confirm signals
- Set stop loss points and exit mechanisms
Conclusion
This strategy integrates considerations of momentum change, trend judgment and divergence features. It can effectively capture trend opportunities. With parameter optimization, signal filtering and risk control methods, good strategy performance can be achieved. Overall, the strategy is designed reasonably and worth further research and practice.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | 4 | r |
| v_input_2 | 8 | s |
| v_input_3 | 6 | u |
| v_input_4 | 3 | SmthLen |
| v_input_5 | false | Trade reverse |
Source Pine Script
/*backtest
start: 2023-01-26 00:00:00
end: 2024-02-01 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version = 2
////////////////////////////////////////////////////////////
//  Copyright by HPotter v1.0 13/12/2016
// r - Length of first EMA smoothing of 1 day momentum        4
// s - Length of second EMA smoothing of 1 day smoothing      8
// u- Length of third EMA smoothing of 1 day momentum         6
// Length of EMA signal line                                  3
// Source of Ergotic TSI                                      Close
//
// This is one of the techniques described by William Blau in his book "Momentum,
// Direction and Divergence" (1995). If you like to learn more, we advise you to
// read this book. His book focuses on three key aspects of trading: momentum,
// direction and divergence. Blau, who was an electrical engineer before becoming
// a trader, thoroughly examines the relationship between price and momentum in
// step-by-step examples. From this grounding, he then looks at the deficiencies
// in other oscillators and introduces some innovative techniques, including a
// fresh twist on Stochastics. On directional issues, he analyzes the intricacies
// of ADX and offers a unique approach to help define trending and non-trending periods.
//
// You can use in the xPrice any series: Open, High, Low, Close, HL2, HLC3, OHLC4 and ect...
// You can change long to short in the Input Settings
// Please, use it only for learning or paper trading. Do not for real trading.
////////////////////////////////////////////////////////////
strategy(title="Ergotic TSI Strategy Backtest")
r = input(4, minval=1)
s = input(8, minval=1)
u = input(6, minval=1)
SmthLen = input(3, minval=1)
reverse = input(false, title="Trade reverse")
hline(0, color=blue, linestyle=line)
xPrice = close
xPrice1 = xPrice - xPrice[1]
xPrice2 = abs(xPrice - xPrice[1])
xSMA_R = ema(ema(ema(xPrice1,r), s),u)
xSMA_aR = ema(ema(ema(xPrice2, r), s),u)
Val1 = 100 * xSMA_R
Val2 = xSMA_aR
xTSI = iff (Val2 != 0, Val1 / Val2, 0)
xEMA_TSI = ema(xTSI, SmthLen)
pos = iff(xTSI > xEMA_TSI, 1,
	   iff(xTSI < xEMA_TSI, -1, nz(pos[1], 0)))
possig = iff(reverse and pos == 1, -1,
          iff(reverse and pos == -1, 1, pos))
if (possig == 1)
    strategy.entry("Long", strategy.long)
if (possig == -1)
    strategy.entry("Short", strategy.short)
barcolor(possig == -1 ? red: possig == 1 ? green : blue )
plot(xTSI, color=green, title="Ergotic TSI")
plot(xEMA_TSI, color=red, title="SigLin")
Published by ChaoZhang on the FMZ strategy square · last modified 2024-02-02. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Ergotic-Momentum-Direction-Convergence-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Advanced Multi Indicator Trend Following and Momentum Quantitative Trading StrategyPine Script · Momentum · 1h
- Reverse Momentum Trading StrategyPine Script · Momentum · 1h
- Momentum Trading Strategy Based on Multi factor ModelPine Script · Momentum · 1d
- Momentum Trend Following Oscillation StrategyPine Script · Momentum · 1h
- Multi Indicator Comprehensive Analysis Quantitative Trading Strategy Trend Momentum and Volatility Collaborative Prediction ModelPine Script · Momentum · 3m
- ADX Momentum Trend StrategyPine Script · Momentum · 10m