Strategy vault / Trend following
Exponential Moving Average Crossover Strategy 438485
The exponential moving average (EMA) crossover is a common trading signal. This strategy uses the crossover of a fast EMA and a slow EMA to generate trading signals. Specifically, when the fast EMA crosses above the…
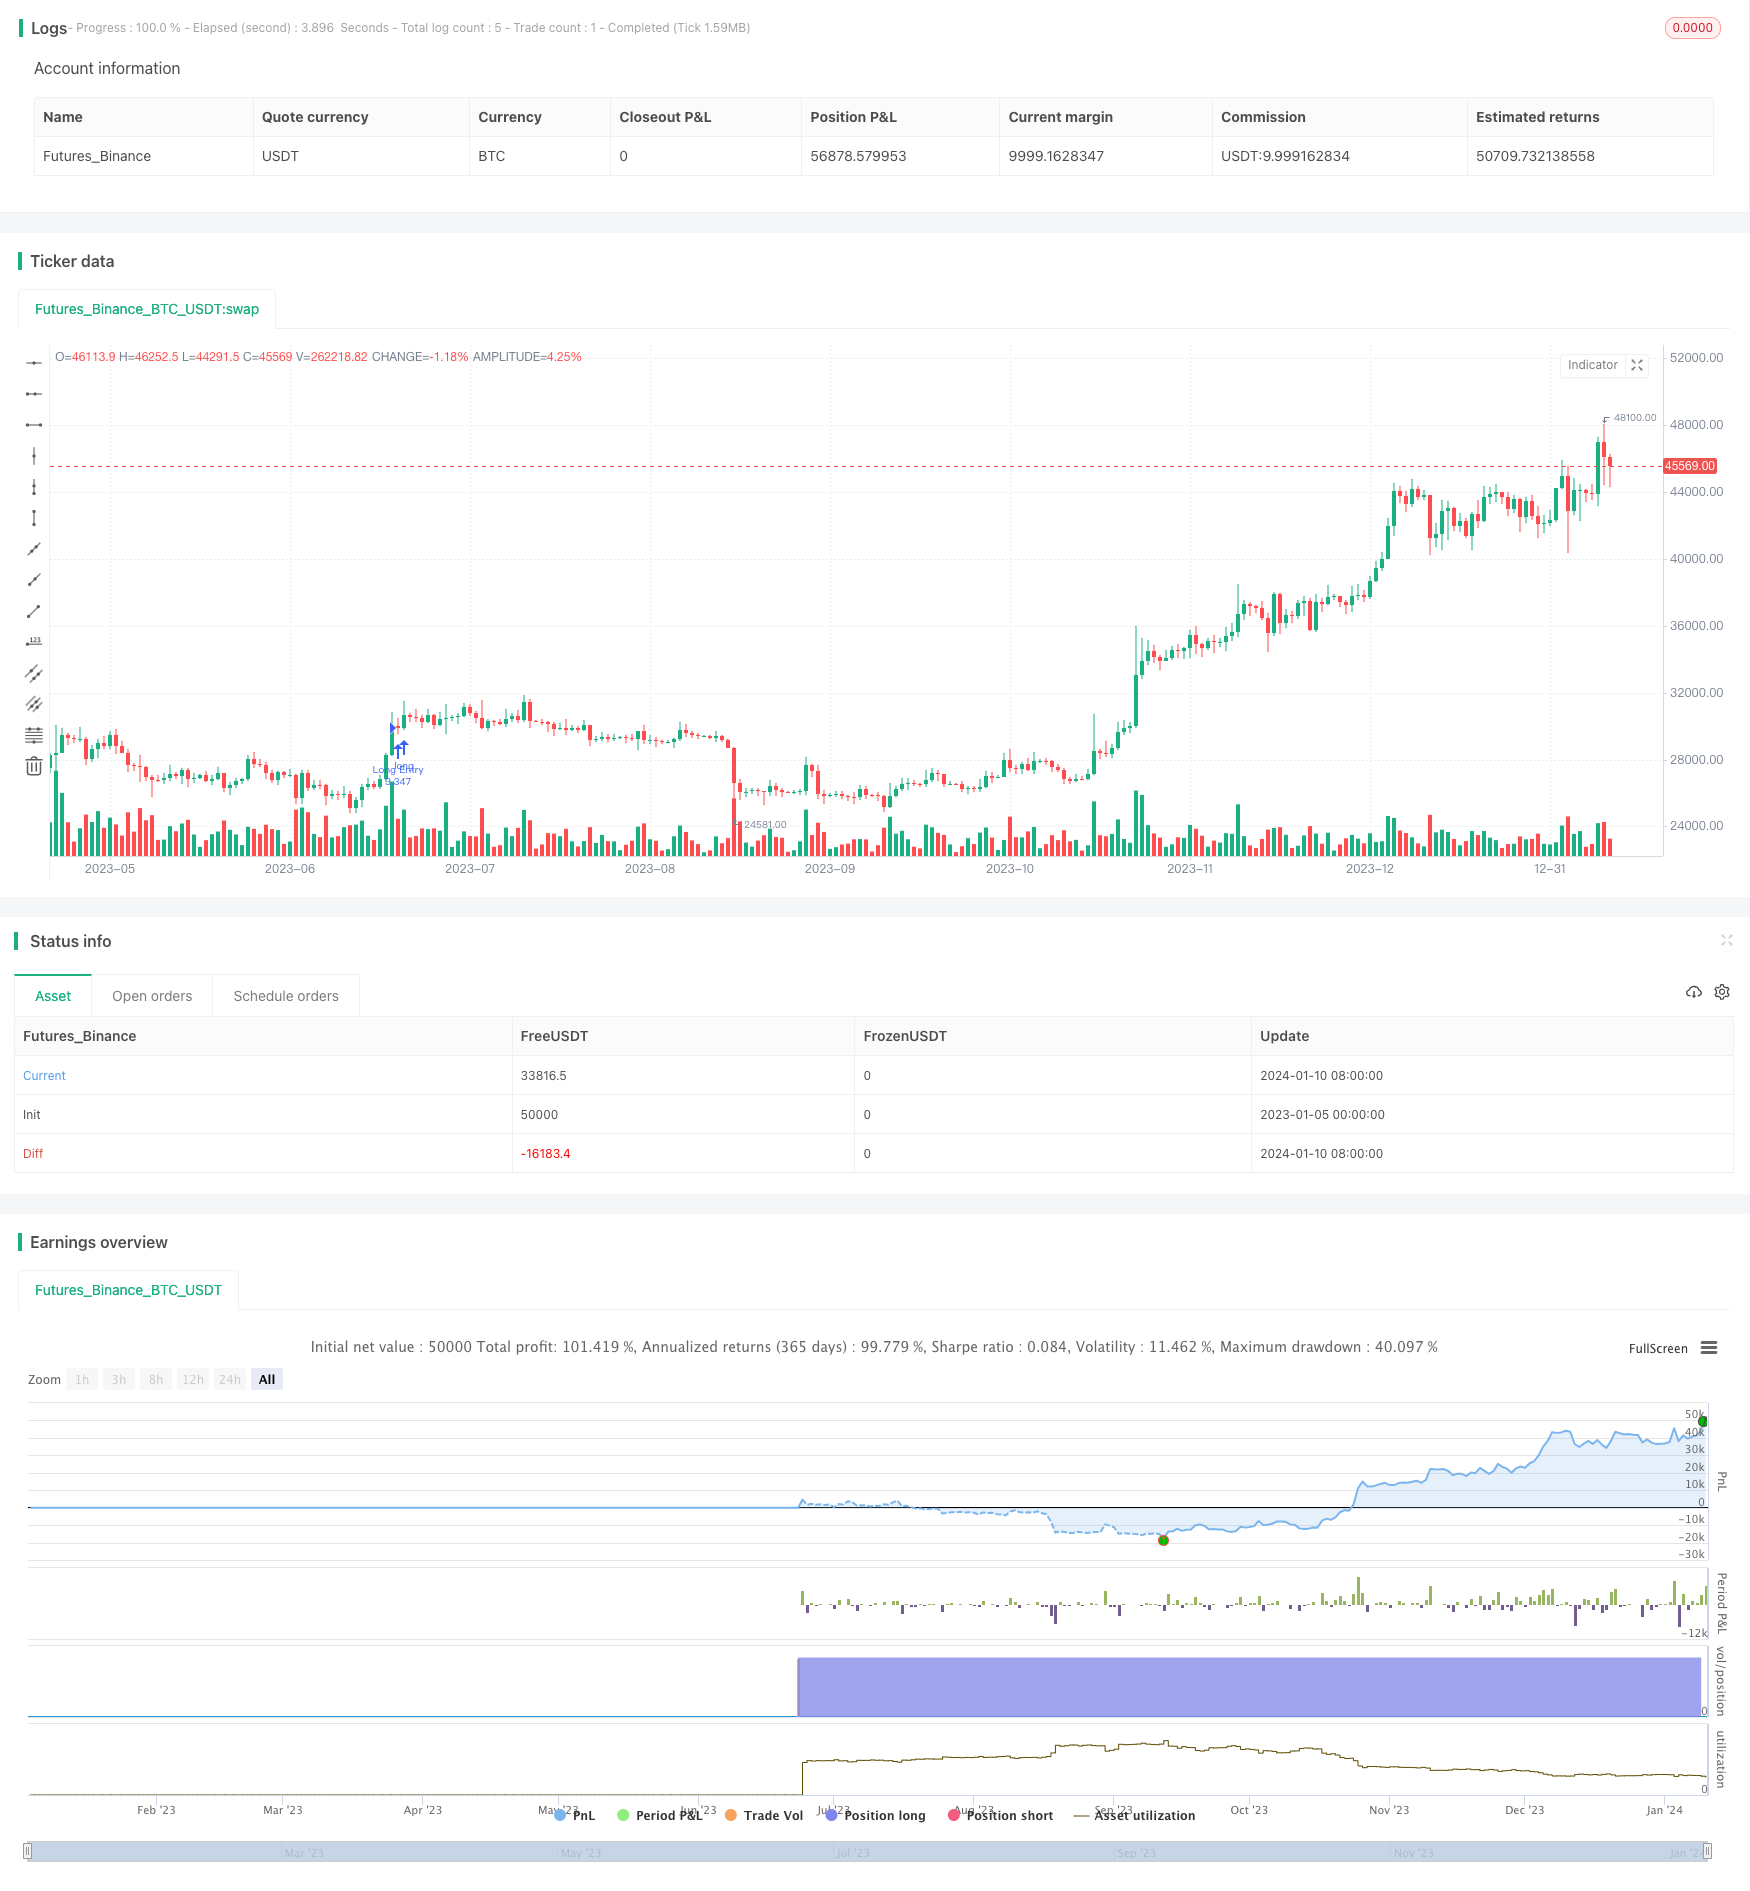
The exponential moving average (EMA) crossover is a common trading signal. This strategy uses the crossover of a fast EMA and a slow EMA to generate trading signals. Specifically, when the fast EMA crosses above the slow EMA, a long position is taken; when the fast EMA crosses below the slow EMA, a short position is taken.
This strategy uses the 20-day EMA as the fast EMA, the 50-day EMA as the medium EMA, and the 200-day EMA as the slow EMA. When both the 20-day EMA and 50-day EMA cross above the 200-day EMA, a long position is taken; when both cross below, a short position is taken. This helps filter out some false signals.
Advantages of the Strategy
- The moving average crossover strategy is simple and easy to understand and implement
- Using multiple moving averages can help filter out false signals
- Entry and exit signals are clear
Risks of the Strategy
- Prone to generating false signals during range-bound markets
- Moving averages have lag and may not capture turns quickly
- Unable to take full advantage of explosive moves
Enhancement Ideas
- Optimize moving average periods for different products and timeframes
- Add filters like volume and Bollinger Bands
- Combine with trend following and mean reversion for flexibility
Summary
The moving average crossover strategy is easy to grasp and is one of the foundational quantitative trading strategies. This implementation serves well as an introductory example. But in live trading, parameters would need optimization, and more advanced technical indicators should be added to filter signals and improve performance.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_int_1 | true | From Month |
| v_input_int_2 | true | From Day |
| v_input_int_3 | 2021 | From Year |
| v_input_int_4 | 10 | Thru Month |
| v_input_int_5 | 25 | Thru Day |
| v_input_int_6 | 2112 | Thru Year |
| v_input_1 | true | Show Date Range |
Source Pine Script
/*backtest
start: 2023-01-05 00:00:00
end: 2024-01-11 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © rt-maax

//@version=5

strategy(title = "rt maax EMA cross strategy", shorttitle = "rt maax ema ", overlay = true, precision = 8, max_bars_back = 200, pyramiding = 0, initial_capital = 100000,
     currency = currency.USD, default_qty_type = strategy.cash, default_qty_value = 100000, commission_type = "percent", commission_value = 0.27)
fastema = ta.ema (close , 50)
fema=ta.ema(close,20)
slowema= ta.ema(close,200)
price = close

// === INPUT BACKTEST RANGE ===
fromMonth = input.int(defval = 1,    title = "From Month",  minval = 1, maxval = 12)
fromDay   = input.int(defval = 1,    title = "From Day",    minval = 1, maxval = 31)
fromYear  = input.int(defval = 2021, title = "From Year",   minval = 1970)
thruMonth = input.int(defval = 10,    title = "Thru Month",  minval = 1, maxval = 12)
thruDay   = input.int(defval = 25,    title = "Thru Day",    minval = 1, maxval = 31)
thruYear  = input.int(defval = 2112, title = "Thru Year",   minval = 1970)

// === INPUT SHOW PLOT ===
showDate  = input(defval = true, title = "Show Date Range")

// === FUNCTION EXAMPLE ===


longCondition1= ta.crossover (fema , fastema)
longcondition2= fema> slowema
longcondition3=fastema>slowema


if (longCondition1 and longcondition2 and longcondition3 )
    stoploss=low*0.97
    takeprofit=high*1.12
    strategy.entry("Long Entry", strategy.long)
    strategy.exit ("exit","long",stop=stoploss,limit=takeprofit)


shortCondition1 = ta.crossunder (fema , fastema )
shortcondition2= fastema< slowema
shortcondition3= fema< slowema

if (shortCondition1 and shortcondition2 and shortcondition3 )
    stoploss=low*0.97
    takeprofit=high*1.5
    strategy.entry("Short Entry", strategy.short)
    strategy.exit("exit","short",stop=stoploss,limit=takeprofit)
Published by ChaoZhang on the FMZ strategy square · last modified 2024-01-12. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Exponential-Moving-Average-Crossover-Strategy-438485.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- Bollinger Band Moving Average Crossover StrategyPine Script · Trend following · 1h
- Bollinger Bands and EMA Trend Following StrategyPine Script · Trend following · 1h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Dual Moving Average Crossover Dynamic Position Optimization Strategy with EMA Cross Signal SystemPine Script · Trend following · 1h
- EMA Cross Trend Following Strategy with SMA Stop Loss and Re Entry MechanismPine Script · Trend following · 1h