Strategy vault / Machine learning
Fast Slow Dual Moving Average Trading Strategy
The dual moving average trading strategy generates trading signals by calculating fast and slow moving averages and watching for crosses. When the fast moving average crosses above the slow moving average, a long…
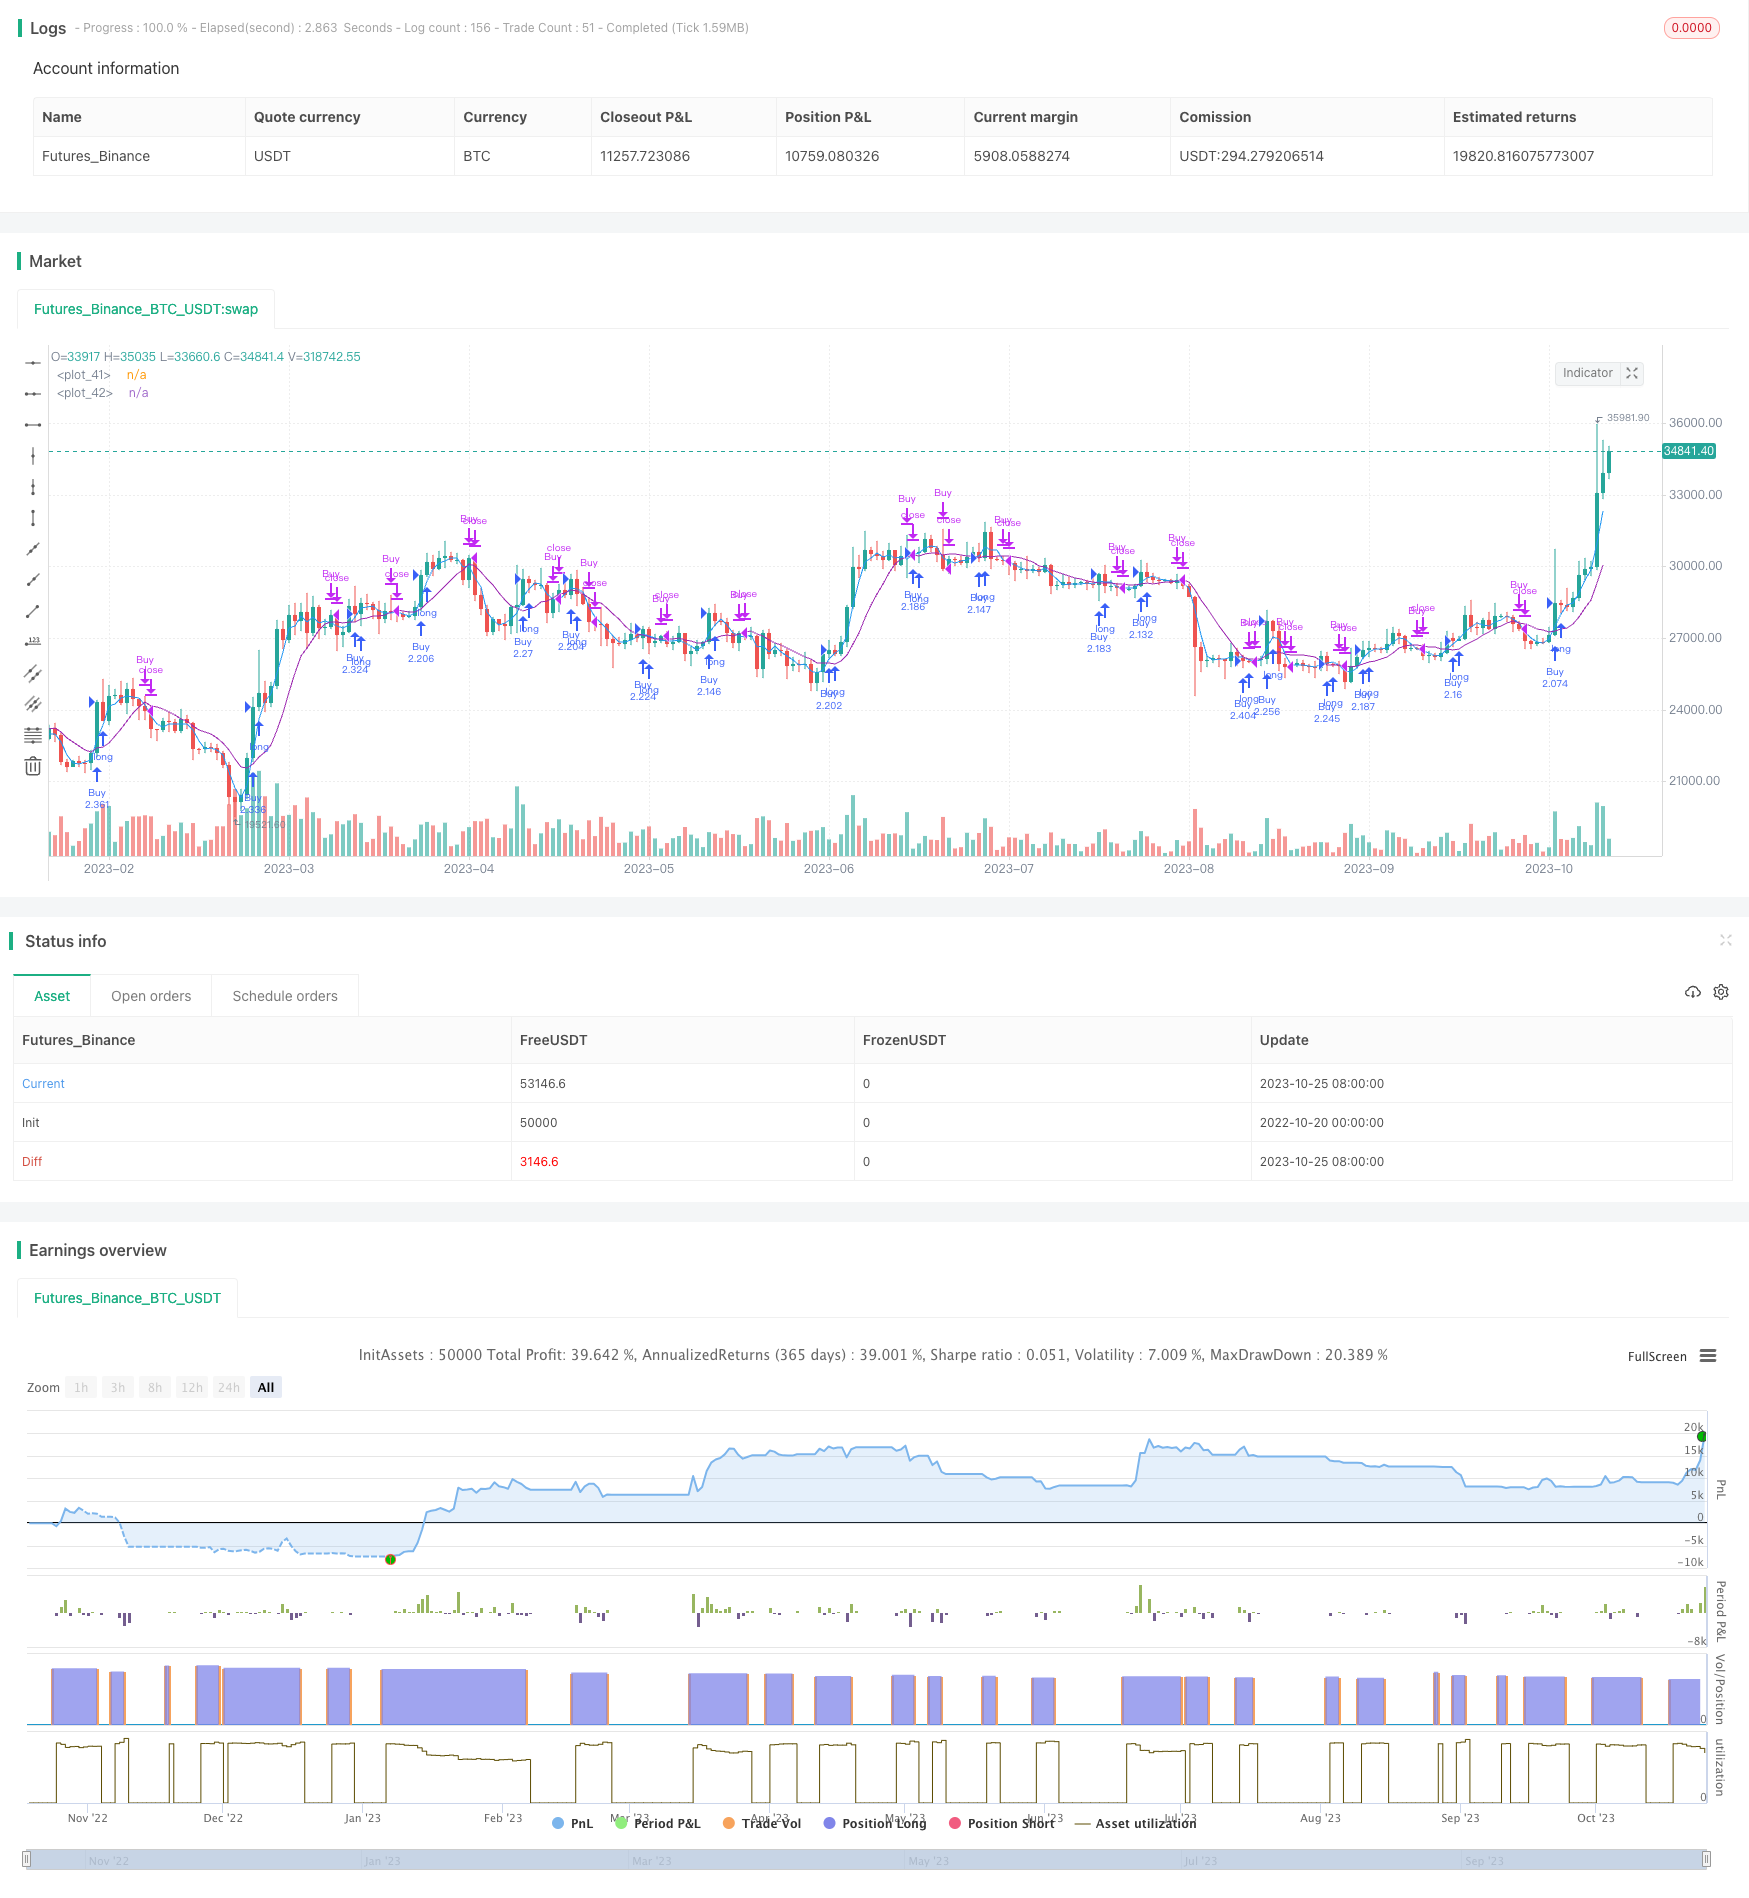
Overview
The dual moving average trading strategy generates trading signals by calculating fast and slow moving averages and watching for crosses. When the fast moving average crosses above the slow moving average, a long position is taken. When the fast moving average crosses below the slow moving average, a short position is taken. The strategy can be used for both trend trading and countertrend trading.
Strategy Logic
The strategy first sets the lengths of the fast moving average maFastLength and the slow moving average maSlowLength. It then calculates the fast moving average fastMA and the slow moving average slowMA. The fast moving average reacts more quickly to price changes and is used to judge the current trend, while the slow moving average reacts more slowly and is used to determine the direction of the trend.
When the fast moving average crosses above the slow moving average, a long entry signal goLong() is generated. When the fast moving average crosses below the slow moving average, existing long positions are closed with the killLong() signal.
The strategy can be set to long only, short only, or allow both long and short trades.
In long only mode, long positions are entered on the goLong() signal and exited on the killLong() signal.
In short only mode, short positions are entered on the killLong() signal and exited on the goLong() signal.
In swapping mode, long positions are entered on goLong(), closed and reversed to short on killLong().
The strategy also includes stop loss, trailing stop, messaging and other optional features.
Advantages
Simple and easy to implement.
Flexibility to go long, short or both.
Optional stop loss and trailing stop features.
Customizable messaging to alert trades.
Sensitive to trend changes in the market.
Adjustable parameters adapt to different markets.
Risks
Can generate excessive trades in choppy or ranging markets.
Slow to react to sudden news events.
Parameter selection impacts strategy performance.
Must follow signals strictly, avoid discretionary trading.
Trading costs can erode profits if not considered.
Enhancements
Add filters like RSI to avoid false signals.
Implement parameter optimization to find best settings.
Use dynamic stops to lock in profits and adjust.
Incorporate machine learning to aid trend prediction.
Optimize messaging for individual trading habits.
Conclusion
The dual moving average strategy is relatively simple and useful for catching strong trends. However, care should be taken to avoid whipsaws in low trend environments. Fine tuning parameters and adding auxiliary indicators or enhancements can further improve robustness and adaptability.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1_close | 0 | Fast MA Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_2 | 3 | Fast MA Period |
| v_input_3_close | 0 | Slow MA Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_4 | 9 | Slow MA Period |
| v_input_5 | false | Short only? |
| v_input_6 | true | Long only? |
| v_input_7 | false | Swap orders? |
| v_input_8 | false | Use Initial Stop Loss? |
| v_input_9 | 25 | Initial Stop Loss Points |
| v_input_10 | false | Use Trailing Stop? |
| v_input_11 | 120 | Trail Points |
| v_input_12 | false | Use Offset For Trailing Stop? |
| v_input_13 | 20 | Trail Offset Points |
| v_input_14 | Long entry message | Long entry message |
| v_input_15 | Long exit message | Long exit message |
| v_input_16 | Short entry message | Short entry message |
| v_input_17 | Short exit message | Short exit message |
| v_input_18 | timestamp(2021-01-01T00:00:00) | startDate |
| v_input_19 | timestamp(2021-12-31T00:00:00) | finishDate |
Source Pine Script
/*backtest
start: 2022-10-20 00:00:00
end: 2023-10-26 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

//@version=4

strategy("SMA Strategy", shorttitle="SMA Strategy", overlay=true, pyramiding=0, default_qty_type=strategy.percent_of_equity, default_qty_value=100)

// === Inputs ===
// short ma
maFastSource = input(defval=close, title="Fast MA Source")
maFastLength = input(defval=3, title="Fast MA Period", minval=1)

// long ma
maSlowSource = input(defval=close, title="Slow MA Source")
maSlowLength = input(defval=9, title="Slow MA Period", minval=1)

// Trade direction
shorting = input(defval=false, title="Short only?")
longonly = input(defval=true, title="Long only?")
swapping = input(defval=false, title="Swap orders?")
// risk management
useStop = input(defval=false, title="Use Initial Stop Loss?")
slPoints = input(defval=25, title="Initial Stop Loss Points", minval=1)
useTS = input(defval=false, title="Use Trailing Stop?")
tslPoints = input(defval=120, title="Trail Points", minval=1)
useTSO = input(defval=false, title="Use Offset For Trailing Stop?")
tslOffset = input(defval=20, title="Trail Offset Points", minval=1)

// Messages for buy and sell
message_long_entry  = input("Long entry message", title="Long entry message")
message_long_exit   = input("Long exit message", title="Long exit message")
message_short_entry = input("Short entry message", title="Short entry message")
message_short_exit  = input("Short exit message", title="Short exit message")

// Calculate start/end date and time condition
startDate  = input(timestamp("2021-01-01T00:00:00"), type = input.time)
finishDate = input(timestamp("2021-12-31T00:00:00"), type = input.time)

time_cond  = true
// === Vars and Series ===
fastMA = sma(maFastSource, maFastLength)
slowMA = sma(maSlowSource, maSlowLength)

plot(fastMA, color=color.blue)
plot(slowMA, color=color.purple)

goLong() =>
    crossover(fastMA, slowMA)
killLong() =>
    crossunder(fastMA, slowMA)

// Long only
if longonly
    strategy.entry("Buy", strategy.long, when=goLong() and time_cond, alert_message = message_long_entry)
    strategy.close("Buy", when=killLong() and time_cond, alert_message = message_long_exit)

// Short only
if shorting
    strategy.entry("Sell", strategy.short, when=killLong() and time_cond, alert_message = message_short_entry)
    strategy.close("Sell", when=goLong() and time_cond, alert_message = message_short_exit)

// Order Swapping
if swapping
    strategy.entry("Buy", strategy.long, when=goLong() and time_cond, alert_message = message_long_entry)
    strategy.entry("Sell", strategy.short, when=killLong() and time_cond, alert_message = message_short_entry)

if useStop
    strategy.exit("XLS", from_entry="Buy", stop=strategy.position_avg_price / 1.08, alert_message = message_long_exit)
    strategy.exit("XSS", from_entry="Sell", stop=strategy.position_avg_price * 1.08, alert_message = message_short_exit)
Published by ChaoZhang on the FMZ strategy square · last modified 2023-10-27. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Fast-Slow-Dual-Moving-Average-Trading-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- AI Driven Dynamic Volatility Adaptive Trend Breakout Trading StrategyPine Script · Machine learning · 2d
- AI Powered Volatility Price System Divergence Trading StrategyPine Script · Machine learning · 1h
- Configurable BBRSIAroon Strategy BacktestPine Script · Machine learning · 5m
- EMA and RSI Quantitative Trading StrategyPine Script · Machine learning · 1h
- High Frequency Hybrid Technical Analysis Quantitative StrategyPine Script · Machine learning · 15m
- KRK aDa Stochastic Slow Mean Reversion Strategy with AI Enhancements KRK aDaPine Script · Machine learning · 1h