Strategy vault / Trend following
FTSMA Trend is your frend
This my new solid strategy: if you belive that "TREND IS YOUR FRIEND" this is for you! I have tested with many pairs and at many timeframes and have profit with just minor changes in settings. I suggest to use it for…
This my new solid strategy: if you belive that "TREND IS YOUR FRIEND" this is for you!
I have tested with many pairs and at many timeframes and have profit with just minor changes in settings. I suggest to use it for intraday trading.
VERY IMPORTANT NOTE: this is a trend following strategy, so the target is to stay in the trade as much as possible. If your trading style is more focused on scalping and/or pullbaks, this strategy is not for you.
This strategy uses moving averages applied to Fourier waves for forecasting trend direction.
How strategy works:
- Buy when fast MA is above mid MA and price is above slow MA, which acts as a trend indicator.
- Sell when fast MA is below mid MA and price is below slow MA, which acts as a trend indicator.
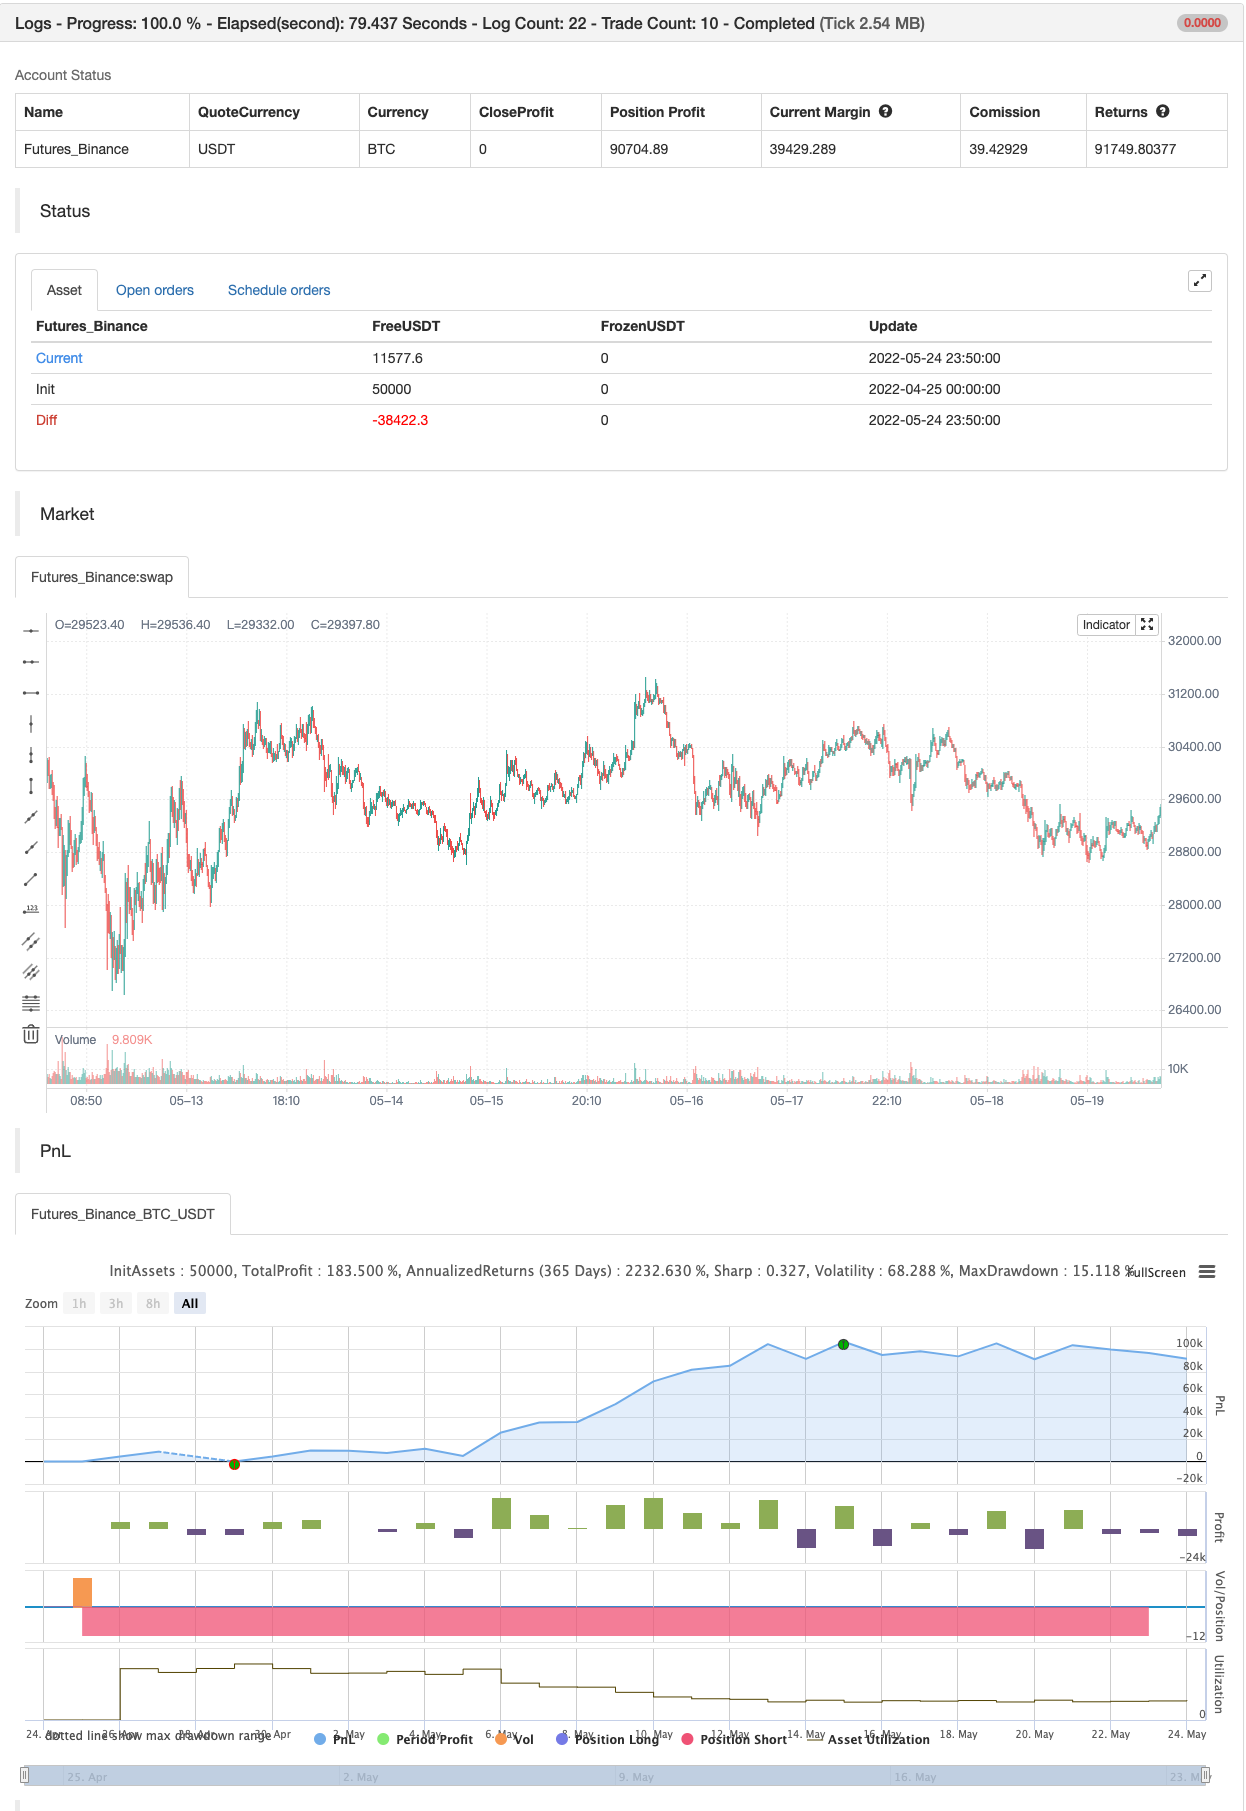
Strategy uses a lot of pyramiding orders because when you are in a flat market phase it will close 1 or 2 orders with a loss, but when a big trend starts, it will have profit in a lot of orders. So, if you analize carefully the strategy results, you will note that "Percent Profitable" is very low (30% in this case) because strategy opened a lot of orders also in flat markets with small losses, BUT "Avg # bars in winning trades" is very high and overall Profit is very high: when a big trend starts, orders are kept open for long time generating big profits.
Thanks to all pinescripters mentioned in the code for their snippets.
I have also a study with alerts. Next improvement (only to whom is interested to this script and follows me): study with alerts on multiple tickers all at one. Leave a comment if you want to have access to study.
HOW TO USE STRATEGY AND STUDY TOGHETER: 1- Add to chart the strategy first, so your workspace will be as clean as possible. 2- Open the Strategy Tester tab at footer of the page. 3- Modify settings to get best results (Profit, Profit Factor, Drawdown). 4- Add study with alerts to your chart with same setting of strategy. I WILL PROVIDE A DETAILED QUICK INSTALLATION GUIDE WITH THE STUDY!
backtest
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1_close | 0 | Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_2 | 200 | Slow MA period |
| v_input_3 | 20 | Mid MA period |
| v_input_4 | 5 | Fast MA period |
| v_input_5 | true | Use MA |
| v_input_6 | true | First sinusoid |
| v_input_7 | 2 | Second sinusoid |
| v_input_8 | 3 | Third sinusoid |
| v_input_9 | 0 | MA Type: EMA | SMA | ALMA | FRAMA | RMA | SWMA | VWMA | WMA | LinearRegression |
| v_input_10 | false | Use linear regression? |
| v_input_11 | 13 | Linear regression lenght |
| v_input_12 | false | Linear regression offset |
| v_input_13 | 0 | Lookback Period: 64 | 4 | 8 | 16 | 32 | 2 | 128 | 256 | 512 | 1024 | 2048 | 4096 |
| v_input_14 | false | Take Profit Points |
| v_input_15 | false | Stop Loss Points |
| v_input_16 | false | Trailing Stop Loss Points |
| v_input_17 | false | Trailing Stop Loss Offset Points |
Source Pine Script
/*backtest
start: 2022-04-25 00:00:00
end: 2022-05-24 23:59:00
period: 10m
basePeriod: 1m
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © 03.freeman

//@version=4
strategy("FTSMA", overlay=true, precision=6, initial_capital=10000,calc_on_every_tick=true, pyramiding=10, default_qty_type=strategy.fixed, default_qty_value=10000, currency=currency.EUR)
src=input(close,"Source")
slowMA=input(200,"Slow MA period")
mediumMA=input(20,"Mid MA period")
fastMA=input(5,"Fast MA period")
plotSMA=input(true,"Use MA")
sin1=input(1,"First sinusoid",minval=1)
sin2=input(2,"Second sinusoid",minval=1)
sin3=input(3,"Third sinusoid",minval=1)
smoothinput = input('EMA', title = "MA Type", options =['EMA', 'SMA', 'ALMA','FRAMA','RMA', 'SWMA', 'VWMA','WMA','LinearRegression'])
linearReg=input(false, "Use linear regression?")
linregLenght=input(13, "Linear regression lenght")
linregOffset=input(0, "Linear regression offset")

//------FRAMA ma---------
ma(src, len) =>
    float result = 0
    int len1 = len/2
    frama_SC=200
    frama_FC=1
    e = 2.7182818284590452353602874713527
    w = log(2/(frama_SC+1)) / log(e) // Natural logarithm (ln(2/(SC+1))) workaround
    H1 = highest(high,len1)
    L1 = lowest(low,len1)
    N1 = (H1-L1)/len1
    H2_ = highest(high,len1)
    H2 = H2_[len1]
    L2_ = lowest(low,len1)
    L2 = L2_[len1]
    N2 = (H2-L2)/len1
    H3 = highest(high,len)
    L3 = lowest(low,len)
    N3 = (H3-L3)/len
    dimen1 = (log(N1+N2)-log(N3))/log(2)
    dimen = iff(N1>0 and N2>0 and N3>0,dimen1,nz(dimen1[1]))
    alpha1 = exp(w*(dimen-1))
    oldalpha = alpha1>1?1:(alpha1<0.01?0.01:alpha1)
    oldN = (2-oldalpha)/oldalpha
    N = (((frama_SC-frama_FC)*(oldN-1))/(frama_SC-1))+frama_FC
    alpha_ = 2/(N+1)
    alpha = alpha_<2/(frama_SC+1)?2/(frama_SC+1):(alpha_>1?1:alpha_)
    frama = 0.0
    frama :=(1-alpha)*nz(frama[1]) + alpha*src
    result := frama
    result

// ----------MA calculation - ChartArt and modified by 03.freeman-------------
calc_ma(src,l) =>
    _ma = smoothinput=='SMA'?sma(src, l):smoothinput=='EMA'?ema(src, l):smoothinput=='WMA'?wma(src, l):smoothinput=='LinearRegression'?linreg(src, l,0):smoothinput=='VWMA'?vwma(src,l):smoothinput=='RMA'?rma(src, l):smoothinput=='ALMA'?alma(src,l,0.85,6):smoothinput=='SWMA'?swma(src):smoothinput=='FRAMA'?ma(sma(src,1),l):na

//----------------------------------------------


//pi = acos(-1)
// Approximation of Pi in _n terms --- thanks to e2e4mfck
f_pi(_n) =>
    _a = 1. / (4. * _n + 2)
    _b = 1. / (6. * _n + 3)
    _pi = 0.
    for _i = _n - 1 to 0
        _a := 1 / (4. * _i + 2) - _a / 4.
        _b := 1 / (6. * _i + 3) - _b / 9.
    _pi := (4. * _a) + (4. * _b) - _pi
pi=f_pi(20)

//---Thanks to xyse----https://www.tradingview.com/script/UTPOoabQ-Low-Frequency-Fourier-Transform/
//Declaration of user-defined variables
N = input(defval=64, title="Lookback Period", type=input.integer, minval=2, maxval=600, confirm=false, step=1, options=[2,4,8,16,32,64,128,256,512,1024,2048,4096])

//Real part of the Frequency Domain Representation
ReX(k) =>
    sum = 0.0
    for i=0 to N-1
        sum := sum + src[i]*cos(2*pi*k*i/N)
    return = sum

//Imaginary part of the Frequency Domain Representation
ImX(k) =>
    sum = 0.0
    for i=0 to N-1
        sum := sum + src[i]*sin(2*pi*k*i/N)
    return = -sum

//Get sinusoidal amplitude from frequency domain
ReX_(k) =>
    case = 0.0
    if(k!=0 and k!=N/2)
        case := 2*ReX(k)/N
    if(k==0)
        case := ReX(k)/N
    if(k==N/2)
        case := ReX(k)/N
    return = case

 //Get sinusoidal amplitude from frequency domain
ImX_(k) =>
    return = -2*ImX(k)/N

//Get full Fourier Transform
x(i, N) =>
    sum1 = 0.0
    sum2 = 0.0
    for k=0 to N/2
        sum1 := sum1 + ReX_(k)*cos(2*pi*k*i/N)
    for k=0 to N/2
        sum2 := sum2 + ImX_(k)*sin(2*pi*k*i/N)
    return = sum1+sum2

//Get single constituent sinusoid
sx(i, k) =>
    sum1 = ReX_(k)*cos(2*pi*k*i/N)
    sum2 = ImX_(k)*sin(2*pi*k*i/N)
    return = sum1+sum2
//Calculations for strategy
SLOWMA = plotSMA?calc_ma(close+sx(0,sin1),slowMA):close+sx(0,sin1)
MEDMA = plotSMA?calc_ma(close+sx(0,sin2),mediumMA):close+sx(0,sin2)
FASTMA = plotSMA?calc_ma(close+sx(0,sin3),fastMA):close+sx(0,sin3)

SLOWMA := linearReg?linreg(SLOWMA,linregLenght,linregOffset):SLOWMA
MEDMA := linearReg?linreg(MEDMA,linregLenght,linregOffset):MEDMA
FASTMA := linearReg?linreg(FASTMA,linregLenght,linregOffset):FASTMA

//Plot 3 Low-Freq Sinusoids
plot(SLOWMA, color=color.green)
plot(MEDMA, color=color.red)
plot(FASTMA, color=color.blue)

//  Strategy: (Thanks to JayRogers)
// === STRATEGY RELATED INPUTS ===
// the risk management inputs
inpTakeProfit   = input(defval = 0, title = "Take Profit Points", minval = 0)
inpStopLoss     = input(defval = 0, title = "Stop Loss Points", minval = 0)
inpTrailStop    = input(defval = 0, title = "Trailing Stop Loss Points", minval = 0)
inpTrailOffset  = input(defval = 0, title = "Trailing Stop Loss Offset Points", minval = 0)

// === RISK MANAGEMENT VALUE PREP ===
// if an input is less than 1, assuming not wanted so we assign 'na' value to disable it.
useTakeProfit   = inpTakeProfit  >= 1 ? inpTakeProfit  : na
useStopLoss     = inpStopLoss    >= 1 ? inpStopLoss    : na
useTrailStop    = inpTrailStop   >= 1 ? inpTrailStop   : na
useTrailOffset  = inpTrailOffset >= 1 ? inpTrailOffset : na

longCondition = FASTMA>MEDMA and close > SLOWMA             //crossover(FASTMA, MEDMA) and close > SLOWMA
if (longCondition)
    strategy.entry("Long Entry", strategy.long)

shortCondition = FASTMA<MEDMA and close < SLOWMA            //crossunder(FASTMA, MEDMA) and close < SLOWMA
if (shortCondition)
    strategy.entry("Short Entry", strategy.short)

// === STRATEGY RISK MANAGEMENT EXECUTION ===
// finally, make use of all the earlier values we got prepped
strategy.exit("Exit Buy", from_entry = "Long Entry", profit = useTakeProfit, loss = useStopLoss, trail_points = useTrailStop, trail_offset = useTrailOffset)
strategy.exit("Exit Sell", from_entry = "Short Entry", profit = useTakeProfit, loss = useStopLoss, trail_points = useTrailStop, trail_offset = useTrailOffset)Published by ChaoZhang on the FMZ strategy square · last modified 2022-05-26. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/FTSMA-Trend-is-your-frend.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- ADX MA and EMA Long Only Trend Tracking StrategyPine Script · Trend following · 1d
- ATR and Moving Average Crossover Hybrid StrategyPine Script · Trend following · 1h
- Bollinger Band Moving Average Crossover StrategyPine Script · Trend following · 1h
- Bollinger Bands and EMA Trend Following StrategyPine Script · Trend following · 1h
- Bollinger Bands and RSI Trend Following StrategyPine Script · Trend following · 1h
- Candlestick Pattern Trend Filter StrategyPine Script · Trend following · 1d