Golden Cross with Bollinger Bands Momentum Strategy
This strategy combines moving average, Bollinger bands and volume weighted average price (VWAP) indicators. It enters long positions when the golden cross forms and the fast moving average breaks above the slow one…
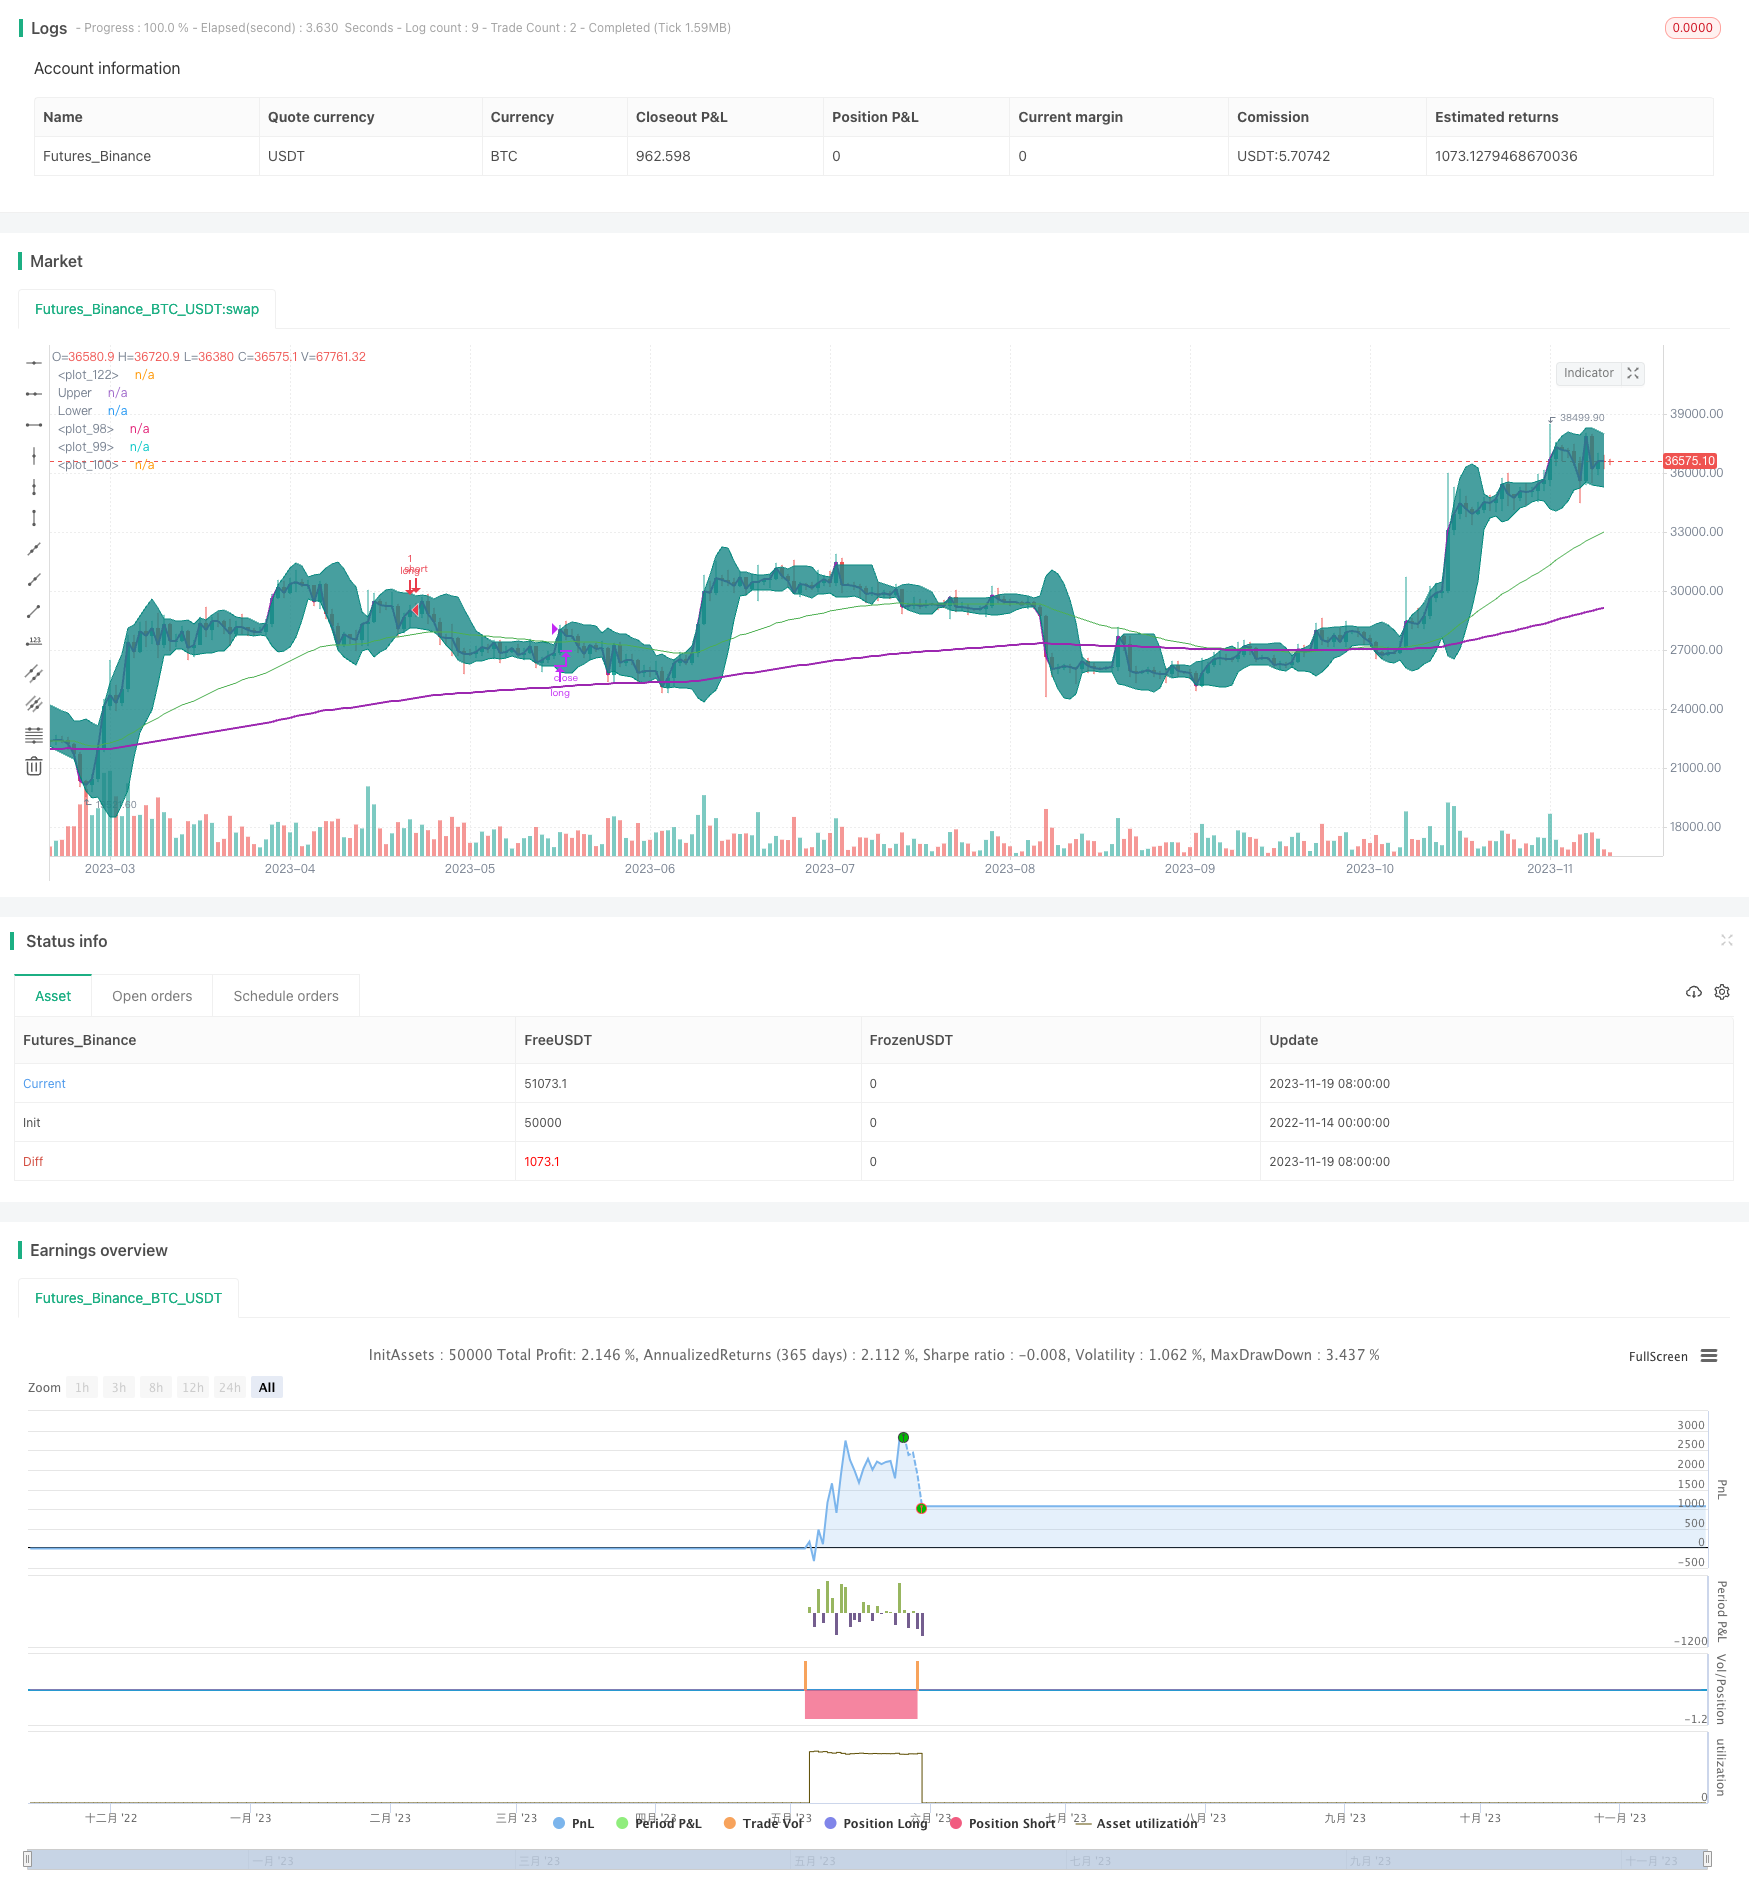
Overview
This strategy combines moving average, Bollinger bands and volume weighted average price (VWAP) indicators. It enters long positions when the golden cross forms and the fast moving average breaks above the slow one. The strategy also utilizes the Bollinger band channel and only considers entering when the price touches the lower band, thus avoiding frequent entries and exits amid market fluctuations.
Strategy Logic
The core logic relies on moving averages to determine the trend direction, and Bollinger bands to locate the fluctuation range for buying signals. Specifically, it has the following key rules:
Construct the golden cross system using 50-day EMA and 200-day EMA. An up trend is identified when the fast EMA crosses above the slow EMA.
When the price is above VWAP, it indicates the price is in an upward phase which favors long positions.
When the price just touches or breaks the Bollinger lower band, it suggests the price may be near a rebound point thus providing a good opportunity.
Exit long positions with profit when the price exceeds the Bollinger upper band.
By combining these rules, the strategy is able to locate appropriate long entries in bull markets and set stop loss/profit taking to secure returns.
Advantages
The golden cross system determines the major trend direction, avoiding small wins and losses amid consolidations.
VWAP gauges the price wave direction for more precise buying signals.
The Bollinger bands add resilience by locating buys while setting stop loss/profit taking locks in gains.
Multiple confirming indicators enhance reliability.
Risks and Solutions
The golden cross may give false signals. Fine tune the MA periods and add other confirmations.
Improper Bollinger parameters could render the strategy ineffective. Optimize periods and standard deviation.
A stop loss threshold too wide fails to effectively limit losses. Tighten the stop loss range to ensure controllable risks.
Optimization Directions
Optimize MA combinations by testing different parameters to find the best.
Test Bollinger periods and parameter sets for better bandwidth and volatility.
Test and tune stop loss ranges for balancing risk control and avoiding premature triggering.
Conclusion
This strategy strikes a balance between discovering opportunities and controlling risks by integrating MA, Bollinger and VWAP analysis for entries. Continuous fine tuning and optimization will allow it to capitalize on sector and market trends over time.
Parameters
| Name | Default | What it controls |
|---|---|---|
| v_input_1 | true | From Day |
| v_input_2 | 6 | From Month |
| v_input_3 | 2020 | From Year |
| v_input_4 | true | To Day |
| v_input_5 | 8 | To Month |
| v_input_6 | 2020 | To Year |
| v_input_7 | 50 | fast EMA |
| v_input_8 | 200 | slow EMA |
| v_input_9 | 7 | BB SMA Length |
| v_input_10_close | 0 | BB Source: close | high | low | open | hl2 | hlc3 | hlcc4 | ohlc4 |
| v_input_11 | 0 | strategy to use: BB | BB_percentageB |
| v_input_12 | true | Stop Loss% |
| v_input_13 | 2 | StdDev |
| v_input_14 | false | Offset |
Source Pine Script
/*backtest
start: 2022-11-14 00:00:00
end: 2023-11-20 00:00:00
period: 1d
basePeriod: 1h
exchanges: [{"eid":"Futures_Binance","currency":"BTC_USDT"}]
*/

// This source code is subject to the terms of the Mozilla Public License 2.0 at https://mozilla.org/MPL/2.0/
// © mohanee

//@version=4
strategy(title="VWAP and BB strategy [$$]", overlay=true,pyramiding=2, default_qty_value=1, default_qty_type=strategy.fixed,    initial_capital=10000, currency=currency.USD)


fromDay = input(defval = 1, title = "From Day", minval = 1, maxval = 31)
fromMonth = input(defval = 6, title = "From Month", minval = 1, maxval = 12)
fromYear = input(defval = 2020, title = "From Year", minval = 1970)

// To Date Inputs
toDay = input(defval = 1, title = "To Day", minval = 1, maxval = 31)
toMonth = input(defval = 8, title = "To Month", minval = 1, maxval = 12)
toYear = input(defval = 2020, title = "To Year", minval = 1970)

// Calculate start/end date and time condition
DST = 1 //day light saving for usa
//--- Europe
London = iff(DST==0,"0000-0900","0100-1000")
//--- America
NewYork = iff(DST==0,"0400-1300","0500-1400")
//--- Pacific
Sydney = iff(DST==0,"1300-2200","1400-2300")
//--- Asia
Tokyo = iff(DST==0,"1500-2400","1600-0100")

//-- Time In Range
timeinrange(res, sess) => time(res, sess) != 0

london = timeinrange(timeframe.period, London)
newyork = timeinrange(timeframe.period, NewYork)

startDate = timestamp(fromYear, fromMonth, fromDay, 00, 00)
finishDate = timestamp(toYear, toMonth, toDay, 00, 00)
time_cond = time >= startDate and time <= finishDate


is_price_dipped_bb(pds,source1) =>
    t_bbDipped=false
    for i=1 to pds
        t_bbDipped:=  (t_bbDipped   or  close[i]<source1) ? true : false
        if t_bbDipped==true
            break
        else
            continue

    t_bbDipped


is_bb_per_dipped(pds,bbrSrc) =>
    t_bbDipped=false
    for i=1 to pds
        t_bbDipped:=  (t_bbDipped   or  bbrSrc[i]<=0) ? true : false
        if t_bbDipped==true
            break
        else
            continue

    t_bbDipped


// variables  BEGIN
shortEMA = input(50, title="fast EMA", minval=1)
longEMA = input(200, title="slow EMA", minval=1)

//BB

smaLength = input(7, title="BB SMA Length", minval=1)
bbsrc = input(close, title="BB Source")

strategyCalcOption = input(title="strategy to use", type=input.string, options=["BB", "BB_percentageB"],      defval="BB")


//addOnDivergence = input(true,title="Add to existing on Divergence")
//exitOption = input(title="exit on RSI or BB", type=input.string, options=["RSI", "BB"],      defval="BB")

//bbSource = input(title="BB  source", type=input.string, options=["close", "vwap"],      defval="close")

//vwap_res = input(title="VWAP Resolution", type=input.resolution, defval="session")
stopLoss = input(title="Stop Loss%", defval=1, minval=1)

//variables  END

longEMAval= ema(close, longEMA)
shortEMAval= ema(close, shortEMA)
ema200val = ema(close, 200)


vwapVal=vwap(close)


// Drawings

//plot emas
plot(shortEMAval, color = color.green, linewidth = 1, transp=0)
plot(longEMAval, color = color.orange, linewidth = 1, transp=0)
plot(ema200val, color = color.purple, linewidth = 2, style=plot.style_line ,transp=0)


//bollinger calculation
mult = input(2.0, minval=0.001, maxval=50, title="StdDev")
basis = sma(bbsrc, smaLength)
dev = mult * stdev(bbsrc, smaLength)
upperBand = basis + dev
lowerBand = basis - dev
offset = input(0, "Offset", type = input.integer, minval = -500, maxval = 500)

bbr = (bbsrc - lowerBand)/(upperBand - lowerBand)
//bollinger calculation

//plot bb
//plot(basis, "Basis", color=#872323, offset = offset)
p1 = plot(upperBand, "Upper", color=color.teal, offset = offset)
p2 = plot(lowerBand, "Lower", color=color.teal, offset = offset)
fill(p1, p2, title = "Background", color=#198787, transp=95)


plot(vwapVal, color = color.purple, linewidth = 2, transp=0)


// Colour background

//barcolor(shortEMAval>longEMAval and close<=lowerBand ? color.yellow: na)


//longCondition=  shortEMAval > longEMAval and  close>open and  close>vwapVal
longCondition=  ( shortEMAval > longEMAval  and close>open and close>vwapVal and close<upperBand ) //and time_cond //     and  close>=vwapVal


//Entry
strategy.entry(id="long", comment="VB LE" , long=true,  when= longCondition and ( strategyCalcOption=="BB"? is_price_dipped_bb(10,lowerBand) : is_bb_per_dipped(10,bbr)  )   and strategy.position_size<1 )   //is_price_dipped_bb(10,lowerBand))  //and strategy.position_size<1       is_bb_per_dipped(15,bbr)


//add to the existing position
strategy.entry(id="long", comment="Add" , long=true,  when=strategy.position_size>=1 and close<strategy.position_avg_price and close>vwapVal) //and time_cond)

barcolor(strategy.position_size>=1  ? color.blue: na)


strategy.close(id="long", comment="TP Exit",   when=crossover(close,upperBand) )

//stoploss
stopLossVal =   strategy.position_avg_price * (1-(stopLoss*0.01) )
//strategy.close(id="long", comment="SL Exit",   when= close < stopLossVal)

//strategy.risk.max_intraday_loss(stopLoss, strategy.percent_of_equity)Published by ChaoZhang on the FMZ strategy square · last modified 2023-11-21. Collected in the Quant Trading Vault. Unvalidated research: re-test with your own data and costs before trusting it.
Build this with AgenKit
A spec is not a trading system. Paste this into your coding agent and AgenKit runs a specialist team — architecture, test-first build, risk gates, review — with paper trading on by default.
/agenkit build a production-grade trading bot with a backtest engine, risk controls and paper trading by default from strategies/Golden-Cross-with-Bollinger-Bands-Momentum-Strategy.md- npx agenkit install engineering-kit in your project
- Paste the command into your agent and approve each phase
- Get tests, backtest, risk controls and a paper-trading switch
Understand it first
Before you run this, read the lesson behind the idea and how to backtest it honestly. Specs like this one are the survivors of an unknown number of trials; deflate their results accordingly.
Related specs
- Multi Indicator Comprehensive Analysis Quantitative Trading Strategy Trend Momentum and Volatility Collaborative Prediction ModelPine Script · Momentum · 3m
- Multi factor Fusion Strategy Multi factor Fusion StrategyPine Script · Momentum · 3h
- ADX Momentum Trend StrategyPine Script · Momentum · 10m
- Advanced Multi Indicator Trend Following and Momentum Quantitative Trading StrategyPine Script · Momentum · 1h
- Bollinger Bands Momentum Trend Following Quantitative StrategyPine Script · Momentum · 1d
- Momentum Indicator Aggregation Trading StrategyPine Script · Momentum · 1h